Crescent Capital BDC Beats And Covers Its Reset Dividend, But Shrinking Originations And A Half-Of-NAV Stock Price Define The Quarter
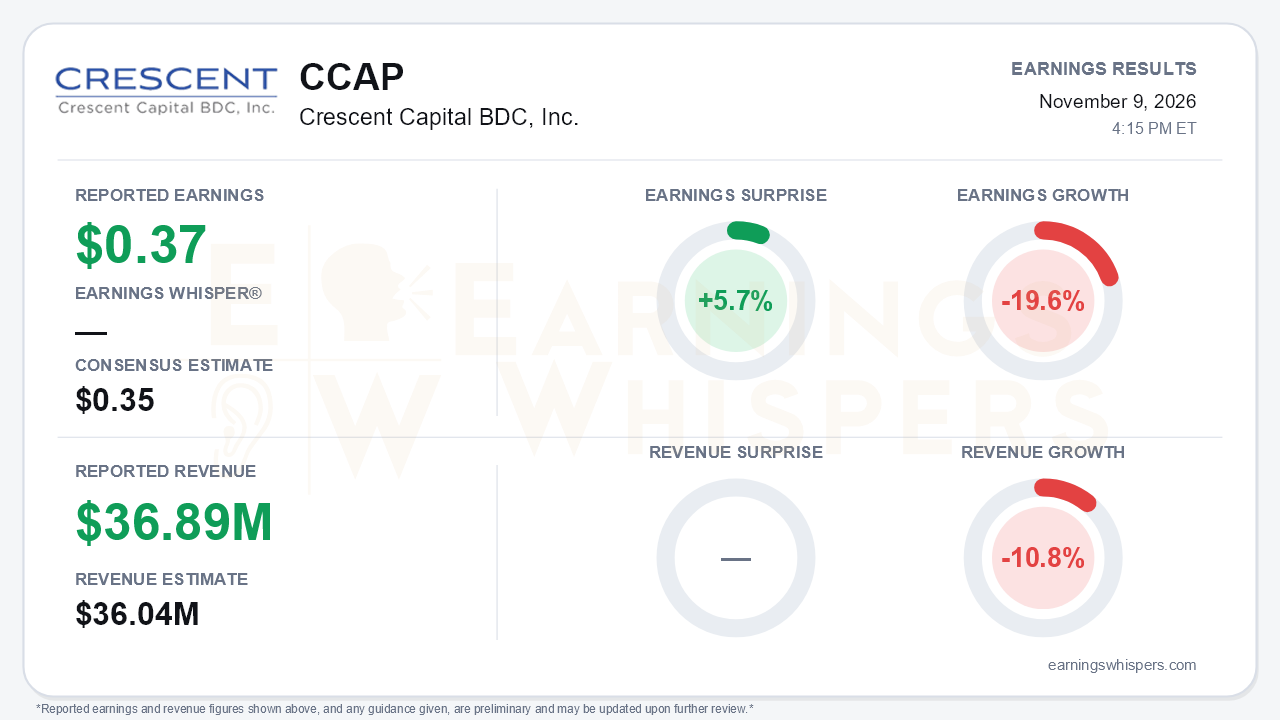
Crescent Capital BDC (NASDAQ: CCAP) cleared a low bar in the third quarter. Net investment income of $0.37 per share beat the $0.35 consensus by 5.7%, and investment income of $36.89 million topped expectations by 2.3%. Earnings still fell 19.6% from a year ago, and revenue fell 10.8%. The year-over-year declines have not reversed, but the sequential picture has steadied: NII ticked up from $0.36 in the second quarter and covered the reset $0.34 regular dividend. That base payout was cut from $0.42 earlier this year. The central tension is that the credit book appears to be stabilizing while the business that would rebuild earnings is shrinking. Management is answering that problem with capital-return measures rather than growth.
The beat deserves context. Sequential income growth was modest. Interest income rose $0.9 million to $35.6 million, which the company attributed to higher benchmark rates, and $0.5 million of that came from accelerated OID amortization tied to repayments. Dividend income slipped again to $0.9 million from $1.2 million in the second quarter and $3.0 million in the first, as distributions from the Logan JV continue to run off. Against the prior year, the weighted average yield on income-producing securities fell to 9.6% from 10.4%. Interest and financing costs rose to $15.1 million from $13.9 million. Lower management and incentive fees cushioned that squeeze. GAAP results improved to net income of $0.27 per share from a $0.09 loss in the second quarter, helped by much smaller realized losses. Still, NAV slipped again to $17.72 from $17.82, and it is down from $19.28 a year ago.
The call offered genuine evidence of credit stabilization:
- The NAV decline slowed to $0.10, from $0.45 in the second quarter and $0.83 in the first.
- There were no new non-accruals for a second straight quarter.
- Non-accruals eased to 4.7% of cost from 4.8% in the second quarter and 5.7% in the first.
- Names rated 4-5 fell to 2.4%.
- Interest coverage improved to 2.3x.
Bears still have legitimate ammunition. The watch list rose to 16% from 15% and 14% over the prior two quarters. The share of loans rated 1-2 dipped to 84%. Management noted more frequent maturity-extension requests from sponsors facing slow exits, and non-accruals at 4.7% remain elevated in absolute terms.
The demand picture is weakening. Management said sponsor LBO lending volume fell about 21% sequentially and roughly 60% year over year, and described the pipeline as "pretty light." Crescent platform commitments slowed to about $1.5 billion from more than $2.5 billion in the second quarter. CCAP's own gross deployment shrank to $24 million from $57 million in the second quarter and $115 million in the first, against $38.7 million of exits and repayments. Part of that slowdown is deliberate. Net leverage of 1.36x remains above the 1.1-1.3x target, so the company is prioritizing deleveraging. The trade-off is a portfolio that is getting smaller, which limits the path to earnings growth.
The forward-looking developments are where management's tone shifted from defensive to assertive on undervaluation:
- **Buyback:** The board authorized a $50 million repurchase program.
- **Sun Life purchases:** Sun Life plans to buy up to $25 million of stock in the open market. Both programs are designed to operate below NAV.
- **New joint venture:** Management outlined an unconsolidated JV seeded with roughly $150 million of first-lien assets. It would be funded with $30 million of CCAP equity, matching partner equity and an asset-based facility. It targets a low-to-mid-teens return on equity and is expected to close in the fourth quarter.
Management reaffirmed reaching target leverage by year-end, but that goal now depends heavily on the JV closing and on realizations. Organic rotation alone has been too slow to get there.
The market has not given the company the benefit of the doubt. Shares at $9.24 are down 15.8% since the open following the August report. They sit about 20% below the $11.56 200-day moving average and at roughly half of reported NAV. That discount explains why buybacks have become management's most potent lever. Investor sentiment also became meaningfully more negative, falling from -0.15 to -0.39 heading into the report. The Earnings Whispers trend signals are uniformly negative, with price, sequential growth, momentum and AVWAP all deteriorating.
The bottom line is that CCAP delivered a modest beat, covered its reset dividend and showed credit metrics that are no longer worsening quickly. Those are real improvements from the first half of the year. Yet originations are drying up, the portfolio is shrinking, and leverage reduction depends on a JV that has not yet closed. Meanwhile, NAV keeps edging lower and the watch list keeps growing. The repurchase programs could be accretive at this discount, but they are a response to a depressed share price, not a source of earnings growth. Until deployment recovers and NAV stops eroding, the stock is likely to be valued on credit risk rather than on NII coverage.
Read our earnings preview for Crescent Capital BDC, Inc.: https://www.earningswhispers.com/article/CCAP/22614
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-30 | |
| Aug-11 | |
| Aug-10 | |
| Aug-10 | |
| Jul-24 | |
| May-14 | |
| May-13 | |
| Apr-27 | |
| Mar-10 | |
| Mar-02 | |
| Mar-02 |
