Endeavour Silver Beats On EPS As Terronera Costs Fall, But Production Guidance Cut And Pitarrilla Delays Cloud The Quarter
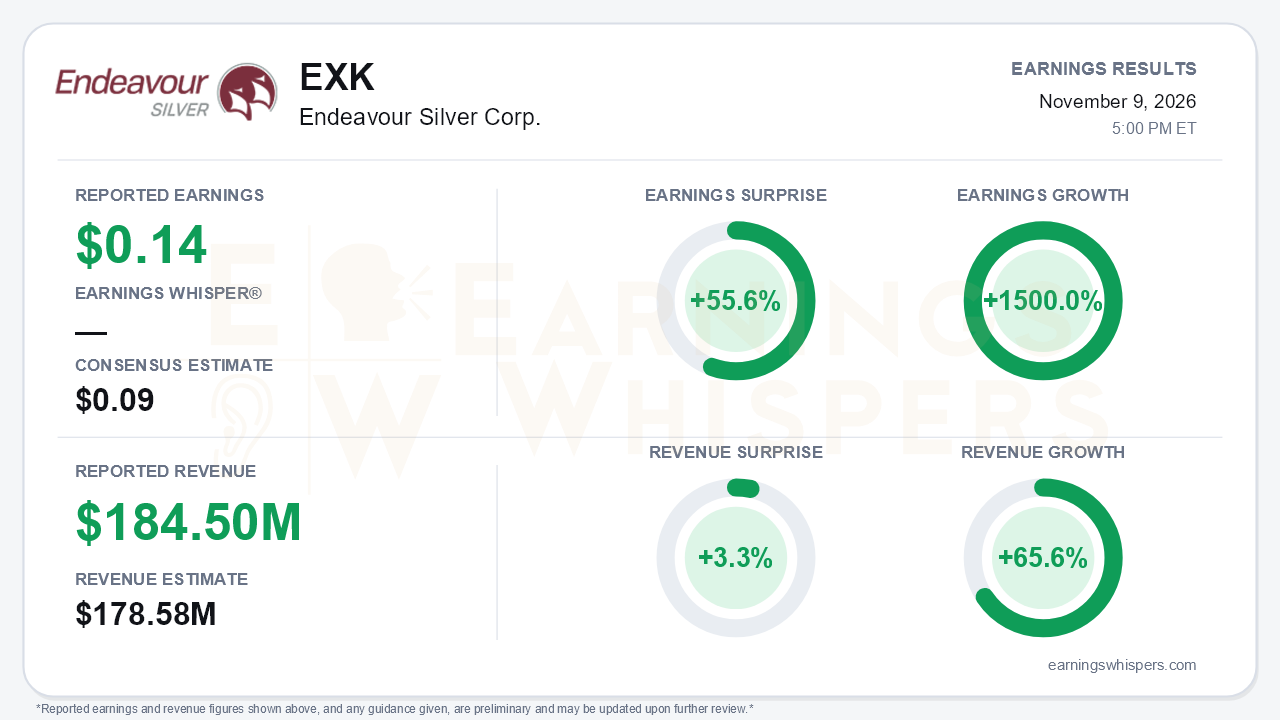
Endeavour Silver delivered a clear beat on its third-quarter numbers. The real story, though, is a company whose operations are improving faster than its outlook. Adjusted earnings of $0.14 per share topped the $0.09 consensus by 55.6% and marked a swing from a $0.01 loss a year earlier, which works out to 1500.0% growth. Revenue of $184.5 million beat the $178.58 million estimate by 3.3% and grew 65.6% year over year. Endeavour paired those results with its first formal cut to 2026 production guidance and higher unit-cost guidance at Terronera. That is the central tension: the cost curve is bending the right way, but the volume plan is not holding.
The quality of the beat deserves some scrutiny. On an IFRS basis, net earnings were $26.4 million, or $0.09 per share, which simply matched consensus. The adjusted figure excludes a $10.5 million loss on derivative and copper-stream revaluations and smaller fair-value and foreign-exchange items. The growth comparison also needs context. Endeavour's own release cites 29% revenue growth because it includes $31.5 million of pre-commercial Terronera revenue in the year-ago base. The 65.6% figure measures against reported revenue from operations of $111.4 million. Sequentially, the picture is softer. Revenue has slipped from about $210 million in Q1 to $185 million. Realized silver of $62.42 an ounce was well below the nine-month average of $72.16, and silver sold (1.90 million oz) lagged production (2.10 million oz) as finished-goods inventory nearly tripled year over year. That inventory build is a potential tailwind for Q4 sales, but it flattered neither revenue nor cash in the quarter.
Beneath the headline, the operating turnaround at Terronera is genuine:
- **Terronera unit costs:** direct operating costs per tonne fell from $195 in Q1 to $169 in Q2 and $156 in Q3.
- **Consolidated unit costs:** these fell from $187 to $152 per tonne over the same period.
- **Recoveries and power:** management said Terronera recoveries reached feasibility-study targets. The LNG power plant, worth roughly $8-10 per tonne, will run for all of Q4.
- **Cost per ounce:** Terronera posted negative cash costs and a $21.81 AISC. Consolidated AISC dropped to $29.54 from $37 in each of the first two quarters.
- **Cash generation:** mine operating cash flow rose 139% to $94.7 million. Cash climbed to $288 million from $236 million in Q2.
The weak spots are real, however. Guanaceví silver grades have run below plan all year, and its Q3 cash costs of $33.97 an ounce compare with $22.98 a year ago. A trunnion crack cut Guanaceví capacity for the last nine days of the quarter. A 12-day community-related suspension hit Terronera in August.
Those setbacks drove the guidance changes:
- **Production:** 2026 guidance was cut to 7.8-8.1 million oz silver, 42,000-43,500 oz gold and 13.7-14.3 million oz silver equivalent.
- **Unit costs:** Terronera direct operating cost guidance rose to $170-180 per tonne, and consolidated guidance to $155-165. Management's explanation was that first-half overruns from the slow LNG transition, contractor demobilization and the blockade were too large to recover.
- **Per-ounce costs:** cash cost and AISC guidance were left unrevised, even though year-to-date AISC of $34.32 has been running well above plan. Bears have legitimate ammunition there.
The forward catalyst list is substantial but carries execution baggage. The Pitarrilla feasibility study is expected within roughly ten days, and the project loan was converted into a $25 million revolver expandable to $100 million. New resource estimates for all three mines, including Endeavour's first 43-101 estimate at Kolpa, are due in early 2027. Management also points to higher Terronera grades in 2027 from the high-grade chute and the La Luz zone. Yet Pitarrilla has slipped on several fronts:
- the feasibility study moved from Q3 to November;
- the construction decision moved from early 2027 to mid-2027;
- early-works spending is behind budget;
- the tailings permit remains the gating item.
Investors have turned noticeably more cautious. Earnings Whispers sentiment fell from a roughly neutral 0.03 to -0.27, a meaningful shift into negative territory heading into the report. Shares at $8.34 are up 8.7% from the open after the July report, but they sit 13.4% below the 200-day moving average of $9.63. Price and AVWAP trend readings remain negative, which suggests the market has been discounting execution risk even as silver-driven profitability surged.
The bottom line is that Endeavour's Q3 showed the cost structure and balance sheet are moving in the right direction. Terronera is finally behaving like the asset it was built to be. However, a guidance cut, higher cost guidance and slipping Pitarrilla timelines mean the beat improves the earnings power argument more than the credibility argument. With sentiment souring and shares below their long-term average, the coming feasibility study and Q4 delivery against the reduced targets matter more than this quarter's surprise.
Read our earnings preview for Endeavour Silver Corp.: https://www.earningswhispers.com/article/EXK/22625
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-09 | |
| Nov-09 | |
| Nov-02 | |
| Oct-13 | |
| Oct-08 | |
| Sep-24 | |
| Sep-22 | |
| Sep-02 | |
| Aug-23 | |
| Aug-21 | |
| Aug-20 | |
| Aug-17 | |
| Aug-16 | |
| Aug-05 |
