Safe Bulkers Doubles Adjusted EPS And Raises Its Dividend Again, But Management's 2027 Outlook Has Turned More Cautious
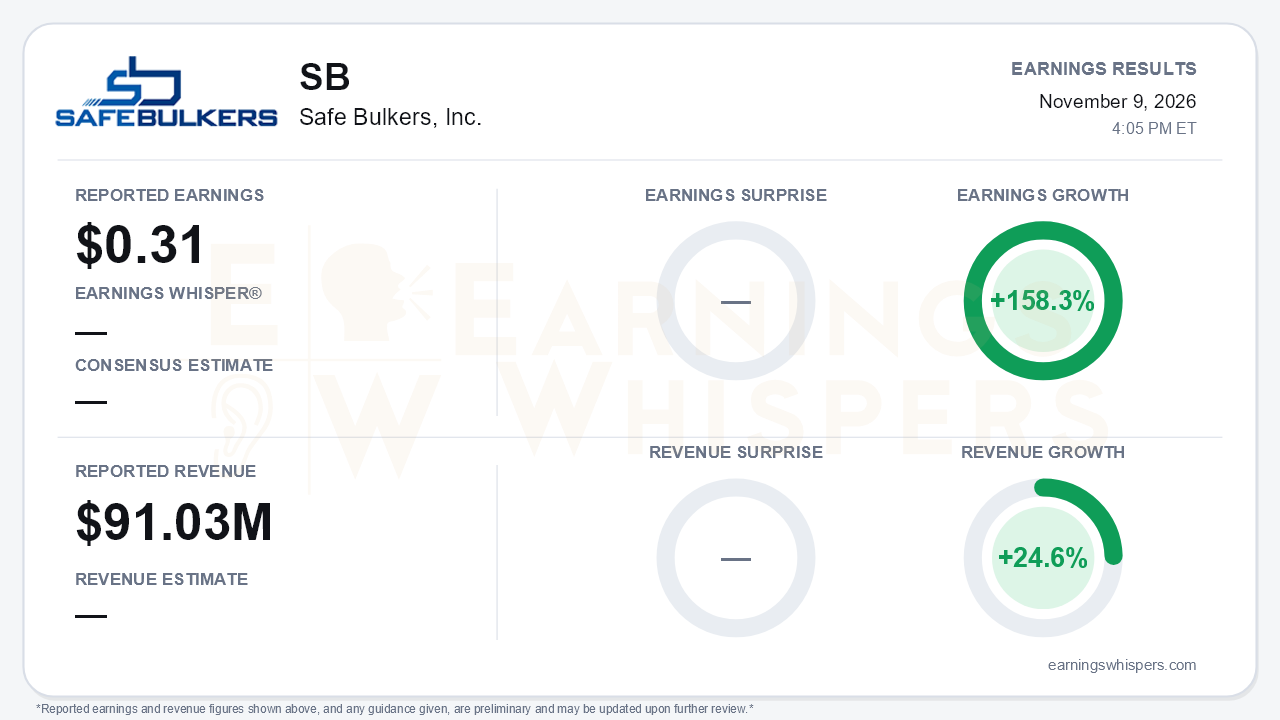
Safe Bulkers (NYSE: SB) delivered its strongest quarter of the current cycle. Adjusted earnings were $0.31 per share on revenue of $91.03 million for the September quarter. Earnings grew 158.3% year over year and revenue grew 24.6%. There was no consensus estimate or whisper number to measure against, so the quarter has to be judged on its trajectory. That trajectory is clearly upward. Adjusted EPS has climbed from $0.14 in the fourth quarter of 2025 to $0.18, $0.28 and now $0.31. The board lifted the quarterly dividend for a third straight time, to $0.09 from $0.075. The central tension is that record results arrived alongside a noticeably more guarded view of 2027. Management now frames the supply-demand balance as turning unfavorable beyond the next few quarters.
The quality of the quarter holds up, with a few caveats. GAAP EPS of $0.35 included a $6.8 million gain on the sale of the Pedhoulas Commander and Xenia. The adjusted figure strips that out, along with a $1.4 million foreign-currency loss, leaving adjusted net income of $34.0 million versus $13.9 million a year ago.
The engine was rates rather than volume:
- **Charter rates:** The time charter equivalent rate rose to $21,235 from $15,507 a year earlier, even though the company operated 45.3 vessels on average versus 46.5.
- **Scrubber earnings:** Scrubber-fitted vessels earned more as the US-Iran conflict and Strait of Hormuz disruption widened fuel spreads. Voyage expenses fell to $4.5 million from $7.3 million as a result.
- **Interest expense:** Interest costs dropped to $5.9 million on lower balances and a 5.10% average rate.
The sequential picture is less dramatic. TCE rose only about 3% from $20,642 in Q2, and adjusted EPS added three cents after a ten-cent jump the prior quarter. Growth is still positive, but the steep part of the recovery appears to be behind the company.
One data conflict is worth flagging. The call materials cite third-quarter adjusted EBITDA of $63.8 million. The press release reconciliation shows $53.8 million, up from $50.3 million in Q2 and $36.1 million a year earlier. The release figure ties to the reconciliation table and should be treated as the reliable number.
Costs moved the wrong way year over year:
- Daily operating expenses rose to $6,061 from $5,104, driven by three completed dry-dockings and newbuild pre-delivery costs.
- Excluding those items, daily opex rose 4% to $5,256, though that was actually down from $5,445 in Q2.
- Scheduled downtime will weigh on available days ahead, at 66 days in Q4 and 86 days in Q1 2027.
The call preserved a credible near-term story. The CEO said he is optimistic about the next two to three quarters. A Capesize, the Pelopidas, was fixed forward at $37,500 per day plus a scrubber premium starting in early 2027. Management also noted that Capesize rates for 2027 are being quoted well above $30,000. Contracted revenue rose to roughly $183 million from about $154 million in Q2.
Bears have legitimate ammunition, though:
- **Supply-demand outlook:** In a closed-Hormuz scenario, management's deck projects 2027 fleet supply growth of 3-4% against demand of roughly 1.5%. That reverses the Q2 framing of 2026 demand outpacing supply.
- **Orderbook:** The industry orderbook rose to about 15.4% of the fleet from roughly 13%, with nearly half in Capesizes.
- **China:** Chinese inventories and slowing GDP growth could soften import demand.
- **Visibility:** Management called visibility beyond six months unclear and does not expect scrapping to pick up soon.
- **Thin 2027 cover:** Only 19% of 2027 ownership days are contracted, and average Capesize charter duration slipped to 1.4 years from 1.7. That leaves substantial spot exposure into a year management itself flags as less favorable.
The balance sheet changed meaningfully:
- **Placement:** The €80.4 million Euronext Athens private placement of 12 million shares lifted total cash to $318.9 million. Liquidity is now roughly $515 million, net debt per vessel fell to $5.3 million from $8.0 million, and leverage dropped below 30%.
- **Refinancing:** The cash cushion arrives just as the €100 million 2.95% unsecured bond moves into the February 2027 maturity bucket. Any refinancing will almost certainly carry a higher coupon.
- **Dilution:** The share count is now about 113.8 million, while Q3 EPS was computed on a weighted average of 104.4 million shares. The full dilution will show up in coming quarters. The 515,469 shares repurchased under the buyback barely offset it.
- **Capital spending:** Management is declining to order more newbuilds at elevated yard prices. It has $247.6 million in remaining newbuild capex (as of September 30) and dry powder for possible second-hand acquisitions.
Market context is limited. No investor sentiment readings or current price were supplied. Shares opened at $7.98 after the July report, comfortably above the 200-day moving average, now at $7.12. The September placement was priced at €6.70 per share, which marks the level at which institutional buyers were willing to commit fresh capital. Investors should watch whether the stock holds above its longer-term average as the market weighs record earnings against the cooler 2027 framing.
The bottom line is that Safe Bulkers converted a strong charter market into record adjusted earnings, a rising dividend and a fortified balance sheet. Sequential momentum is flattening, though. Management's own outlook points to a less favorable supply-demand balance in 2027, a year in which most of the fleet remains uncontracted. Near-term earnings power looks secure. The durability of these returns beyond the next few quarters is now the open question.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-03 | |
| Oct-23 | |
| Oct-02 | |
| Sep-10 | |
| Aug-27 | |
| Jul-28 | |
| Jul-28 | |
| Jul-22 | |
| Jul-01 | |
| Jun-22 | |
| Jun-18 | |
| Jun-17 |
