SQM's Earnings Have Tripled But Its Stock Has Slumped; Q3 Must Show The Lithium Upswing Holds
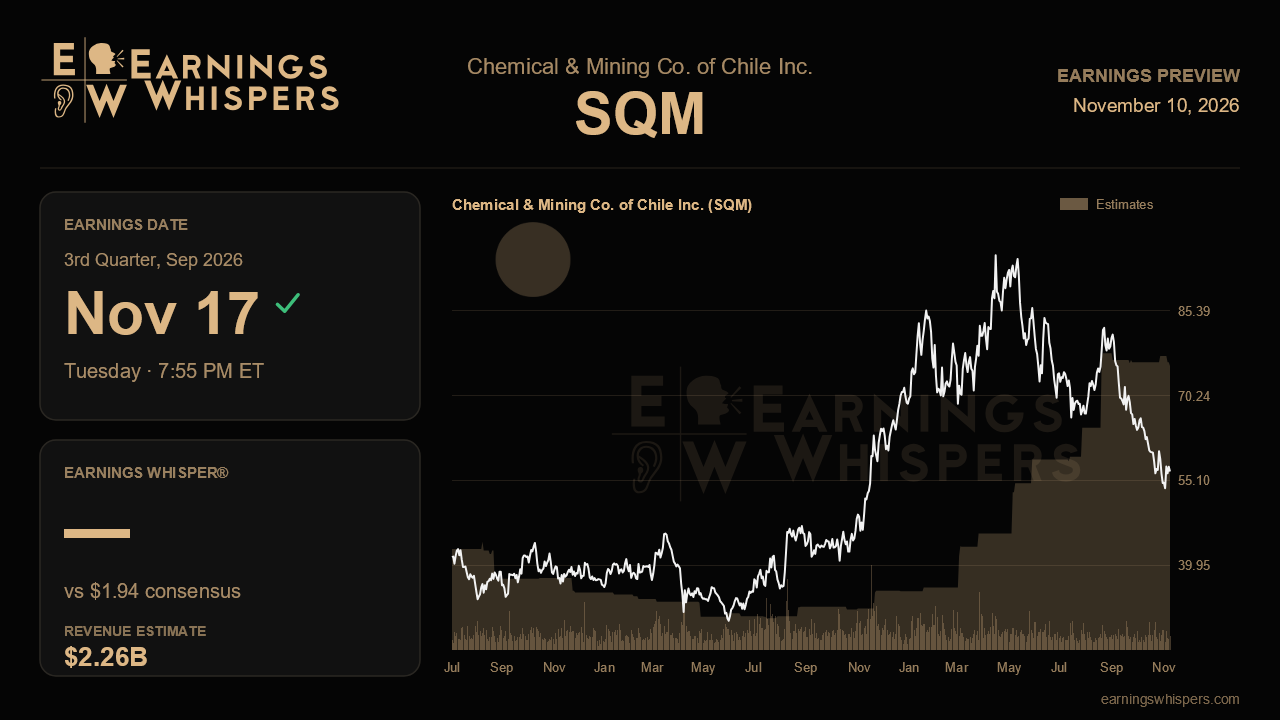
SQM arrives at its third-quarter report with an awkward contradiction. On its last call, management raised nearly everything it could, from global lithium demand to Chilean output to iodine volumes, for the third straight quarter. Since then, the stock has lost almost a quarter of its value while the S&P 500 slipped only modestly. Either the market is looking past a strong operating story toward an oversupplied 2027, or it has overreacted. Tuesday's numbers, due after the close on November 17, should help settle which view is right.
Wall Street expects earnings of $1.94 a share on revenue of about $2.26 billion. Against the year-ago quarter, that is a blowout, with EPS up roughly 213% and sales nearly doubling from $1.17 billion. Sequentially, though, the consensus is calling for a step down from the $2.31 a share and $2.47 billion reported last quarter. That matters because management told analysts it expected third-quarter lithium volumes to roughly match the record of more than 84,000 tons of lithium carbonate equivalent set in the second quarter, with hopes for a stronger fourth quarter. If volumes really are flat, the Street's lower revenue estimate implies analysts are bracing for softer realized pricing, weaker iodine or less favorable mix. A quarter that holds volumes and keeps pricing near second-quarter levels would put the consensus at risk of looking too cautious.
Pricing is the swing factor. Realized lithium prices climbed from around $10 per kilogram in the fourth quarter of 2025 to about $18 in the first quarter of 2026, then rose again in the second. Management also said extra supply of roughly 200,000 tons is coming online this year from Chinese brine and spodumene, African and Argentine ramps and Australian restarts encouraged by higher prices. The third-quarter realized price will be the first clean read on whether that supply response is starting to bite. The other demand-side risk came up on the call. Analysts noted that battery storage shipments have been running at about twice actual deployments, and management conceded there was some inventory pull-forward tied to China's export rebate changes. Any sign that storage-related orders are slowing would undercut the case behind management's demand estimate of more than 2.1 million tons.
Below the headline numbers, several threads deserve attention. The Chilean production target of 280,000 to 290,000 tons for 2026 needs to stay intact, and management's promise that unit costs would come in below 2025 should show up in lithium margins, even with a mining tax that takes roughly 11% to 12% of lithium profit. The International segment, built around Australian spodumene, has been a persistent drag. Its realized price has lagged the Chilean business even as spodumene prices rose, which management attributed to lumpy shipment timing. If that gap narrows this quarter, the timing explanation holds up. If it widens again, skeptics will push harder. On the non-lithium side, iodine was guided to grow about 10% in volume, but management warned the tailwind would ease toward year-end as new Chilean supply arrives, so early price softness would not be a surprise.
Sentiment has edged from mildly bearish before the last report to mildly bullish now, a modest change that does not suggest much enthusiasm. The chart is gloomier. At $56.70, the shares sit far below their 200-day average near $75 and only about 6% above the post-earnings low of $53.67, after trading as high as $84.50. Even the bottom of this range sits well below last quarter's floor in the mid-$60s.
The central question is whether lithium pricing is plateauing or rolling over. If SQM holds volumes near record levels, keeps realized prices close to second-quarter levels and repeats its demand and production targets, the stock's slide will look like an overreaction to 2027 worries. If prices are already slipping and management softens its tone on storage demand or new supply, the market's pessimism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Aug-19 | |
| Aug-19 | |
| Aug-18 | |
| Aug-18 | |
| Jul-30 | |
| Jun-02 | |
| May-27 | |
| May-27 | |
| May-26 | |
| May-26 | |
| Apr-22 | |
| Mar-11 | |
| Mar-09 | |
| Mar-07 |
