Iridex Must Prove Its Back-Half Rebound Is Real As Retina Weakness Tests Guidance
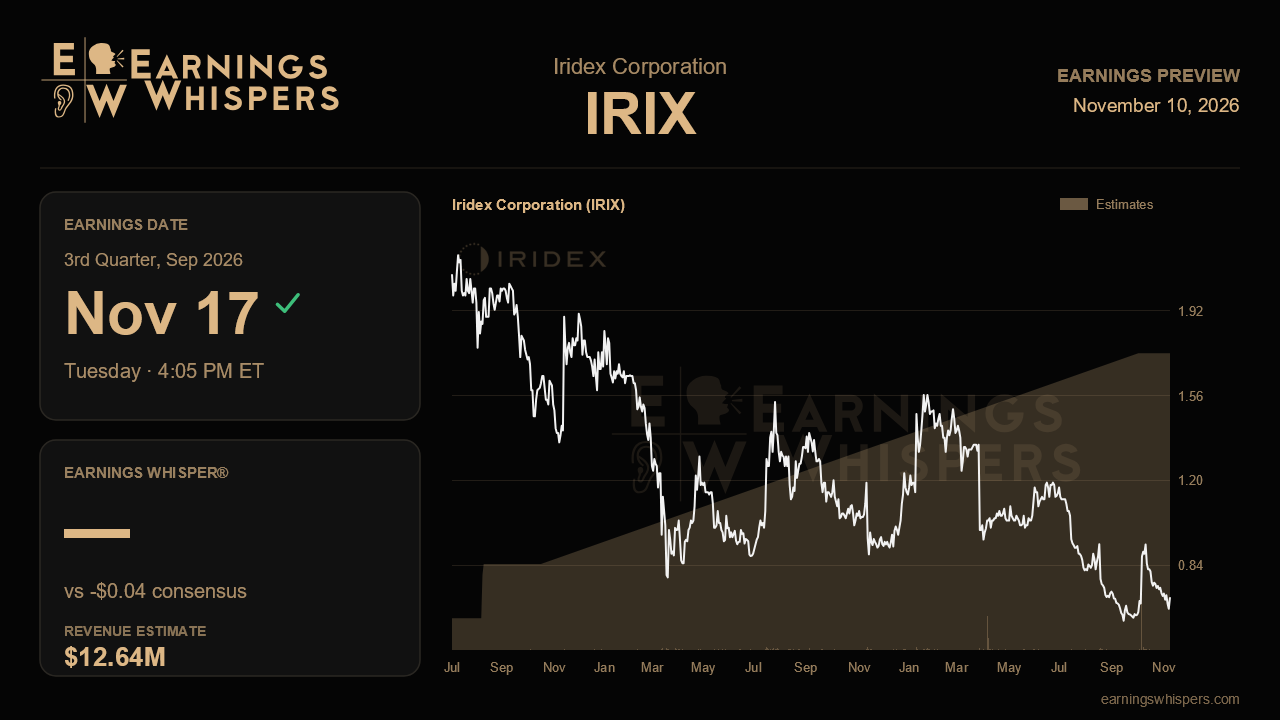
Iridex heads into its third-quarter report with a full-year revenue target that has survived four straight calls but now rests on increasingly heavy lifting. The company's glaucoma probe business is growing at its fastest pace in a year. Retina sales, gross margin and cash flow have all moved the wrong way. The question for this report is whether the second half rebound management keeps promising is starting to show up, or whether a reaffirmed guide is drifting toward wishful thinking.
The Street expects a loss of $0.04 per share on revenue of about $12.6 million. That would be essentially flat with last year's $12.5 million, a gain of only about 1%, while the loss would narrow sharply from $0.09 a year ago and from $0.07 last quarter. The math behind the full-year outlook of $51 million to $53 million is unforgiving. First-half revenue totaled roughly $24.4 million, so the back half needs about $26.6 million to $28.6 million. If the third quarter lands at consensus, the fourth quarter would have to deliver somewhere between $14 million and $16 million, well above anything the company has recently posted. Even a quarter in line with estimates therefore leaves the guide dependent on a big finish.
There is also a timing wrinkle. Last quarter, management warned that customers in Japan and Europe stocked up on probes ahead of regulatory blackout periods tied to the headquarters relocation. That pull-forward flattered second-quarter glaucoma numbers and set up sequential softness now. Consensus calling for flat sequential revenue implicitly assumes something else offsets that hangover, most plausibly a stabilizing retina business. Retina revenue fell to $6.5 million from $8.0 million a year earlier, the second weak quarter in a row, hurt by China destocking and regulatory friction, Middle East disruption and what the company itself described as execution problems. Evidence that retina has bottomed would validate management's call for low-single-digit full-year growth there. Another decline would challenge it directly.
On the glaucoma side, the bar is about durability. Cyclo-G6 probe volume jumped 35% to 17,700 units, but management pegged underlying growth closer to 15% after stripping out pre-orders. Holding something near that pace, along with continued US price increases and early traction from adding the endoprobe to the iPro purchasing group contract, would show the franchise is compounding rather than borrowing from future quarters. System placements matter too. They slid to 18 from 44 two quarters earlier amid European order timing and console competition, and consoles drive future probe pull-through.
The earnings estimate hinges on margin. Gross margin dropped to 34.2% from 40% the prior quarter, and adjusted EBITDA flipped to a loss of $0.4 million. Reaching a $0.04 loss probably requires a meaningful margin recovery alongside the operating expense discipline that cut costs 5% last quarter. Cash is a separate concern: the relocation requires a safety-stock inventory build expected to drain cash through 2026, so last quarter's positive cash flow may not repeat. The payoff, in the form of contract-manufacturing savings and inventory unwinding, is pitched for 2027.
The market has not been patient. Shares have fallen 13.6% since the last report, trailing the S&P 500 by about 11 points, and at $0.71 they sit far below the 200-day average of $1.02 and closer to the post-earnings low of $0.61 than the high. The current range sits entirely below the prior quarter's band of $0.80 to $1.20, a sign that skepticism is building. That lowers the bar for relief, but only if the numbers support the story. Ultimately, this report comes down to whether retina stabilization and margin repair arrive on schedule. If they do, the reaffirmed guide looks credible. If they do not, a fourth-quarter miracle becomes the only path to the target.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-03 | |
| Oct-12 | |
| Oct-05 | |
| Aug-19 | |
| Aug-18 | |
| Aug-18 | |
| Aug-04 | |
| Jul-20 | |
| Jun-09 | |
| May-20 | |
| May-19 | |
| May-19 | |
| May-05 | |
| Apr-07 |
