Prenetics Must Prove July's Record IM8 Momentum Held As Street Trails Raised Guidance
Prenetics heads into its third-quarter report with an unusual setup: management has raised its outlook repeatedly and set an aggressive 2027 target, yet the stock has slipped since the last report and Wall Street still won't fully commit to the company's numbers. The question for this report is whether the IM8 supplement business kept scaling efficiently after a record July. The alternative is that the summer surge looks more like a peak than a new baseline.
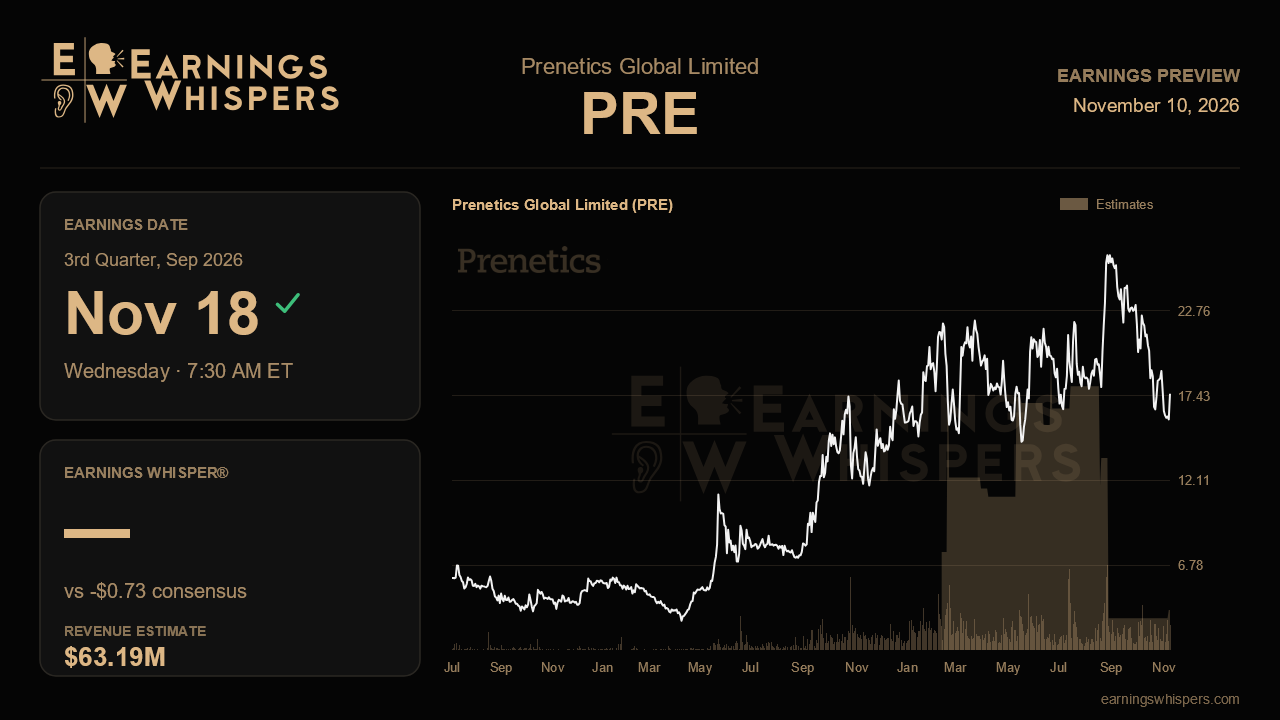
Consensus calls for revenue of about $63.2 million, up roughly 168% from $23.6 million a year ago and about 36% above the $46.5 million reported last quarter. The loss is expected to widen to $0.73 per share from $0.41 a year earlier. That deeper loss is expected rather than alarming. Last quarter's adjusted EBITDA loss swelled to around $19 million as marketing spend doubled, and management framed that as deliberate investment in customer acquisition. The more telling comparison is guidance. Prenetics lifted its 2026 revenue outlook to $220 million to $230 million from $190 million to $210 million, yet the full-year consensus of $211.8 million sits below even the new low end. The gap is wider for 2027, where the company is calling for $400 million or more against a Street estimate near $359 million. Analysts are effectively discounting management's word, which lowers the bar for this quarter but raises the stakes for any guidance commentary.
The revenue estimate itself looks reachable on paper. July alone produced a record $20.9 million, so the quarterly consensus implies August and September merely held that pace. The more important test is how that revenue was bought. Management highlighted a July customer cohort of more than 47,000 acquired at roughly $239 each, about a fifth cheaper than the second-quarter average near $305, while gross profit returned per dollar of acquisition cost improved to $1.52. Scaling volume while acquisition costs fall is rare in consumer subscriptions. Management notably declined to build that efficiency into guidance. If customer acquisition costs stayed near July levels and subscribers kept climbing from the 140,000 reported last quarter, the bull case gets considerably stronger. If costs drifted back toward $300 or retention softened as young cohorts aged, the profitability story weakens quickly, because the model depends on those cohorts paying back.
Cash flow is the other milestone. Management said the third quarter should be the first with positive consolidated adjusted free cash flow, but that measure counts proceeds from the $1 billion General Catalyst facility, which funds 70% of acquisition marketing. Investors should look past the headline figure to how much of the improvement came from operations versus financing. Gross margin, which has crept from 60% to about 65% over four quarters, should also hold steady if pricing and mix remain healthy. Early signs on the fourth-quarter Hydration launch would help support the $400 million 2027 ambition, which leans heavily on new products in crowded categories.
The market has grown more cautious. Shares are down 10.5% since the last report, trailing the S&P 500 by more than 8 percentage points. At $17.55, the stock sits below its 200-day moving average of $19.58 and in the lower part of a wide $14.69 to $27.24 post-earnings range. Bullish sentiment remains high at 85.6% but has eased slightly from 88.6% before the prior report. Strong reported growth paired with a lagging share price suggests skepticism about quality rather than quantity.
Ultimately, this report will be judged less on whether revenue clears $63 million than on whether Prenetics kept growing without paying more for each customer. If acquisition costs and retention held while revenue tracked toward the raised range, the Street's discount to guidance looks too conservative. If efficiency faded, the deepening losses will look less like investment and more like the cost of buying growth.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-05 | |
| Nov-05 | |
| Nov-03 | |
| Oct-12 | |
| Aug-26 | |
| Aug-20 | |
| Aug-20 | |
| Aug-18 | |
| Aug-17 | |
| Aug-17 | |
| Aug-07 | |
| Jul-14 | |
| Jun-10 | |
| Jun-04 |
