TELA Bio Beats On Cost Cuts, But Shrinking Revenue And A Thinning Cash Cushion Define The Quarter
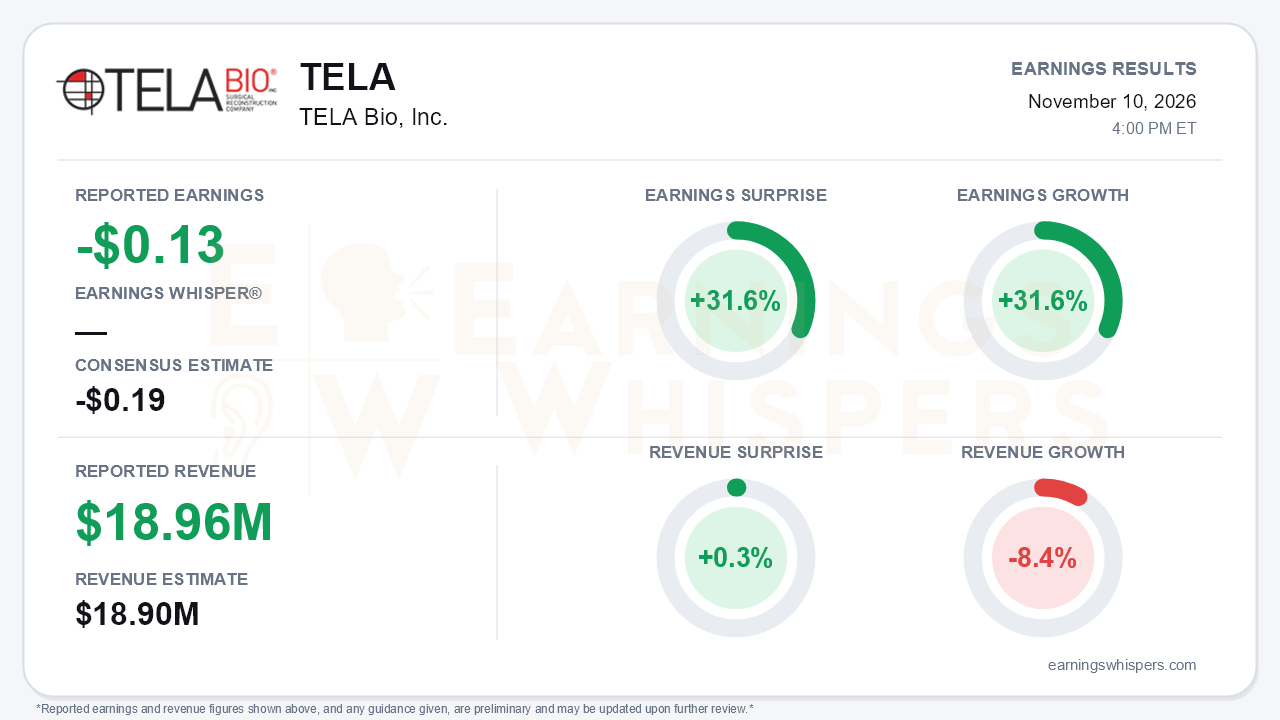
TELA Bio cleared a low bar in the third quarter. The adjusted loss was $0.13 per share against a consensus estimate of a $0.19 loss, a 31.6% beat and a 31.6% year-over-year improvement. Revenue of $18.96 million edged past the $18.9 million consensus by 0.3% but fell 8.4% from a year ago. That is the central tension: under a new CEO, the company is cutting its way to a smaller loss while the top line keeps shrinking. Revenue growth has moved from +3% in the first quarter to -4% in the second and now about -8%. That is a clear deceleration, not the inflection management promised earlier in the year.
The quality of the earnings beat deserves scrutiny. In absolute terms, the adjusted net loss improved to $7.3 million from $8.4 million, but part of the per-share gain reflects a weighted share count of 57.7 million, up from 45.4 million. On a GAAP basis, the net loss actually widened to $9.3 million from $8.6 million. Two items drove that:
- $2.0 million of severance and legal costs tied to the restructuring;
- interest expense that nearly doubled to $2.1 million.
GAAP gross margin slipped to 64.9% from 67.5% because of a $1.0 million write-off of expired product. Excluding non-cash charges, adjusted gross margin was 71%, roughly in line with last year's 70%.
The real improvement came from expense control. Operating expenses excluding other items fell about 17.5% year over year to $17.6 million, down from $23.2 million in the second quarter. The $17 million annualized cost plan, which began September 1, includes roughly a 20% headcount reduction. As a result:
- operating loss narrowed to $7.3 million, from $9.3 million in Q2 and $10.5 million in Q1;
- adjusted EBITDA loss shrank to $3.4 million from $7.7 million sequentially.
That is genuine progress on burn. It came from cuts, however, not from growth.
The call revealed a demand picture that remains soft:
- OviTex PRS revenue fell 20% year over year and 6% sequentially. That directly contradicts the second-half recovery management had anticipated on the prior call.
- European growth, while still positive at 18%, has decelerated from 41% in Q1 and 26% in Q2. International revenue slipped sequentially to $3.6 million.
- US hernia revenue and units rose sequentially, but hernia revenue was down slightly year over year as mix shifted toward smaller units.
- LiquiFix posted a record quarter, with its customer base up 60% year to date.
Management blamed weaker elective procedure volumes and competitor bundling. CEO Heather Getz now frames the recovery as a multi-quarter effort, the second go-to-market realignment in a year. Full-year guidance, which once pointed to 15%+ growth, was withdrawn in Q2 and was not reinstated.
The balance sheet is where bears have the most ammunition:
- Cash fell to $22.7 million, from $30.4 million in Q2, $39.5 million in Q1 and $50.8 million at year-end.
- The $56.3 million Perceptive loan is now classified as a current liability.
- Stockholders' equity has swung to a $24.6 million deficit.
- Perceptive suspended minimum revenue covenant testing for the third and fourth quarters, which relieves near-term pressure but underscores the strain.
Management says the cost plan extends the runway into 2028. That claim depends on revenue stabilizing.
There are some forward catalysts:
- 510(k) clearance of the Liora monofilament scaffold (referred to as "Leora" on the call), the company's first in-house implant, with a commercial plan slated for early 2027;
- pursuit of a national contracting agreement;
- four new peer-reviewed publications supporting OviTex and OviTex PRS;
- restored Nasdaq bid-price compliance, with no reverse split planned for now.
Investor sentiment entered the report deeply negative but improved meaningfully, rising from -1.0 to roughly -0.59. Price action tells a more sobering story. Shares spiked to a 52-week high of $1.50 on September 23. By the pre-report snapshot, they had retreated about 42% to $0.86, slightly below the $0.90 open after the prior report. The stock sits just 1.4% above its 200-day moving average of $0.85. Momentum and AVWAP trend readings remain negative, consistent with a market that has given back most of its enthusiasm for the restructuring story.
The bottom line is that TELA delivered the cost discipline it promised, and the narrower EBITDA loss is real. The headline beat, however, masks an accelerating revenue decline, a PRS franchise that missed its own recovery target, and a balance sheet leaning on lender forbearance. Until sales stop shrinking and guidance returns, the improving loss line reads more as a runway extension than a turnaround.
Read our earnings preview for TELA Bio, Inc.: https://www.earningswhispers.com/article/TELA/22770
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-06 | |
| Nov-03 | |
| Oct-27 | |
| Oct-05 | |
| Aug-31 | |
| Aug-11 | |
| Aug-10 | |
| Aug-07 | |
| Aug-05 | |
| Aug-04 | |
| Jul-29 | |
| Jul-20 | |
| May-13 |
