RideNow's Turnaround Stalls As Clear Price Rollout And Softer Consumer Cut Adjusted EBITDA 57%; Refinancing Buys Time
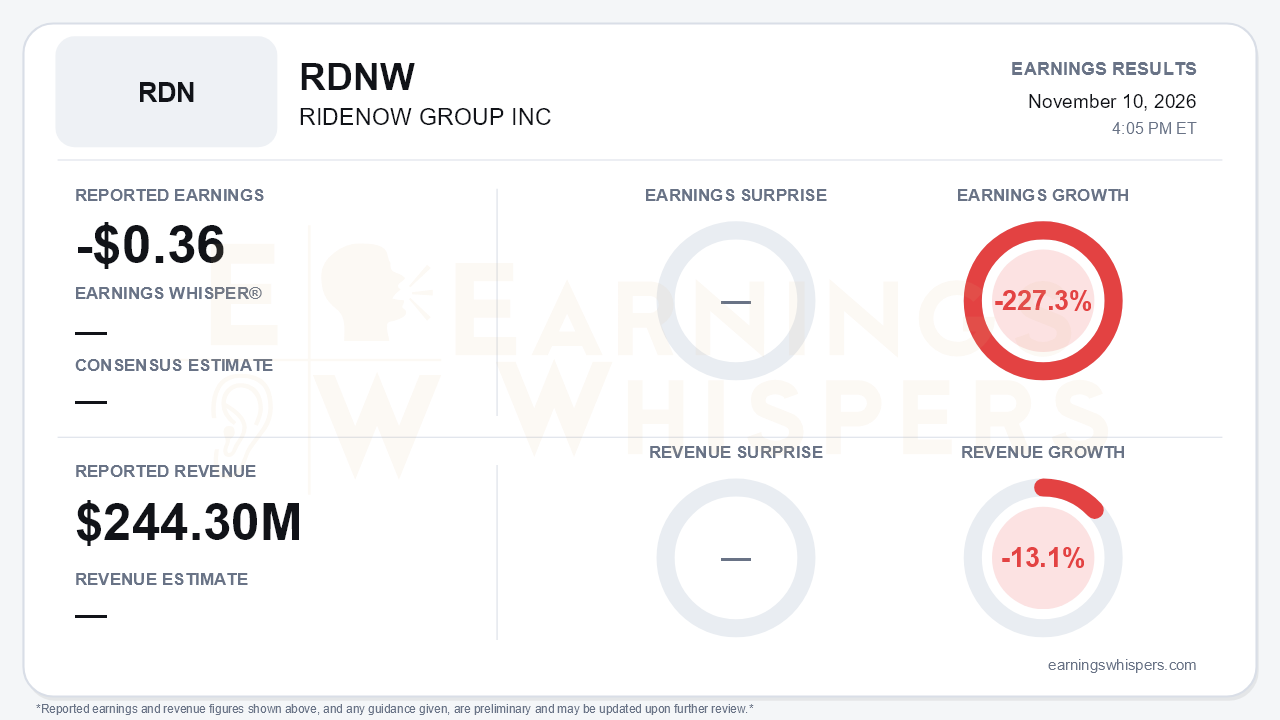
RideNow Group's third quarter broke the turnaround narrative it had been building all year. The company lost $0.36 per share, compared with an $0.11 loss a year ago, an earnings decline of 227.3%. Revenue fell 13.1% to $244.3 million. No consensus estimate was available, so the debate is not about a beat or a miss. It is about direction. After four consecutive quarters of same-store growth, same-store powersports revenue fell 7.9% and same-store retail units dropped 10.9%. Adjusted EBITDA fell to $5.3 million from $12.3 million. That is a sharp reversal from Q2, when adjusted EBITDA rose 19.2% to $20.5 million, and Q1, when it grew 32.9%.
The GAAP loss overstates the operating damage somewhat, but not by much. Roughly $5.8 million of refinancing costs, mostly a $5.7 million loss on debt extinguishment, sit below the operating line. Even excluding those costs, the core picture weakened materially:
- **Operating income** fell 55.3% to $4.2 million.
- **SG&A** consumed 91.0% of gross profit, or 88.1% on an adjusted basis. That compares with 74.1% in Q2. A $4.8 million reduction in SG&A could not keep pace with the $10.5 million drop in gross profit.
- **Gross profit per unit** rose 3.7%, but this flatters the quarter. It was driven by fewer units against a relatively steady F&I and parts base, not by better vehicle pricing.
- **Vehicle margins** told the real story. New-unit gross margin fell to 13.1% from 14.8% in Q2. Pre-owned margin dropped to 15.4% from 18.0%. Pre-owned retail gross profit fell 33.7% year over year.
The central tension is how much of this damage was self-inflicted, and therefore potentially temporary. Management attributed the decline primarily to its August company-wide rollout of "RideNow Clear Price," an all-in transparent pricing model built to comply with FTC guidance on pricing and fees. On the call, management said Clear Price accounted for about half of the unit decline and about $4 million of the roughly $7 million EBITDA decline. That leaves a meaningful residual that cannot be blamed on pricing policy. Management's tone also changed noticeably. In Q1 and Q2 it spoke of strong momentum and no consumer deterioration. This quarter it cited rising rates, high fuel prices and inflation weighing on discretionary spending. The Q2 expectation of strong adjusted EBITDA and free cash flow through the rest of 2026 was effectively not met.
The balance sheet and working capital deserve scrutiny:
- **Inventory** climbed to $329.2 million from $257.4 million at year-end. Floor plan notes rose to $291.9 million.
- **New inventory** stood at just over five months of supply, against a low-four-month target. Model-year 2026 units are no longer MAP-protected, which points to continued clearance discounting.
- **Operating cash flow** was a $41.7 million outflow for the nine months.
- **Adjusted free cash flow** of $14.2 million looks healthier only because it adds back $58.4 million of non-trade floor plan borrowings. It was also down from $20.8 million at the six-month mark, implying cash consumption in Q3.
- **Liquidity** declined to $149.4 million from $158.2 million.
- **Non-vehicle net debt** reached $203.7 million. That is up from $189.3 million at year-end and from the $174.4 million figure referenced on the call.
- **Stockholders' deficit** widened to $22.1 million.
There are real positives:
- **Refinancing.** The long-promised deal replaced the Oaktree term loan with a $220 million Centerbridge facility maturing in 2031. It removes restrictive milestones without equity dilution, and a Wells Fargo-led $50 million ABL facility is in advanced discussions. The cost is steep, however, at SOFR (with a 3% floor) plus 8.375%.
- **Cost actions** accelerated, with $4.6 million of annualized cuts in Q3 and a new target of $10 million in incremental run-rate savings exiting 2027.
- **M&A** resumed with a Tallahassee tuck-in that adds Can-Am and Sea-Doo.
- **Near-term outlook.** Management says September and October unit trends improved to low-to-mid single-digit declines. It expects Q4 adjusted EBITDA to exceed Q3, against normal seasonality. Investors should note how low that bar is: $5.3 million. Elevated inventory and clearance pricing could also pressure Q4 margins even if volumes recover.
- **Longer-term option.** If FTC enforcement forces competitors to adopt transparent pricing, RideNow's early compliance could become a share-gain advantage. For now, management concedes most competitors outside Phoenix remain non-compliant.
Market context offers limited help. Shares opened at $6.26 the morning after the August report, just below a 200-day moving average now at $6.33. The stock therefore entered this period without established upward momentum. No current price or sentiment reading was available to gauge how investors have repositioned since.
The bottom line is that RideNow traded a quarter of earnings for a regulatory bet and a cleaner capital structure. The refinancing removes the most acute overhang. However, the reversal in same-store trends, margin compression, swelling inventory and higher-cost debt give bears legitimate ammunition. The Q4 EBITDA improvement management promised, and evidence that Clear Price volumes are genuinely recovering, now carry the burden of proof.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Sep-28 | |
| Aug-12 | |
| Aug-11 | |
| Aug-11 | |
| Aug-04 | |
| Jun-09 | |
| Jun-02 | |
| Jun-01 | |
| May-18 | |
| May-15 | |
| May-14 | |
| May-06 |
