MaxCyte Beats Big And Raises Again, But The Akron Bio Deal Changes The Story
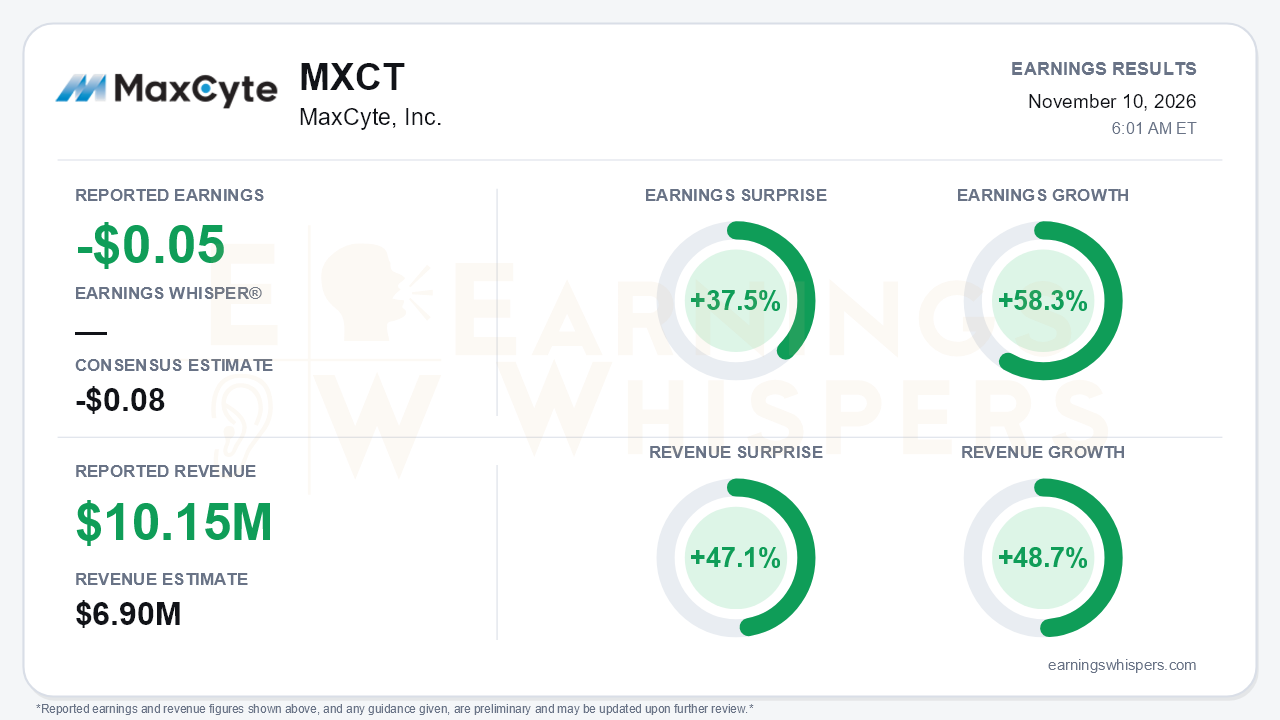
MaxCyte delivered its cleanest quarter in some time and then moved the conversation elsewhere. The company reported a third-quarter loss of $0.05 per share on revenue of $10.15 million. The consensus estimate called for a loss of $0.08, so EPS beat by 37.5%, and revenue topped the $6.9 million consensus by 47.1%. Revenue grew 48.7% year over year, and earnings improved 58.3% as the net loss narrowed to $4.8 million from $12.4 million. Management raised full-year revenue guidance for the second time in about a month. It also announced the proposed acquisition of Akron Bio, a supplier of GMP-grade reagents. That deal nearly doubles revenue but drains most of the balance sheet. The beat is real. The central tension is that investors are now being asked to underwrite a very different company.
The quality of the beat deserves scrutiny, though most of it holds up. Core revenue rose 27% to $8.2 million, a sharp reversal from a roughly 25% decline in the first quarter and another year-over-year decline in the second. The mix is more mixed:
- **Instruments:** Revenue doubled to $2.8 million. Management acknowledged that part of this came from partner purchases originally expected in the fourth quarter.
- **Processing assemblies and consumables:** These rose 20% year over year and 32% sequentially to $3.1 million after two flat quarters at $2.3 million. This recurring line is the better tell on underlying demand.
- **SPL revenue:** Revenue from the Strategic Platform License program jumped to $2.0 million from $0.4 million. Royalties rose to about $1 million, tracking Casgevy sales of roughly $99 million in the quarter.
GAAP gross margin of 83% was flattered by that high-margin SPL revenue. On an adjusted basis, excluding SPL revenue and inventory reserves, margin slipped to 80% from 81%. The narrower loss owes as much to cost discipline as to growth. Operating expenses fell 25% to $14.5 million, research and development spending was nearly halved, and last year's quarter carried a $3.1 million restructuring charge.
The guidance math is where the timing shift shows up. Full-year revenue is now expected to be at least $34.5 million, versus $30 million to $32 million as recently as the second quarter. Core revenue guidance rose to about $28 million from $25 million to $27 million, and SPL guidance increased to at least $6.5 million. Gross margin guidance moved to the high 70s from the mid-70s. Against roughly $20.9 million of core revenue through nine months, the core guide implies a fourth quarter near $7 million. That would be a noticeable sequential step down from $8.2 million and consistent with the instrument pull-forward. Management's framing of roughly 15% second-half core growth, versus low-single-digit total growth guided in the second quarter, is still a meaningful upgrade. Tone shifted from defensive earlier in the year to openly confident.
Akron is the real catalyst and the real risk.
**What MaxCyte gets:**
- About $28 million of 2026 revenue, $7 million to $8 million of EBITDA and positive cash flow.
- Pro forma revenue above $60 million and recurring revenue rising to 74% of the mix from 57%.
- Exposure to its largest customer falling to about 14% from 27%.
- Combined 2027 cash burn guided below $10 million, versus about $17 million for MaxCyte alone in 2026.
**What it costs:**
- Total consideration is $151.8 million, including $105 million in cash, about $26.8 million in stock and $20 million in guaranteed deferred payments.
- Year-end cash falls to an estimated $40 million to $45 million from $132.7 million.
- MaxCyte takes on about $22 million of drawn debt from a previously debt-free position.
- Interest income will shrink, and Akron's mid-60s gross margins dilute MaxCyte's roughly 80% profile.
- Customer overlap is only about 10%, so the cross-selling thesis is unproven.
- Shareholders who just watched $5.5 million in buybacks will now absorb new share issuance.
After management described its M&A posture as "very, very selective" only a quarter ago, bears have legitimate ammunition on the strategic pivot. The partner pipeline offers offsetting upside. A $1 million pivotal-dosing milestone arrived early, management cited up to three approved partner products within 24 months, and the Genentech partnership is already generating instrument orders.
The market setup is more complicated than the surprise implies. Earnings Whispers investor sentiment entered the report negative and weakened modestly, from -0.27 to -0.36. The stock has been volatile: it fell to $0.94 on October 13, then spiked to $1.76 by October 29. At $1.30 just before the report, it had given back much of that spike while remaining 11.1% above the open following the August report and nearly 22% above its 200-day moving average. Price and momentum trend readings are positive, while AVWAP remains negative. That pattern fits a stock that has re-rated off its lows without convincing holders.
The bottom line is that MaxCyte's standalone business has clearly turned. Core revenue swung from steep declines to 27% growth, consumables reaccelerated and guidance moved higher twice. Some of that strength was borrowed from the fourth quarter, and the margin gain leans on SPL revenue. The Akron deal trades a cash-rich, single-platform story for a larger, cash-generating but more leveraged and lower-margin one. The quarter's results earned credibility; the acquisition now has to prove it was worth spending most of that cushion.
Read our earnings preview for MaxCyte, Inc.: https://www.earningswhispers.com/article/MXCT/22754
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-28 | |
| Oct-14 | |
| Sep-23 | |
| Sep-11 | |
| Aug-19 | |
| Aug-13 | |
| Aug-12 | |
| Jul-21 | |
| Jul-15 | |
| May-13 | |
| May-12 |
