Suja Life Beats Third-Quarter Estimates, But A Third Straight Sales Guidance Cut And The First EBITDA Cut Reveal A Deepening Grocery Slowdown
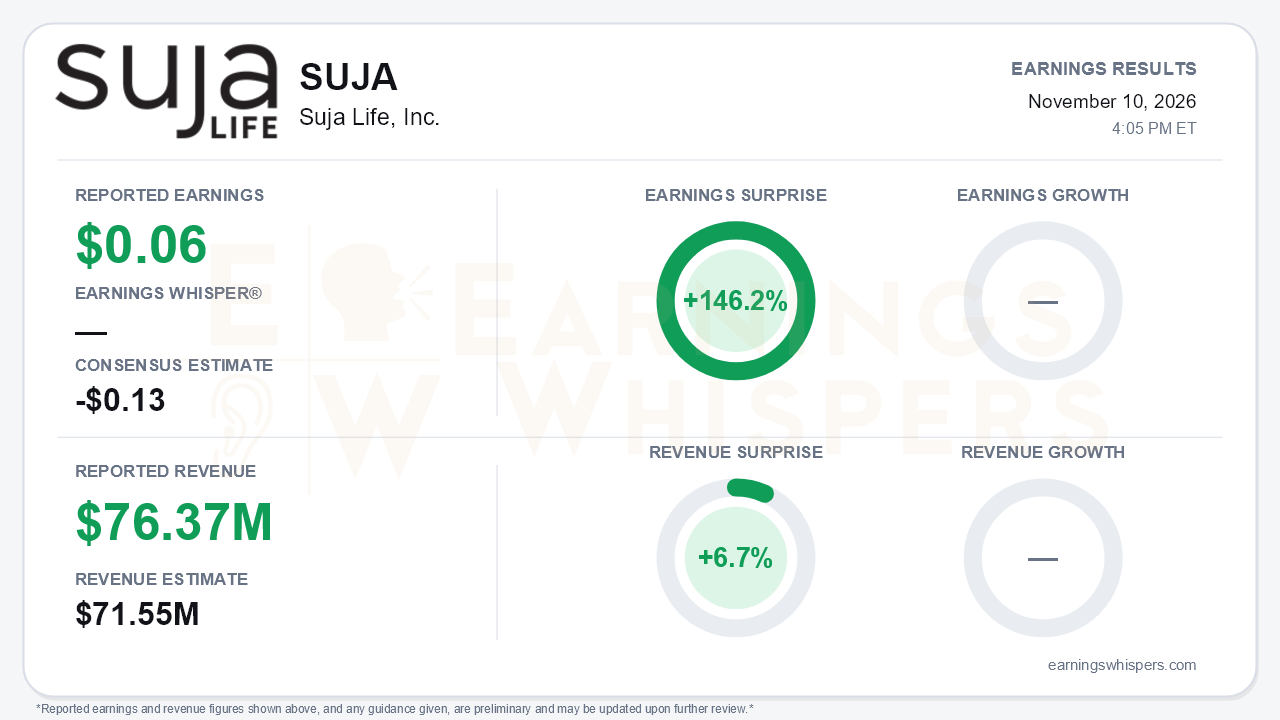
Suja Life delivered a third-quarter beat that looks considerably better on paper than it does underneath. The company reported earnings of $0.06 per share against a consensus estimate calling for a $0.13 loss, a 146.2% surprise. Revenue of $76.37 million topped the $71.55 million consensus by 6.7% and rose 3.3% from a year earlier. The investment story, however, turned on what came alongside the beat. Management cut its full-year sales outlook for the third consecutive quarter, lowered adjusted EBITDA guidance for the first time, and warned that 2027 will start slowly and fall short of its 13% long-term growth algorithm. That is the central tension: a quarter that cleared the bar, attached to a forward picture that keeps getting smaller.
The quality of the beat deserves scrutiny. Roughly $2.0 million of shipments originally expected in the fourth quarter landed in the third, which accounts for a meaningful share of the revenue upside. The $0.06 figure is also a normalized result. On a GAAP basis, Suja posted a net loss of $8.3 million, or $0.22 per Class A share. That loss was a clear improvement from $14.6 million a year ago, but it still included $6.7 million of items the company calls one-time, among them a $1.8 million debt-extinguishment loss, $1.5 million of restructuring costs and a $1.0 million labeling-related regulatory write-off. Adjusted EBITDA jumped to $10.5 million from $1.0 million, but the improvement came mostly from SG&A leverage of 820 basis points as Suja lapped heavy Slice launch spending. It did not come from the core economics. Gross margin fell to 43.9% from 46.3%, and adjusted EBITDA margin of 13.8% trailed the roughly 15.2% the Street expected.
The conference call showed the slowdown is broad. Sales growth decelerated from 22.5% in the first quarter to 11.6% in the second and 3.3% in the third. Gross margin followed the same path, sliding from 50.5% to 46.8% to 43.9% on heavier trade spending, weaker fixed-cost absorption, and oil-linked freight and packaging inflation. Grocery is the problem. Category promotional share has risen more than six points, and disruptor shot brands are selling 50% to 60% of volume on promotion. Suja's per-point velocities are falling even as distribution grows about 10%. Green Juice, single-serve shots and Vive softened. Slice growth collapsed to 3% from 61% in the prior quarter, and Emerging Brands sales grew just 3% to $2.7 million as new distribution built slowly. Management's tone shifted to match, moving from August's talk of "going on offense" and targeting the top of the range to a blunter "we have work to do."
Bulls still have real material. Suja was the only top-five manufacturer to gain share in natural healthy beverages, adding about 30 basis points to just over 9%. Household penetration climbed to 11.2% from 9.6%, and spend per buyer rose 9%. Club grew around 20%, convenience more than 40%, and Refreshers more than 40%, while new distribution has been secured for the 2027 selling season. The balance sheet has also been transformed. Total debt fell to $163.0 million from $303.9 million after the IPO, and the August refinancing cut the effective rate to 5.7% from 9.7%. Quarterly interest expense dropped to $3.3 million from $7.6 million, and the full-year interest guide eased to about $18 million. Cash has thinned to $15.5 million, though, with nine-month operating cash flow slightly negative and capital spending up to $18.6 million as a sixth HPP machine comes online.
The forward bar now hinges on execution. Revised guidance of $351 million to $354 million in sales and $68 million to $70 million in adjusted EBITDA implies fourth-quarter revenue of $83.7 million to $86.7 million. The call characterized that as roughly a mid-single-digit decline, a sharp reversal from the mid-teens rebound management defended in August. Meanwhile, implied fourth-quarter EBITDA of $17.8 million to $19.8 million still requires a substantial margin step-up. The new unified commercial organization and social-first marketing model do not arrive until early 2027.
Investors were not positioned for good news. Earnings Whispers sentiment stood at a deeply negative -0.75 heading into the report. Shares at $10.42 sat 1.6% below the 200-day moving average of $10.59, essentially hugging that level rather than trading decisively above or below it. The broader trend readings skew negative. A lot of skepticism was therefore already embedded, but the guidance cut and the 2027 warning give bears fresh ammunition rather than reasons to cover.
The bottom line is that Suja's headline beat was flattered by shipment timing, normalized accounting and easy SG&A comparisons, while the underlying trends in grocery velocity, gross margin and Slice momentum all weakened. The refinancing and share gains keep a credible long-term story alive. Until promotional pressure stabilizes and guidance stops moving lower, though, the quarter reads as a deceleration story dressed up as a beat.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 7 hours | |
| Nov-11 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Oct-20 | |
| Oct-19 | |
| Sep-21 | |
| Aug-20 | |
| Aug-19 | |
| Aug-17 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Aug-04 |
