Orion180 Tops Estimates In First Public Quarter, But The Growth Engine Is Shifting Toward Risk-Bearing Profits
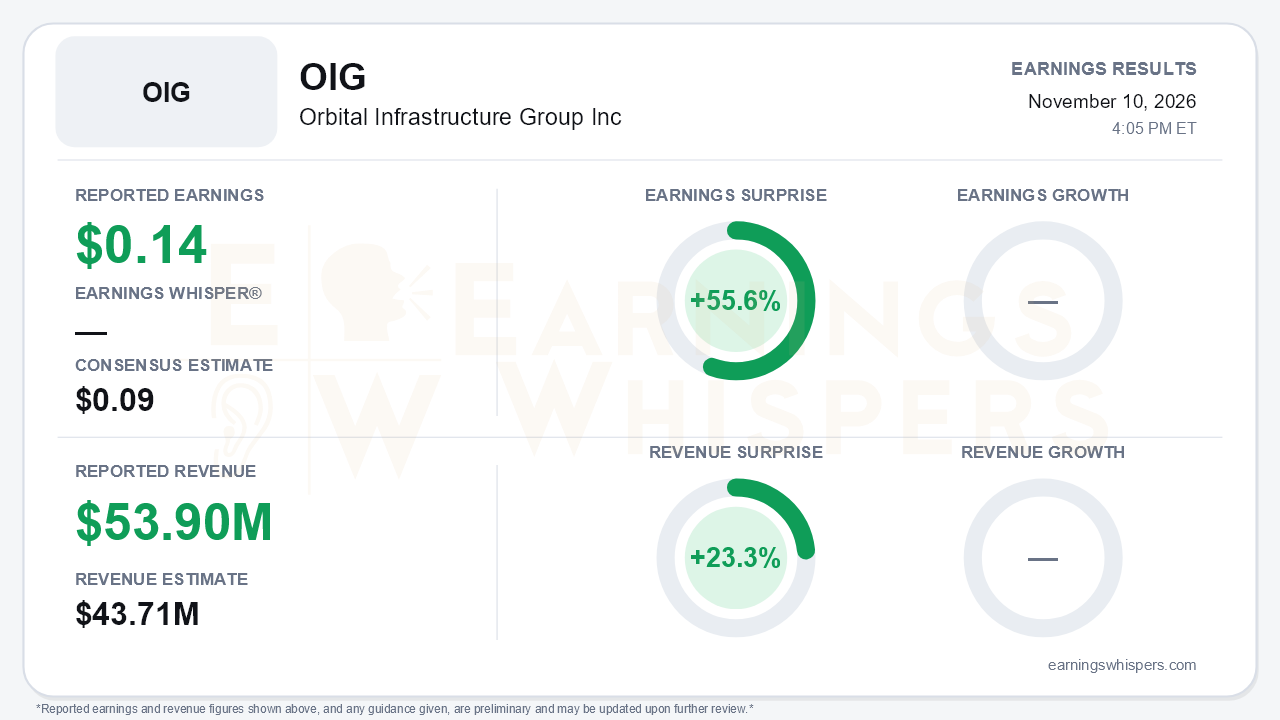
Orion180 Insurance Group used its first quarter as a public company to post a clear beat. Earnings were $0.14 per share against a $0.09 consensus, a 55.6% surprise, and revenue of $53.9 million topped the $43.71 million estimate by 23.3%. Note that the Earnings Whispers record still lists the OIG ticker under its former holder, Orbital Infrastructure Group, which is a different business. Orion180 grew managed premiums written 60% to $204 million, lifted premiums in-force 72% to $678 million, and raised GAAP net income 32% to $11.5 million. The volume story is unambiguous. The more important question is where the profit came from, and that is the central tension: the fee-based services business that anchors the 'high-margin, tech-enabled' pitch is growing earnings far more slowly than revenue, while the more volatile underwriting segment is doing the heavy lifting.
The quality of the beat deserves scrutiny. Services commission and fee revenue rose 64% to $75.1 million, but Services adjusted EBITDA grew only 16% to $18.6 million, compressing the segment's margin from roughly 35% to about 25%. Salaries and software costs nearly doubled to $15.3 million and other services G&A more than doubled to $17.4 million. Meanwhile, Underwriting adjusted EBITDA jumped to $11.5 million from $2.7 million as the combined ratio improved 27 points to 68.8%. Most of that gain came from a 22-point drop in the expense ratio. The gross loss ratio actually rose to 32.8% from 27.3%, so the improvement in the net loss ratio to 42.8% reflects reinsurance structure more than cleaner underlying loss experience. Management described hurricane impact as immaterial, which flatters a quarter that is seasonally exposed. At the consolidated level, adjusted EBITDA rose 65% to $25.1 million and margin widened to 46.6%. GAAP net margin, however, slipped to 21.3% from 25.4%, weighed by higher interest expense and $2.8 million of IPO-related costs and debt-extinguishment charges.
Growth is also moderating as comparisons stiffen. For the nine months, net income swung from $5.6 million to $25.0 million, which means the first half went from a loss to a profit. Third-quarter growth of 32% is a far more normal pace. Commission and fee revenue rose 76.8% year-to-date but 64.4% in the quarter, and policy fee income slowed from 82% to 70%. Total revenue growth held steady at about 58%. Retention slipped to 87.6% from 89.6%, and management acknowledged some pricing pressure as admitted carriers return to homeowners lines. That is a credible early warning in a business built on renewing a fast-growing book.
The call preserved a confident growth narrative with tangible levers. Management pointed to:
- the October launch of Flex Lux, covering dwellings up to $5 million in Florida and Texas;
- the DP Landlord program, now live in nine states;
- early contribution from Colorado and continued ramps in Texas, Florida and California;
- a quota-share reinsurance panel expanded to 11 members, with per-event retention for fronting carriers capped at $1 million.
The IPO raised about $224 million net, and the company ended the quarter with $166 million of cash against $56 million of debt. Investors should also note what the cash-flow statement shows. The company paid $206.5 million in dividends year-to-date and repurchased its preferred stock, which left shareholders' equity at just $52.3 million despite the offering. No formal financial guidance was provided, so the forward case rests on management's qualitative confidence rather than numbers it can be held to.
The market context is difficult to read cleanly. Investor sentiment stood at a mildly negative -0.22 heading into the report, with no prior reading for comparison. The supplied price history, including a reference open of $2.11 after a May 2023 report, a 338% gain, and a stock trading more than 200% above a $2.87 200-day average, appears to splice legacy Orbital Infrastructure data with Orion180's post-IPO trading. Those technical comparisons should not be treated as a meaningful measure of how the market has priced this insurer. The honest framing is that Orion180 has only weeks of trading history and no established technical baseline.
The bottom line is that Orion180 delivered a strong debut beat on both earnings and revenue, backed by premium growth most insurers would envy and a sharply improved combined ratio. Beneath the headline, the profit mix is tilting toward underwriting results helped by a benign storm quarter. Services margins are compressing, retention is softening against returning competition, and management offered no guidance. Bulls have a scalable growth platform with new products and fresh capital. Skeptics have legitimate ammunition in earnings quality and a thin equity base, and the next quarter's loss and retention trends will matter more than this beat.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Oct-27 | |
| Oct-19 | |
| Oct-13 | |
| Sep-30 |
