Marchex Delivers Its Profitability Step-Up But Falls Short Of The Whisper As Growth Trails Archenia-Era Promises
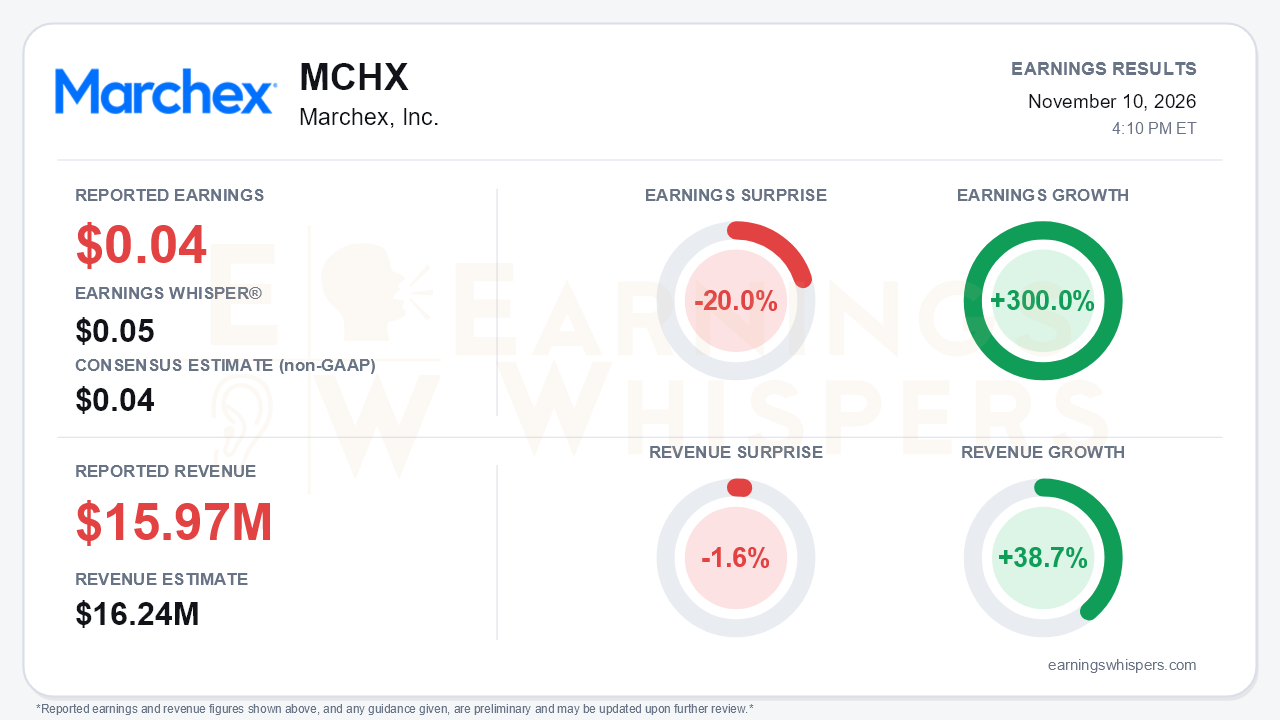
Marchex's third quarter delivered the profitability inflection it had promised, but not the growth. Adjusted earnings of $0.04 per share matched the $0.04 consensus. They fell short of the $0.05 Earnings Whisper number, a 20.0% miss against the whisper. Revenue of $15.97 million missed the $16.24 million consensus by 1.6% and landed at the bottom of management's own $16.0 to $16.5 million range. On the Earnings Whispers normalized basis, earnings grew 300.0% year over year and revenue grew 38.7%. The release, however, presents prior-year results 'as adjusted' for the Archenia combination. On that basis, revenue rose only about 5%, from $15.2 million to $16.0 million. That gap is the central tension. The margin story is real, but the combined top line is expanding far more slowly than the 15% to 20% combined run-rate growth management framed on its fourth-quarter 2025 and first-quarter 2026 calls.
The quality of the earnings improvement deserves a closer look, because it came almost entirely from cost cuts rather than revenue leverage. GAAP net income swung to $1.3 million, or $0.03 per share, from a $1.3 million loss a year ago. Adjusted EBITDA jumped to $2.4 million from $0.5 million, or $2.6 million (16% margin) before reorganization and acquisition costs. Management called this a run rate above $10 million annualized and its best in over a decade. Operating expenses beyond cost of revenue fell to $6.7 million from $9.3 million:
- Sales and marketing dropped about $700,000.
- Product development dropped about $700,000.
- G&A dropped about $1.2 million.
- Stock compensation and depreciation also declined.
Meanwhile, gross margin slipped to 51% from 54% on revenue mix and paid-pilot costs. Adjusted EBITDA of $2.4 million sat within the $2.3 to $2.5 million guide but slightly below the 'combined ~$2.5M or more' framing from the first-quarter call.
On the call, management leaned on commercial proof points rather than numbers:
- **AI Voice Agent conversion.** The advertising/media customer cited as a pilot last quarter converted to a commercial AI Voice Agent deployment. It is expected to add more than $200,000 in annualized revenue in 2027 on a roughly $400,000 base.
- **Automotive OEM approval.** A major automotive OEM approved Engage for Service for its dealer portal, making the product eligible for co-op funding after a 75-dealership pilot. That is potentially the more scalable development.
- **Pipeline.** Management said several seven-figure pipeline deals have progressed since the second quarter, with specific large deals targeted for year-end. Paid AI Voice Agent pilots are under discussion with several large enterprises.
- **Leadership.** Former Archenia CEO Travis Fairchild was named President to drive commercialization.
Demand signals improved, but bears have legitimate ammunition in what went missing. The top-100 customer adoption metrics shared on prior calls were not updated. The 'rule of 30-40' framing disappeared. The initial 2027 outlook promised on the second-quarter call was deferred to March 2027.
Fourth-quarter guidance calls for revenue of $15.0 million or more and adjusted EBITDA of $2.3 to $2.5 million. Management attributes the sequential revenue decline to typical seasonality and says pipeline timing could help it outperform. Even so, the guide implies year-over-year growth against a fourth quarter 2025 that ran in the low-$14 million range. Management says 2027 will be an 'increasing growth year' and that EBITDA can scale above the $10 million run rate despite planned sales and product investment. That investment is itself a risk to the newly established margin.
The balance sheet also changed meaningfully with the acquisition. Related-party obligations and contingent earn-outs now total roughly $16 million, including about $7.4 million classified as current. That compares with $8.7 million in cash, which did tick up from $8.2 million at the end of the second quarter. Stockholders' equity roughly halved from year-end to $14.7 million.
Investor sentiment swung sharply into the report, moving from -0.43 after the August release to +0.61. Investors moved from clearly negative to solidly positive expectations, which may explain why matching consensus while missing the whisper registers as a disappointment. Price action tells a less enthusiastic story:
- Shares sat at $1.30 before the report, down 24.9% from the $1.73 open following the August results.
- They were 17.1% below the $1.57 200-day moving average.
- The quarter included both a 52-week high of $2.00 in late August and a 52-week low of $1.15 in mid-September, leaving the stock just 13% above that low.
The Earnings Whispers price, sequential-growth and AVWAP readings remain negative, with only momentum positive.
The bottom line is that Marchex proved it can be profitable as a combined company, largely by cutting costs, but it has not yet proved the Archenia deal can produce the accelerating growth that was sold to investors. Roughly 5% combined growth, a low-end revenue print, softer gross margin and a deferred 2027 outlook leave the growth thesis resting on pipeline conversion and the OEM channel. Investors will not get hard numbers on either until March.
Read our earnings preview for Marchex, Inc.: https://www.earningswhispers.com/article/MCHX/22751
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-30 | |
| Oct-29 | |
| Oct-27 | |
| Oct-08 | |
| Sep-28 | |
| Sep-22 | |
| Sep-21 | |
| Sep-16 | |
| Sep-08 | |
| Aug-26 | |
| Aug-24 |
