Lumexa Imaging Beats On Accelerating Advanced Volumes, But The Guidance Raise Comes From Taxes
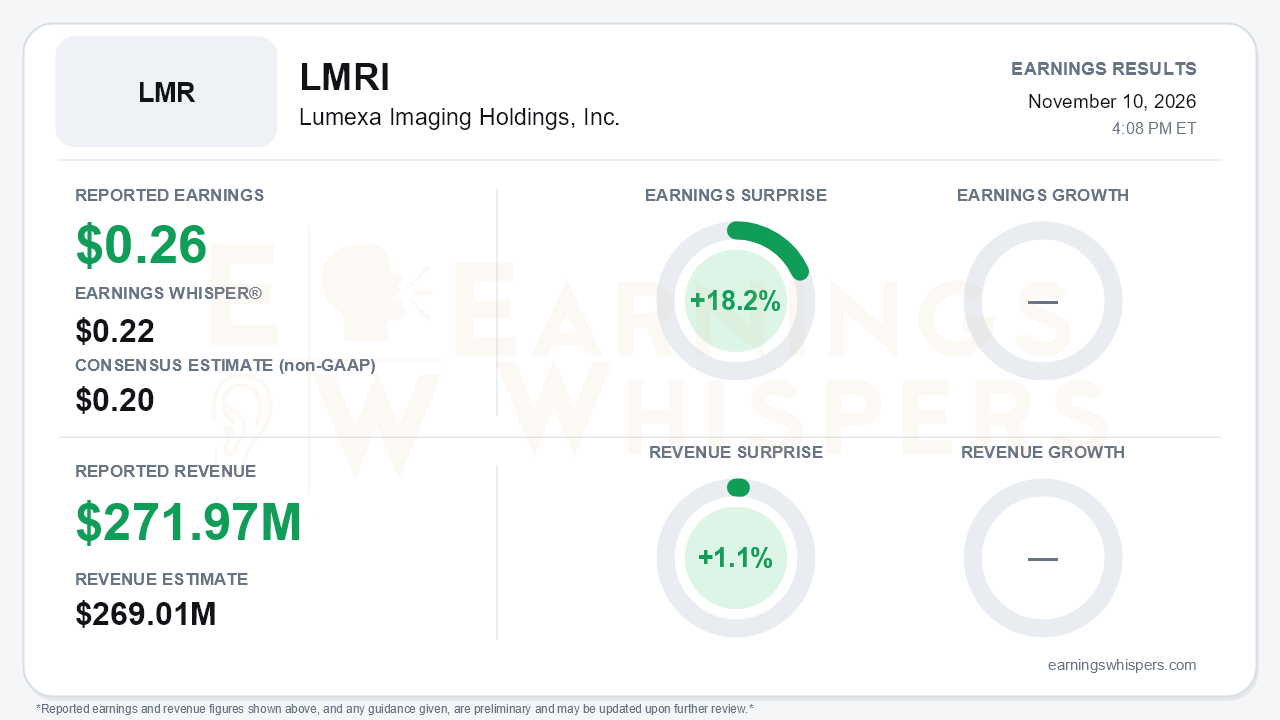
Lumexa Imaging delivered what the conference call framed as its cleanest quarter since the IPO. Adjusted EPS of $0.26 beat the $0.20 consensus by 18.2% and cleared the $0.22 Earnings Whisper number. Revenue of $271.97 million edged past the $269.01 million estimate by 1.1%. Adjusted EPS doubled from $0.13 a year earlier, and GAAP results swung from a $3.5 million net loss to $7.2 million of net income. More important than the beat is the trajectory: volumes, pricing, mix and margin all improved sequentially. The central tension is that the full-year outlook did not move with them. The headline earnings raise is a tax story. Revenue guidance and the adjusted EBITDA midpoint are unchanged.
The quality of the beat deserves scrutiny. The GAAP turnaround owes more to the balance sheet than to operations. Interest expense fell to $15.7 million from $30.6 million after the IPO-era recapitalization. Income from operations actually slipped to $28.1 million from $30.3 million because G&A jumped to $30.0 million from $17.1 million. That increase included higher stock-based compensation of $12.3 million versus $8.3 million and $3.6 million of litigation costs, both excluded from adjusted figures. Roughly $35 million of revenue is zero-margin pass-through, which flatters the top line without adding profit. Still, adjusted EBITDA rose to $62.6 million, and margin reached 23.0% versus 22.8%. That was the first year-over-year margin gain since the IPO, after margins of 21.4% in Q2 and 20.3% in Q1.
The operating story is genuinely improving, and it is improving in each quarter of the year:
- **Volumes:** System-wide procedure growth accelerated to 4.0%, from 3.1% in Q2 and 2.5% in Q1. Advanced-modality growth sped up to 8.1%, from 6.3% in Q2.
- **Mix:** Advanced procedures hit a record 38.2% of system-wide volume, up 145 basis points.
- **Pricing:** Revenue per scan grew 3%, versus 2.2% in Q2.
- **Revenue:** System-wide outpatient revenue grew 7.7%, versus 6% in Q2 and 4% in Q1.
- **Joint ventures:** Equity earnings climbed to $22.8 million from $18.0 million a year earlier.
Cash generation is the other clear upgrade. Free cash flow was $20.6 million, a 32.9% conversion of adjusted EBITDA. Management lifted full-year conversion guidance to at least 30%, from 25-30%. Cash rose to $90 million, and net leverage eased to 3.5x.
The catalyst list lengthened. An expanded Advocate Health partnership takes Lumexa into Illinois as its 10th health-system JV. CMS finalized the 2027 site-neutral rule, which management now frames as a roughly $77 billion addressable market. Three de novos opened in early November, and the company reiterated its 8-10 opening target. AI tools such as FastScan are now deployed across most of the enterprise. Bears have legitimate ammunition, however:
- **Medicare rates:** The final 2027 Physician Fee Schedule came in about 1% lower, versus a prior flat assumption, and roughly 20% of revenue is Medicare. Management called the impact limited because 2027 commercial contracts are largely done.
- **Capex:** Spending stepped up to $14.2 million, well above the earlier $5-7 million quarterly framework.
- **Footprint:** Center count declined on closures, and only five de novos are open year-to-date against the 8-10 goal.
- **Professional fees:** Growth slowed to 2.6% from 5%.
- **Guidance quality:** The adjusted EPS range rose to $0.86-$0.90 from $0.71-$0.77 because of a lower assumed tax rate. The EBITDA range of $236-$240 million was merely narrowed. That outlook implies a fourth-quarter step-up to the high-$60 million range, so execution has to continue.
The market setup is more complicated than the surprise implies, because investors already anticipated much of the improvement. Earnings Whispers sentiment swung from -0.14 at the prior report to +0.41, a substantial shift from mildly negative to clearly positive. Shares closed at $13.97 the day before the release. That is 18.5% above the post-August open and 26.5% above the $11.05 200-day moving average. The stock sat just 1.4% below its inter-earnings high of $14.17, set that same day, and 42% above its late-September low of $9.83. Momentum and AVWAP trend readings are positive, consistent with a stock entering the report with strength rather than skepticism.
The bottom line is that Lumexa produced real operating progress: accelerating advanced volumes, better pricing, rising JV contributions, expanding margins and stronger cash conversion. Those trends support a credible growth narrative tied to site neutrality. However, the raised EPS outlook rests on taxes, core guidance only held its midpoint, and Medicare and capex pressures emerged. With sentiment and price both running ahead into the print, the bar for the fourth quarter has moved meaningfully higher.
Read our earnings preview for Lumexa Imaging Holdings, Inc.: https://www.earningswhispers.com/article/LMRI/22748
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-28 | |
| Aug-25 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Jul-29 | |
| Jun-02 | |
| May-13 | |
| May-12 | |
| May-12 | |
| May-12 |
