Fossil Returns To Growth A Quarter Early And Raises Guidance Again, But Pull-Forward And Royalty Timing Flattered The Q3 Beat
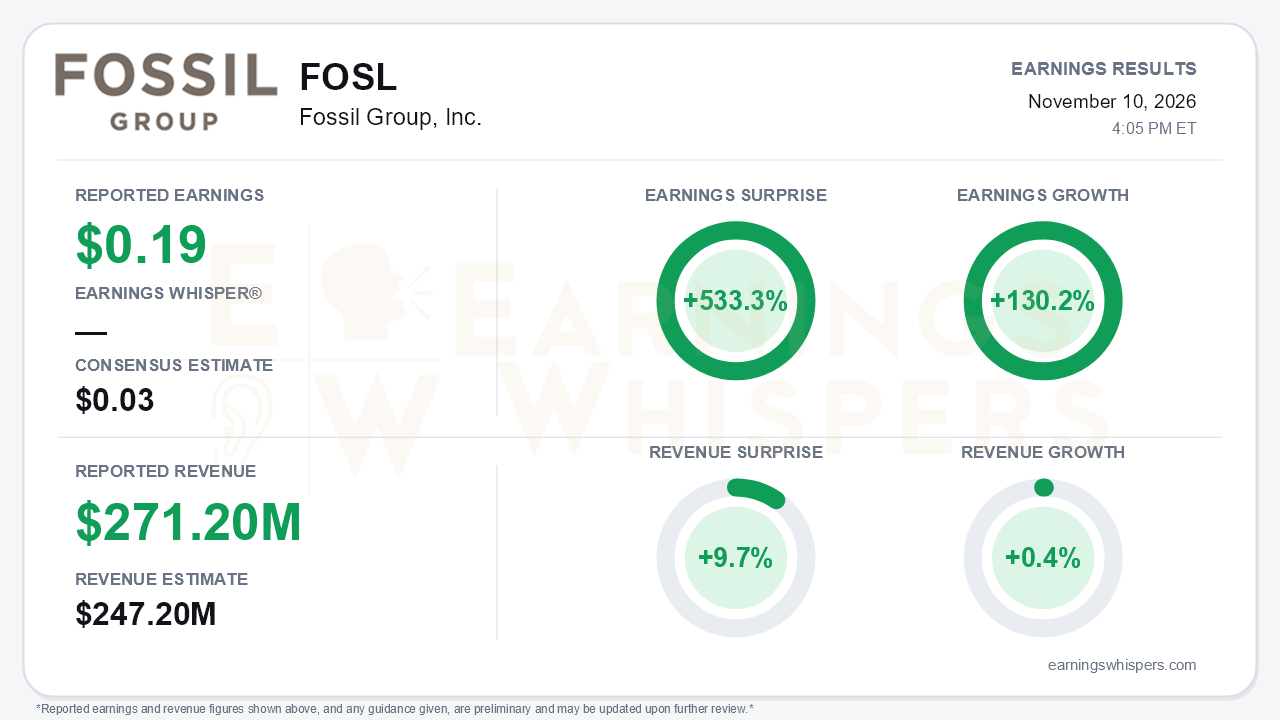
Fossil Group delivered the kind of quarter turnaround skeptics were not positioned for. The company earned $0.19 per share on a GAAP basis against a $0.03 consensus estimate, a 533.3% surprise, compared with a $0.76 loss a year earlier, which works out to 130.2% earnings growth. Revenue of $271.2 million beat the $247.2 million consensus by 9.7% and edged up 0.4% year over year. Constant-currency sales rose 2.0%, Fossil's first growth quarter of the turnaround and one quarter ahead of management's plan. Management also raised full-year guidance for the second straight quarter. The central tension is that the beat was helped by timing in both revenue and gross margin, so the quality of the quarter deserves more scrutiny than the headline surprise suggests.
Start with the top line. Management disclosed that roughly $10 million of wholesale shipments moved from the fourth quarter into the third. That accounts for a meaningful share of the $24 million revenue beat. Without the pull-forward, reported sales would likely have declined modestly.
The gross margin needs similar caution. It jumped 10.8 points to 59.8%, but the release attributes much of that to lower licensed-brand minimum royalties and the accelerated timing of minimum royalty recognition. On the call, management explained that royalty-shortfall charges are now spread across all four quarters, so the usual third-quarter dip did not occur. That makes the year-over-year comparison less clean. Even so, the cost work is real:
- SG&A fell 8.8% to $133.9 million, or 49.4% of sales.
- Restructuring charges dropped to $2.9 million.
- Constant-currency adjusted operating income reached $30.2 million, an 11.0% margin, versus a $14.4 million loss a year ago and $8.6 million of adjusted EBITDA in the second quarter.
Below the operating line, the picture is less tidy. Interest expense more than doubled to $8.9 million on higher debt and rates, and a 44.6% effective tax rate absorbed much of the pretax gain. Adjusted EPS was $0.23.
The underlying sales trajectory is the strongest part of the story. In constant currency, sales fell 20% in the fourth quarter of fiscal 2025, then declined 6% and 4% in the first two quarters of 2026 before turning positive. Drivers included:
- The Fossil brand grew 13.6%.
- Traditional watches rose 6.4%.
- Wholesale increased 4.4%.
- Asia jumped 15.1%, with India singled out as exceptional.
- This came despite a roughly 190-basis-point drag from store closures.
The weak spots remain:
- Leathers fell 20.5% and jewelry 10.8%.
- Smartwatches have nearly vanished.
- Direct-to-consumer sales declined 5.9% on flat comps.
- Europe fell 5.6%, pressured by the Middle East conflict and the shift to distributor models.
This is a watch-led recovery, not a broad portfolio revival.
The forward catalysts are substantive:
- The Diesel license was extended through 2032, and the Nick Jonas ambassador deal was renewed, with a new collection planned for the second half of 2027.
- The Swiss-made Signature CS1 and Machine X1 lines are selling ahead of expectations.
- Management described Armani and Michael Kors extension talks as in advanced stages, with confidence that "remains high." Neither renewal is signed, however, and those licenses remain the largest overhang.
- The store closure program is essentially complete, leaving 174 stores.
Full-year sales guidance now stands at $980 million to $990 million, up from $955 million to $975 million, and the adjusted operating margin outlook rose to 5.5% to 6.5% from 4% to 6%. Management now expects positive full-year GAAP net income. Because year-to-date net income is just $0.2 million, that commitment rests on the fourth quarter, which has already lost about $10 million of shipments and is guided to SG&A in the low 50s as a percentage of sales as marketing spend rises.
The balance sheet gives bears legitimate ammunition. Inventory rose 13.4% to $189.2 million, a reversal from a 14% decline in the first quarter. Management frames this as investment behind demand. Other pressure points:
- Total debt climbed to $208.0 million from $176.1 million a year ago.
- Cash slipped to $77.0 million.
- Stockholders' equity shrank to $80.7 million.
Positive free cash flow guidance was reaffirmed rather than raised.
The market had largely embraced the turnaround before the print. Shares climbed 37.3% from the $5.87 open after the August report to $8.06. They finished the pre-report snapshot just 2.3% below a $8.25 52-week high set on November 9 and about 63.5% above the 200-day moving average. The stock has rallied 86% from its September low. Earnings Whispers price, momentum and AVWAP trend readings are all positive. Investor sentiment swung decisively from modestly negative (-0.30) to strongly positive. The supplied current reading of 5.67 falls outside the stated -1 to +1 scale, so its precise magnitude should be treated cautiously, but the direction of the shift is unambiguous. In practice, Fossil entered the report with expectations already rising, which raises the bar for the fourth quarter.
The bottom line is that Fossil showed a credible turnaround: growth returned early, guidance rose twice, and cost discipline is producing real operating leverage. However, a Q4-to-Q3 shipment shift and a change in royalty accounting flattered the beat. Rising inventory, heavier debt service and unsigned Armani and Kors renewals keep the risk profile elevated. With the stock trading near its highs, the fourth quarter's ability to absorb the pull-forward and still deliver full-year GAAP profitability is now the key test.
Read our earnings preview for Fossil Group, Inc.: https://www.earningswhispers.com/article/FOSL/22739
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| 6 hours | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-20 | |
| Oct-08 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Jul-22 |
