Firefly Aerospace Beats And Lifts Its Revenue Floor, But The $1.3B AST Deal Arrives Alongside Another Alpha Block II Slip
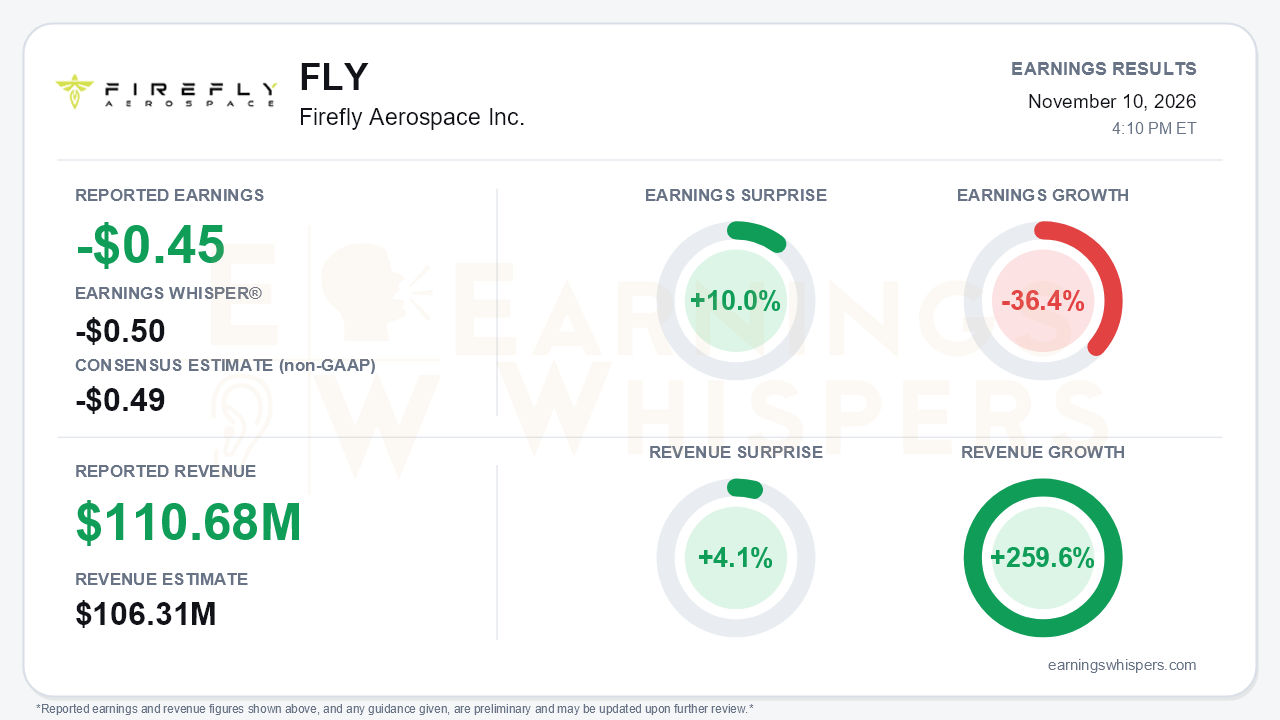
Firefly Aerospace (NASDAQ: FLY) beat third-quarter expectations, but the bigger story is how the business is changing. The company posted a non-GAAP loss of $0.45 per share, better than the -$0.49 consensus and the -$0.50 Earnings Whisper number, a 10.0% upside surprise. Revenue of $110.68 million topped the $106.31 million consensus by 4.1% and grew 259.6% year over year, faster than the roughly 203% year-to-date pace. Management also raised the low end of 2026 revenue guidance, narrowing the range to $440-$450 million from $420-$450 million. The central tension is that the commercial franchise is expanding quickly, led by a more than $1.3 billion AST SpaceMobile agreement and a record $1.7 billion backlog, while Alpha, the company's namesake rocket, keeps slipping to the right.
The quality of the beat deserves scrutiny. Earnings Whispers calculates that earnings fell 36.4% year over year, and the dollar figures show why. Non-GAAP net loss widened to $75.4 million from $51.4 million. The per-share loss looks smaller mainly because the weighted share count rose to 168 million from 94 million after the IPO. Adjusted EBITDA loss deepened to $69.5 million from $46.3 million a year ago and from $61.2 million in Q2, driven largely by higher R&D. On a GAAP basis, the net loss of $94.2 million improved from $133.4 million, but only because last year carried warrant and debt-extinguishment charges.
There were genuine sequential improvements:
- Gross margin recovered to 22.9% from 20.3% in Q2, though it remains below the 27.7% reached in Q4 FY25.
- Free cash outflow narrowed to $85.3 million from $106.3 million in Q2.
Revenue also dipped sequentially from Q2's record $117.7 million, which included an accelerated hardware order. The guidance range implies a Q4 of roughly $131-$141 million.
The call recast Firefly's medium-term story around the AST deal. The agreement includes:
- an IP license worth about $400 million in cash plus 10-14 million AST shares;
- $250 million of support services;
- $250 million of engine deliveries, covering 27 Miranda and 9 Vera engines.
Management said the deal should lift gross margin from the mid-20s and help fund Eclipse and Alpha capacity. Management's language shifted from "momentum" to "transformative." Executives also described Alpha demand as the most supply-constrained ever and cited pricing above the $22 million VICTUS SOL contract. The order book supports that tone. Backlog has climbed from $1.3 billion in Q1 to $1.5 billion in Q2 and about $1.7 billion now, on more than $300 million of new Q3 awards. New Alpha business includes Firefly's first European launches with SSC Space, a Synspective deal for up to 10 launches, an extension of Lockheed Martin's agreement for up to 25 Block II launches, and a third hypersonic task order. Firefly also joined NASA's $10 billion CLPS 2 program and the $981 million Space Force NITE-STAR IDIQ.
Bears have legitimate ammunition. Alpha Flight 8, the Block II debut, has now moved from late summer to Q4 2026 to Q1 2027. Planned 2026 launches have fallen from four to three to effectively just Flight 7. Management declined to give a 2027 launch target, and Eclipse's first-launch timing was not explicitly reaffirmed. Launch revenue fell to $4.7 million from $9.4 million in Q2 and $13.3 million in Q1. That is an awkward contrast with a growing launch backlog that depends on an unproven vehicle cadence.
The AST deal also carries caveats:
- Revenue is back-loaded, with engine deliveries starting in year two.
- AST could eventually build Miranda engines itself.
- Capex and R&D are guided materially higher to support the program.
Higher spending will lift near-term cash burn just as liquidity has slipped to $839.7 million from $940.3 million.
Investor sentiment has turned sharply. It fell from +0.36 at the prior report to -0.22, a meaningful swing from optimism to skepticism. The price action has been volatile. Shares hit $28.20 just after the Q2 report, collapsed to a 52-week low of $14.45 on Nov. 5, then rebounded 68% to $24.31 before the release. The stock remains 9.0% below its post-Q2 opening price and about 9.5% below its 200-day moving average. Momentum and AVWAP trend readings have turned positive, consistent with that rebound. Even so, the market setup is more complicated than the surprise implies, because a good part of the recovery came before these results were published.
The bottom line is that Firefly delivered a clean headline beat, a firmer revenue floor, record backlog and a potentially margin-accretive AST partnership, which together preserve a credible growth story. But losses are widening in dollar terms, cash burn will rise with AST-related investment, and Alpha's repeated delays leave the launch business more promise than proof. Execution on Flight 8 in early 2027 is now the swing factor for whether this quarter's backlog becomes reported revenue.
Read our earnings preview for Firefly Aerospace Inc.: https://www.earningswhispers.com/article/FLY/22738
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 |
