UTI Must Prove Its Guidance Cut Was An Execution Stumble, Not A Demand Problem
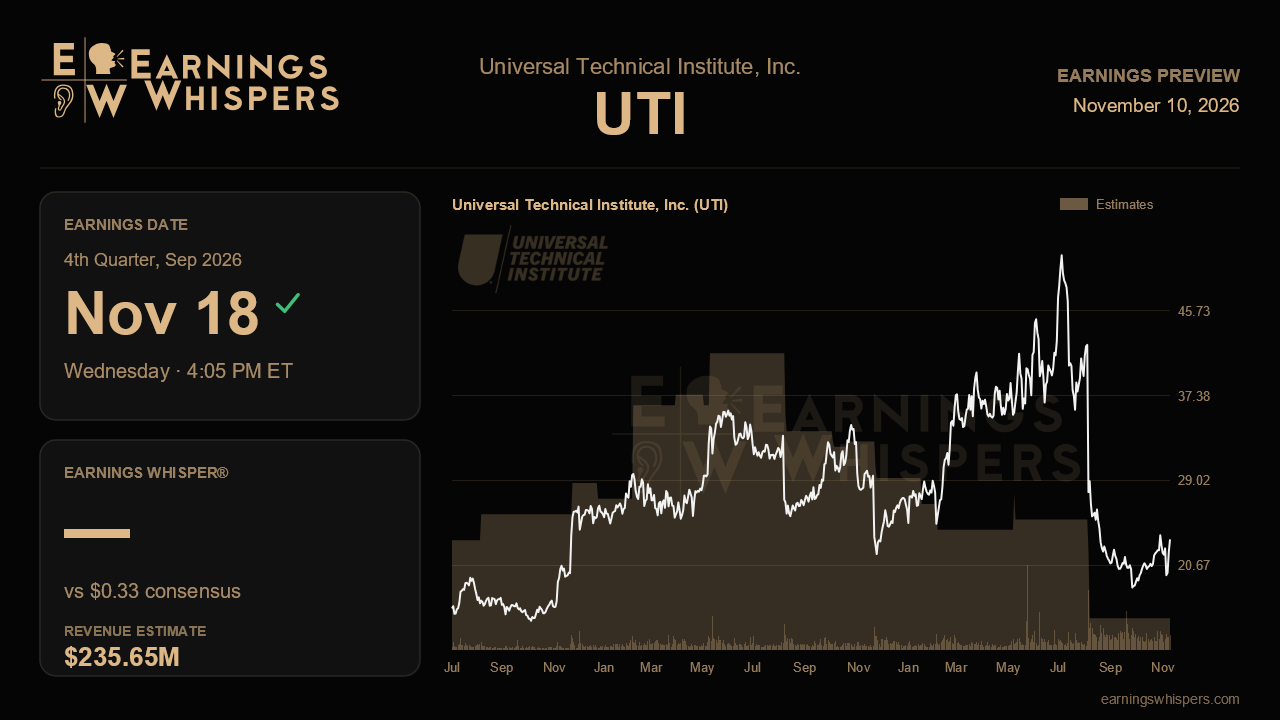
Universal Technical Institute heads into its fiscal fourth-quarter report with an unusual split personality. Demand indicators looked excellent last quarter, with new student starts up 11% and the flagship UTI division up 23%. Yet management still cut its full-year outlook across every profitability line. The report after the close on November 18 is essentially a referendum on that explanation. Was the damage really a contained, fixable problem in one recruiting channel, or the first crack in a growth story the market had priced generously?
The Street is looking for earnings of $0.33 per share on revenue of $235.7 million. That would be revenue growth of about 5.9% from a year ago but a slight decline in earnings from $0.34. In other words, the top line keeps moving while profit stalls. That is the pattern you would expect if students are flowing into lower-priced programs and the company is spending ahead of new campuses. The revised full-year guidance calls for earnings of $0.57 to $0.64 per share on revenue of $893 million to $900 million, down from $0.71 to $0.80 and $905 million to $915 million. Full-year consensus sat at $0.76 when the cut landed, above even the old midpoint, so estimates have had to come down a long way. The key question is whether the quarterly number now fully reflects management's lower bar or still carries some leftover optimism.
Management blamed about 70% of the roughly $20 million EBITDA shortfall on weak fourth-quarter high-school starts in automotive and diesel. It called this an execution problem: the field admissions team ran at about 140 representatives, too few to convert lead flow that was up more than 15%, and the company responded by raising headcount about 20% to 170 or more. The remaining 30% came from students shifting toward shorter skilled-trades programs faster than planned, and those programs carry less revenue and margin. The cleanest validation would be fourth-quarter starts landing inside the tightened range of 31,900 to 32,300, plus evidence that the larger rep force is already lifting high-school conversion heading into fiscal 2027. A challenge would be starts at the low end, or signs that the mix shift is accelerating rather than stabilizing. Either would suggest the margin pressure is structural rather than a one-quarter hiccup.
There are offsetting stories worth tracking. UTI Atlanta's first start was running 30% ahead of plan and San Antonio about 40% ahead of its launch model. That is strong, though San Antonio's lead has narrowed from the roughly 60% beat cited the quarter before. The UTI and Concord operating model was unified at the end of July, so this is the first full quarter to show whether promised cost synergies are real. Investors should also want updates on the four fiscal 2027 campus openings, the pull-forward that lifted capex to about $110 million, and whether B2B talks with an EV maker, airlines and defense contractors have produced anything concrete.
The market has delivered its verdict on the cut. Shares have fallen 25.3% since the last report while the S&P 500 slipped 2.6%. At $23.21, the stock trades far below its 200-day average of $32.07, and its entire post-earnings range of $18.02 to $31.87 sits beneath the prior quarter's low. Sentiment has soured as well, with bearish readings deepening to 48.4% from 23.2% heading into last quarter. That pessimism lowers the bar somewhat, but it also signals that patience with execution excuses is thin.
Ultimately, this report hinges on whether management can show that the shortfall was confined to fiscal 2026's fourth quarter. Results inside the revised guidance, stable margins on the program mix, and a credible early read on fiscal 2027 would support the view that the demand engine is intact. Another reset would make the company's long-range targets of more than $1.2 billion in revenue and about $220 million in EBITDA by fiscal 2029 much harder to take at face value.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-10 | |
| Oct-29 | |
| Oct-28 | |
| Oct-24 | |
| Oct-21 | |
| Sep-29 | |
| Sep-21 | |
| Sep-09 | |
| Sep-02 | |
| Aug-20 | |
| Aug-18 | |
| Aug-11 | |
| Aug-06 | |
| Aug-05 | |
| Aug-05 |
