Worksport Posts Record Sales And Near-Breakeven Cash Burn, But Quietly Drops Its Full-Year Targets
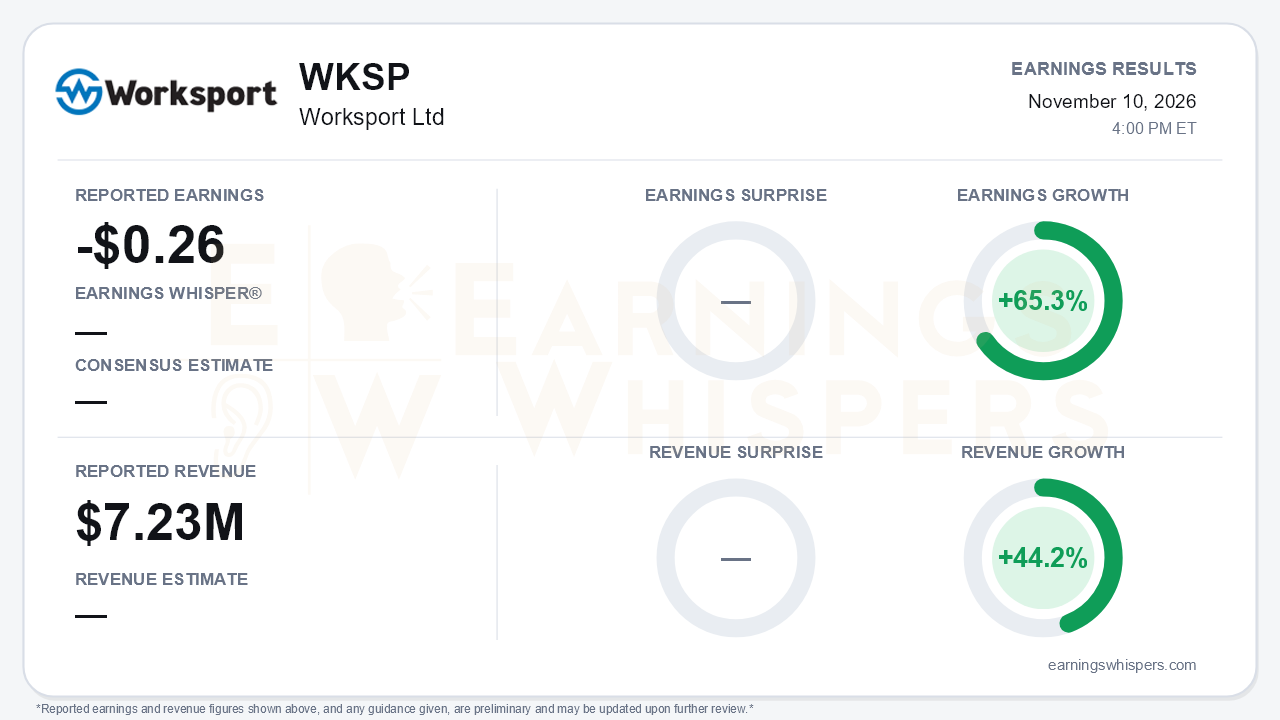
Worksport (NASDAQ: WKSP) delivered the operating-leverage quarter it has been promising. It also stopped repeating the dated targets that defined its 2026 story. The company reported a loss of $0.26 per share on record revenue of $7.23 million for the September quarter. Revenue grew 44.2% year over year, and earnings improved 65.3% from the $0.75 per-share loss a year earlier. No consensus estimate was available, so there is no surprise to judge. The more useful comparison is sequential. Sales rose 38% from $5.2 million in Q2 and have more than doubled from $3.3 million in Q1. Operating cash use collapsed to roughly $0.4 million from $3.4 million in Q2 and $8.2 million in Q1. That is the central tension: the income statement is finally scaling, while the full-year revenue guide and the dated cash-breakeven goal have both disappeared.
The per-share improvement flatters the quarter. Weighted shares more than doubled to 13.6 million from 6.6 million a year ago, and shares outstanding reached nearly 20 million at quarter-end versus 9.8 million in December. Net loss narrowed a more modest 27% year over year to $3.6 million and only 9.3% sequentially from $3.97 million. The genuine leverage sits in the cost base:
- Net sales rose about $2.0 million sequentially, while operating expenses rose only about $85,000, to $5.6 million.
- Operating expenses fell 11.7% year over year and dropped to roughly 77-78% of sales from 127%.
- Sales and marketing fell to 25% of sales from 47% a year ago.
Gross margin moved the wrong way. It slipped to 30.3% from 31.5% in Q2 and 31.3% a year ago, still well short of the 35% FY26 target. Management blamed aluminum costs, which it said have doubled on tariff-driven inflation, and a richer B2B mix.
Demand is the strongest part of the story. NEXUS sales reached about $4.8 million, up roughly 150% sequentially and about two-thirds of revenue. Large distributor orders rose about sevenfold, and B2B reached about half of September sales versus 40% in June. Revenue climbed every month of the quarter, from $2.2 million in July to $2.7 million in September. Orders of about $7.9 million ran ahead of shipments, lifting backlog to about $740,000 from $117,000. COR launched on Amazon in September, a channel management had dismissed on the Q1 call. The catch is that the fastest-growing channel is also the one diluting margin. Growth is coming partly at the expense of the 35% gross-margin goal.
The cash improvement also deserves scrutiny. Q3 operating cash flow benefited from about $2 million of working-capital release, led by inventory falling to $9.6 million from $12.1 million, and management said this is not a run rate. Strip it out and the underlying burn looks closer to $2.3-2.4 million: the $3.6 million net loss less about $1.3 million of non-cash charges. That is better than earlier in the year but far from breakeven. Management's earlier aim of sustainable operating cash breakeven in 2026 has been replaced with no calendar target. The $35-42 million FY26 revenue guide went unmentioned, and with nine-month sales of $15.8 million it is effectively out of reach.
AetherLux certification has also slipped. It moved from a fall/October target to Q4 2026, and pilot installations are now targeted for Q1 2027. A non-binding term sheet to acquire a patented truck-bed accessory business adds a bundling catalyst for NEXUS, but it remains subject to diligence and definitive agreements.
Financing is the binding constraint, and the market setup reflects it:
- **Liquidity:** Cash rose to $2.53 million from $1.2 million, but mainly because of the August warrant inducement. That deal issued 3.8 million shares plus new warrants for up to 4.8 million shares at $0.60. The company also has $1.8 million of revolver availability.
- **Balance-sheet relief:** The credit facility was renewed through July 2028, and a roughly $2.7 million equipment obligation was released.
- **Listing risk:** Worksport now faces a Nasdaq $1 minimum-bid deficiency with a February 2027 deadline, plus a possible extension.
- **Valuation:** Management cited a market value of about $6 million against roughly $20 million of book value. The balance sheet shows $18.8 million of equity.
Shares opened at $0.74 after the August report, below the current 200-day moving average of $0.86. That points to a stock that has been trading under its longer-term trend even as operations improved. Current price and sentiment readings were not available, so the post-report reaction cannot yet be assessed. Each equity raise at these levels remains costly to existing holders.
The bottom line is that Worksport showed real operating traction. Revenue is growing far faster than expenses, demand from distributors is accelerating, and the loss per dollar of sales has fallen from $1.76 in Q1 to $0.49. But the quarter's best cash number leaned on one-time inventory release, margins are moving away from target, and management retreated from its revenue and breakeven timelines. Bulls can point to a credible scaling story. Bears have legitimate ammunition in dilution, listing risk and a still-meaningful underlying burn.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 6 hours | |
| 12 hours | |
| Nov-10 | |
| Nov-04 | |
| Nov-03 | |
| Oct-06 | |
| Sep-30 | |
| Sep-10 | |
| Aug-26 | |
| Aug-11 | |
| Aug-10 | |
| Jul-29 | |
| Jul-22 | |
| Jun-25 | |
| Jun-22 |
