HIVE Digital Beats On A Sequential Rebound, But A Defensive Pivot And Shrinking Cash Overshadow The Quarter
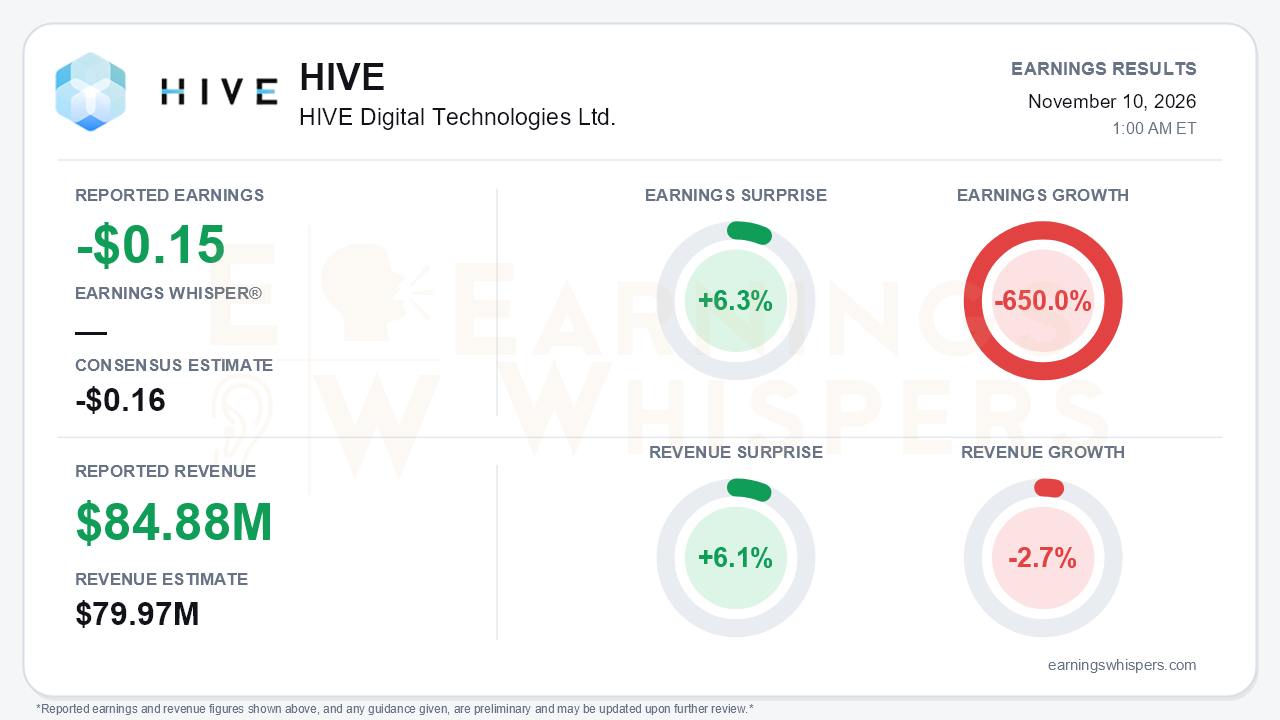
HIVE Digital Technologies beat expectations on both lines for its fiscal second quarter ended September 2026. The company reported a loss of $0.15 per share against a consensus estimate of -$0.16, a 6.3% surprise. Revenue of $84.88 million topped the $79.97 million consensus by 6.1%. The beat was real, but it was a sequential recovery rather than a growth story. Revenue fell 2.7% year over year, and earnings fell 650.0% from the year-ago period. The more consequential development came from management. After quarters of expansive re-rating talk, it pivoted to a defensive, 'cash is king' posture, and that changes the investment setup more than a one-cent beat does.
The operating improvement from the June quarter is genuine. Revenue rose 7.3% sequentially. Gross operating margin climbed to $30.2 million, or 35.6% of revenue, from $24.2 million, or 30.6%. Adjusted EBITDA nearly doubled to $24.8 million from $13.4 million. Mining did most of the lifting: average network difficulty eased, and HIVE booked 1,070 Bitcoin versus 1,004 in Q1. The year-over-year view is less flattering. A year ago, gross operating margin was 49% on $42.4 million and adjusted EBITDA was $31.5 million, so profitability remains well below where it was before a 27% drop in Bitcoin prices. The GAAP net loss of $78.7 million included:
- $54.9 million of depreciation;
- a $31.2 million non-cash impairment of ASIC miners, taken because of weak hash economics and falling resale values;
- $7.3 million in derivative losses.
The impairment is non-cash, but it is an explicit admission that the mining fleet is worth less than it was carried at. That is a meaningful signal for a company whose revenue is still roughly 90% digital currency.
The AI side, operating as BUZZ HPC, is where the growth narrative lives, and it held up:
- HPC revenue rose 70.7% year over year and 25.3% sequentially to $8.8 million, helped by a B200 cluster in Manitoba.
- HPC gross margin improved to about 51% from roughly 44%.
- Live GPU cloud ARR reached about $40 million, up from $35 million at the Q1 call.
- Contracted ARR edged up to $185 million from $180 million.
- The roughly $200 million calendar year-end target was maintained.
- Management nudged its GPU cloud EBITDA margin target to about 80%.
CEO Aydin Kilic said current GPU-hour market prices exceed contracted rates from six months ago, a constructive demand read. Still, the gap between $40 million live and $185 million contracted is the whole thesis, and closing it depends on hardware shipping and entering service on schedule.
That execution path looks more constrained than it did a quarter ago. Cash fell to $139 million from $208 million. Management said further capex is on hold pending a market recovery and effectively ruled out using the ATM at current prices. That matters because HIVE raised $43.2 million last quarter at an average of $3.15 per share, and the stock now trades at $1.72. The GB200 cluster for Bell AI Fabric and Cohere is funded through debt; the release cites $129 million of financing, while the call described a $120 million loan at 9%. The Bowdoin colocation deal, worth about $45 million in potential annual revenue, missed its end-of-September signing target and remains at the letter-of-intent stage with no new date. Management's own valuation framing was cut to roughly $1.4 billion near term from about $2 billion, and to $3.9 billion for the full roadmap from $5.2 billion. Management also flagged political headwinds for U.S. data centers and turmoil in Paraguay. The $84.5 million Swedish VAT provision still sits on the balance sheet.
There are credible offsets. Ontario's data center playbook and the premier's pledge to approve projects 'sooner rather than later' support the 320 MW Greater Toronto Area pipeline. The New Brunswick campus expanded to 64 acres, and an additional 100 MW at Yguazú is slated for energization this quarter. These are optionality, though, not revenue, and the $700 million 2028 HPC ARR goal is explicitly an unfunded target.
The market is not giving the company the benefit of the doubt. Investor sentiment sits at -0.42, firmly negative, though no prior reading is available for comparison. Shares at $1.72 are 38.1% below the 200-day moving average of $2.78. The supplied quarterly high and low ($1.85 and $1.66) both date to the report session itself, so the post-earnings reaction amounts to a volatile trade near depressed levels. The Earnings Whispers trend readings lean negative, with price trend negative and AVWAP neutral.
The bottom line is that HIVE delivered a cleaner quarter than expected, with real sequential margin repair and steady GPU cloud progress, but the headline beat masks a more cautious company. Shrinking cash, a mining impairment, a slipped colocation deal, a closed equity window and lowered valuation ambitions mean the AI build-out now hinges on financing discipline rather than momentum. Until contracted ARR converts into recognized revenue, bears have legitimate ammunition.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 6 hours | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-09 | |
| Nov-09 | |
| Nov-05 | |
| Nov-05 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 | |
| Oct-28 |
