Gogoro's Record 24.4% Gross Margin Is Overshadowed By Its First Revenue Guidance Cut As Q2's Recovery Story Stalls
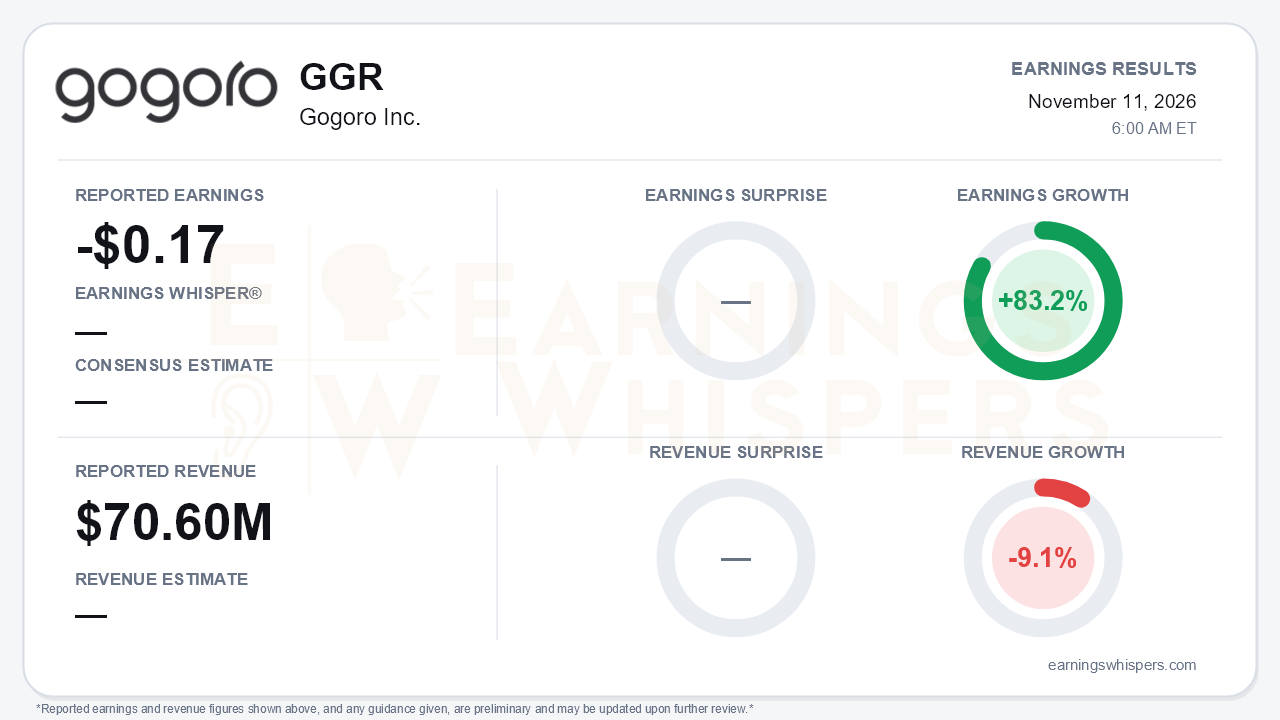
Gogoro's third quarter delivered the cleanest-looking income statement in the company's recent history, and also its most sobering outlook. The company lost $0.17 per share, compared with a $1.01 loss a year earlier, which Earnings Whispers measures as 83.2% earnings growth. The IFRS net loss shrank to $3.4 million from $14.9 million. Revenue, however, fell 9.1% to $70.6 million. Management also cut full-year revenue guidance to $270–$290 million from $285–$305 million, a range it had set in Q4 2025 and reaffirmed in each of the past two quarters. That is the central tension: margins are at a record while the top line is shrinking, and the Q2 recovery narrative, when revenue grew 7.3%, did not survive the quarter.
The quality of the earnings improvement deserves scrutiny. IFRS gross margin doubled to 24.4% from 12.2%, but much of that gain is the absence of $7.7 million in battery-upgrade costs. That program ended in Q4 2025, and those costs are already excluded from non-IFRS results. On a non-IFRS basis, margin improved more modestly, to 24.4% from 22.2%. Non-IFRS gross profit was essentially flat at $17.2 million. Adjusted EBITDA slipped to $19.0 million from $20.2 million a year ago and from $19.3 million in Q2.
Other items flattered the bottom line:
- **Lower depreciation:** expense fell about $3.3 million.
- **Share-based compensation reversal:** a turnover-rate update produced a net credit, compared with a $559,000 charge last year.
- **Accounting estimates:** management attributed the narrower non-IFRS net loss of $3.9 million primarily to a $3.4 million favorable impact from changes in accounting estimates.
The operating discipline is real. Operating expenses fell $3.0 million, and the sequential gross-margin climb from 14.3% in Q4 2025 to 20.4%, 22.6% and now 24.4% shows genuine progress. But the profit improvement is less organic than the headline swing suggests.
Beneath the margins, the revenue drivers diverged:
- **Battery swapping:** the subscription business held up. Subscribers rose to about 684,000 from 657,000 a year ago, and swapping revenue grew 1.8% in constant currency even as a lower-mileage subscriber mix weighed on ARPU.
- **Hardware:** revenue fell 13.5% (7.5% in constant currency). Gogoro-branded and PBGN scooter registrations dropped 9.7%, and component and shared-scooter revenue also declined.
Currency cost about $4.8 million, so constant-currency revenue declined only 2.9%. Still, that is a sharp reversal from roughly 10% constant-currency growth in Q2. The Luna launch lifted average selling prices, but management framed the strategy as choosing product economics over volume driven by aggressive marketing spending. That is a defensible choice, though it also concedes share. The roughly 6% market-share recovery cited last quarter was not repeated. The call's tone moved from "position of strength" to "realistic about the challenges."
The forward-looking language raises its own caution flags:
- **Margin durability:** management warned the record gross margin may be hard to sustain as raw material and component costs rise.
- **Taiwan growth:** management said Taiwan alone will not drive significant growth.
- **Profitability targets:** the 2026 non-IFRS profitability goal for the Gogoro Network, repeated on every prior call, went unmentioned. Management introduced a free cash flow target for 2027 and kept profitability in 2028.
- **Spending pressure:** the release itself says higher brand, channel and Vietnam spending will moderate further sequential profit improvement.
Cash generation also cooled. Nine-month operating cash flow rose just 8.8%, against more than 70% growth through the first half. A $14.3 million inventory build was a meaningful drag.
The catalysts are real but early. Vietnam has progressed from a plan to an operating pilot. The Castrol joint venture is building swapping infrastructure in Ho Chi Minh City, and two delivery platforms report riders covering roughly 150–160 kilometers a day. That market sold about 735,000 electric two-wheelers in 2025 and has already surpassed that total in 2026. The October close of $61.8 million in equity funding removes near-term liquidity anxiety. That matters given:
- $68.9 million in quarter-end cash;
- $92.3 million in current borrowings;
- $25 million in put obligations now classified as current.
The funding came at a cost. The 24.9 million new shares more than double the roughly 20 million share base used for Q3 per-share results, which will dilute future per-share comparisons. The funding also deepens reliance on the largest shareholder, a concentration issue an investor raised on the call.
Investor sentiment readings and current technical data were not available for this report, which limits what can be said about positioning. One reference point does stand out. The October placement was priced at $2.48 per share, above the $2.14 opening price after the Q2 report. Whether that premium holds will be an early test of how investors weigh a stronger balance sheet against a weaker revenue outlook.
The bottom line is that Gogoro has largely fixed its cost structure but not its demand problem. Record margins, a narrower loss and fresh capital make the company sturdier. The guidance cut, the dropped 2026 network profitability goal, the caution on margins and softening cash flow make the path to growth less certain. Vietnam is now the swing factor, but it remains a pilot, and Taiwan will still supply roughly 95% of 2026 revenue.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| 3 hours | |
| 5 hours | |
| Oct-22 | |
| Oct-07 | |
| Oct-07 | |
| Sep-13 | |
| Aug-24 | |
| Aug-24 | |
| Aug-24 | |
| Aug-24 | |
| Aug-03 | |
| Jul-05 | |
| Jun-23 | |
| May-28 |
