UCloudlink Beats On Revenue And Narrows Its Loss, But A Sub-Dollar Stock Leaves Little Room For Error On Q4 Guidance
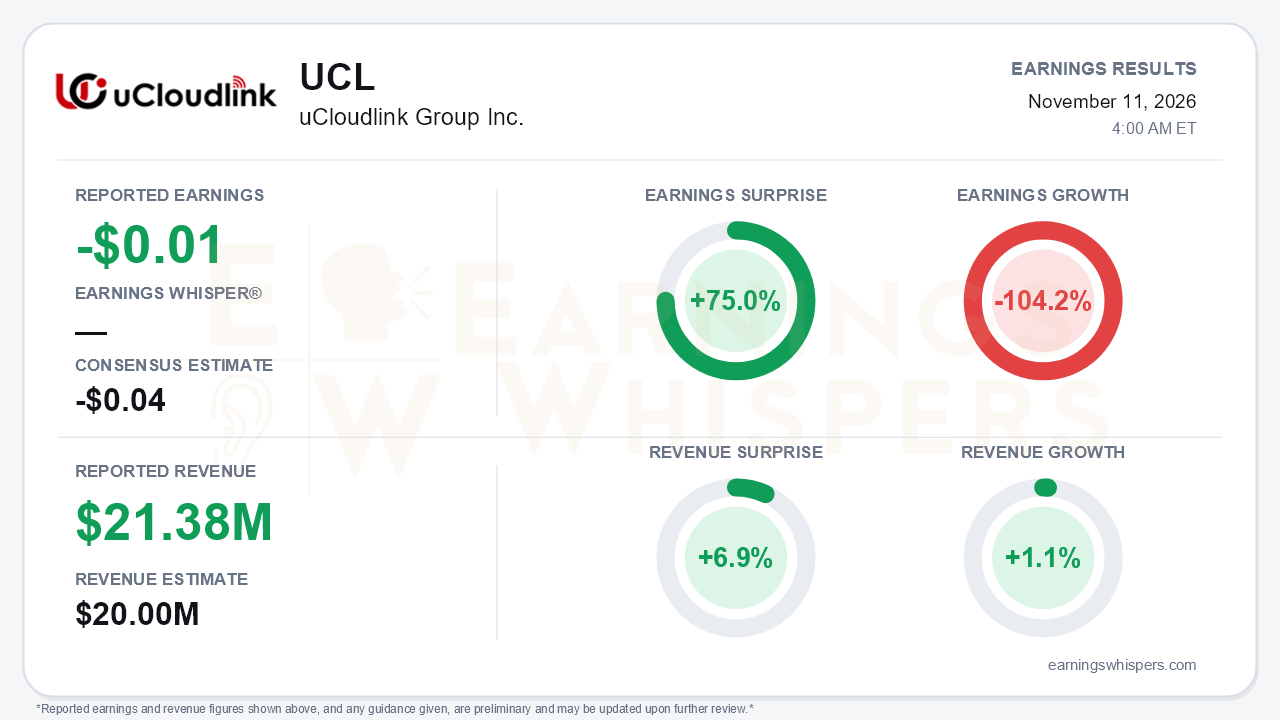
uCloudlink delivered the inflection it failed to produce last quarter. The company reported a loss of $0.01 per ADS, beating the -$0.04 consensus by 75.0%. Revenue of $21.38 million topped the $20.0 million estimate by 6.9% and grew 1.1% year over year. That is a modest gain, but it was the first positive year-over-year print after declines of 10.1% in Q1 and 5.9% in Q2. It also landed at the high end of the $19-22 million guidance range, after Q2 missed its own range. The 104.2% year-over-year earnings decline looks alarming, but it mostly reflects an $8.7 million fair-value gain on investments that inflated last year's $9.3 million net income. Sequentially, the loss narrowed sharply, from $3.5 million in Q1 and $3.0 million in Q2 to $0.3 million.
The quality of the beat deserves scrutiny, because the headline masks two businesses moving in opposite directions. Service revenue fell 6.1% to $16.0 million. International data connectivity slid to $10.4 million from $11.9 million on softer Chinese outbound travel. Product sales jumped 30.8% to $5.4 million and did the heavy lifting on the top line, but at a cost. Product gross margin collapsed to 26.8% from 41.0% as memory-chip inflation and mix pushed cost of products sold up 62.4%. Service gross margin was the bright spot, rising to 60.3% from 56.6% a year ago and 59.1% last quarter. Overall gross margin improved sequentially for a third straight quarter, to 51.8%, though it remains below last year's 53.6%. On a non-GAAP basis, the picture is less flattering than GAAP: the adjusted net loss was $0.6 million and adjusted EBITDA was -$0.2 million, versus positive $1.4 million a year earlier. The small GAAP loss was cushioned by a $0.8 million fair-value gain.
That is the central tension. The legacy GlocalMe MeowGo business still drives more than 80% of revenue, and it keeps shrinking. Revenue fell 9.9%, DAU fell 6.4% and MAU fell 10.3%, with no improvement from Q2's rate of erosion. The newer lines are scaling fast off small bases:
- IoT revenue surged 496.5%, accelerating from 392.4% in Q2.
- SIM revenue rose 40.3%.
- GlocalMe Life revenue rose 189.9%, reversing a Q2 decline.
- PetPhone revenue rose 285%.
Combined, those four lines still contribute only about $4 million per quarter. Those new lines drove total DAU growth to 22.4% from 13.3% in Q2. That acceleration reflects a growing installed base, not yet meaningful revenue.
The call preserved a credible near-term story. Management's tone shifted from defensive to describing a "meaningful turning point," and Q4 revenue was guided to $22.5-25.5 million, or 1.8% to 15.4% growth. Other operational positives:
- Operating cash flow turned positive at $1.0 million, after outflows of $8.7 million in Q1 and $3.0 million in Q2.
- 4G/5G CPE products ramped strongly after validation.
- PetPhone gained European telecom retail placement and entry into three Chinese carriers' procurement catalogs.
- Roughly 30 positions were cut.
- A share repurchase program was announced.
The full-year guidance picture needs care, because the sources conflict. The press release narrows FY2026 revenue to $79-82 million from $75-85 million, which is consistent with nine-month revenue of $56.5 million plus the Q4 range. The call analysis characterizes the outlook as a cut to $69-82 million. The release math supports $79-82 million, which leaves the midpoint essentially unchanged. The more meaningful point is that the range sits well below the roughly $85-100 million management floated at the start of the year.
Bears have legitimate ammunition beyond guidance. Nine-month operating cash burn still totals $10.7 million. Shareholders' equity has fallen to $22.8 million from $28.8 million in December, and short-term borrowings rose to $8.1 million. Cash of $26.5 million is adequate but not abundant for a company still spending heavily on PetPhone marketing and R&D. Memory-chip costs and component lead times remain unresolved headwinds just as hardware becomes a bigger share of the mix, with services falling to 74.9% of revenue from 80.6%.
The market setup is more complicated than the surprise implies. Shares entered the report at $0.19, down 64% from the $0.53 open after the August report. They sat about 80% below the 200-day moving average and just 4.5% above a fresh 52-week low of $0.18 set the day before results. Investor sentiment nonetheless swung meaningfully, from -0.47 to +0.16, suggesting expectations had begun to stabilize even as the price kept sliding. The Earnings Whispers trend readings remain mostly negative, with momentum and AVWAP weak, though sequential growth is a clear positive.
The bottom line is that uCloudlink delivered what it failed to deliver in Q2: revenue growth, sequential margin gains, positive cash flow and a near-breakeven quarter. The improvement rests on hardware-heavy, lower-margin growth and new businesses that remain small, while the core MeowGo franchise keeps eroding. Q4 must land within the guided acceleration for the turnaround narrative to gain traction with a stock that has been treated as broken.
Read our earnings preview for uCloudlink Group Inc.: https://www.earningswhispers.com/article/UCL/22958
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 11 hours | |
| 11 hours | |
| 17 hours | |
| Nov-05 | |
| Nov-04 | |
| Sep-04 | |
| Sep-04 | |
| Aug-18 | |
| Aug-18 | |
| Aug-18 | |
| Aug-17 | |
| Aug-11 | |
| Aug-11 | |
| Jun-09 | |
| Jun-04 |
