Riskified's Growth Breakout Raises Guidance Again, But Gross Margin Is Paying The Price
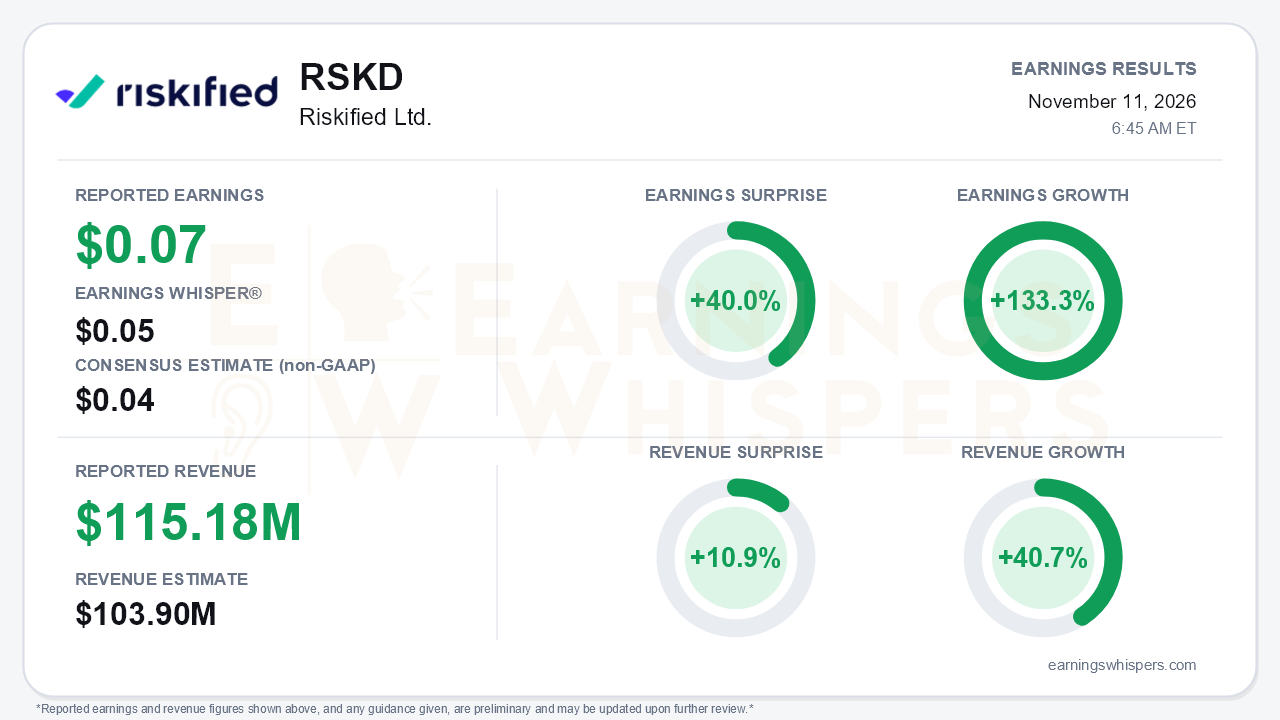
Riskified delivered its strongest quarter since going public. Non-GAAP earnings of $0.07 per share beat the $0.04 consensus by 40.0% and topped the $0.05 Earnings Whisper number, rising 133.3% from a year ago. Revenue of $115.18 million beat consensus by 10.9% and grew 40.7%, the company's first quarter above $100 million. Growth has stepped up sharply all year: 7% in Q1, 22% in Q2 and now 41%, against the roughly 27% management had guided. Management raised its full-year outlook for the third time. The central tension is that revenue is accelerating far faster than gross profit. Riskified is buying growth with margin, and the quarter's quality depends on whether investors read that as temporary onboarding cost or a structural mix shift.
The margin gap is substantial. GAAP gross margin fell to 43% from 50% a year ago, and non-GAAP gross margin fell to 43% from 51%. Gross profit grew only 20%, half the pace of revenue. On the call, management linked the slide to newly onboarded merchants with higher chargebacks. The sequential trend has not stabilized: gross margin was about 58% in Q4 FY25, 46% in Q2 and 43% in Q3. Operating discipline offset much of the damage. Operating expenses fell to 36% of revenue from 42% in Q2 and 45% in Q1, and adjusted EBITDA rose 47% to $8.1 million. The GAAP loss narrowed to $1.3 million, or $(0.01) per share, from $(0.05). Free cash flow reached a record $15.2 million. Per-share results also benefited from a much smaller share base, with basic weighted shares down to 133.9 million from 156.8 million.
The demand picture is unusually concentrated:
* **Digital finance:** billings grew more than 300%, up from about 180% in Q2 and 30% in Q1. The category spans exchanges, remittance, sports betting and event contracts.
* **U.S. billings:** growth accelerated to about 69% from 38% in Q2.
* **Softer areas:** EMEA billings fell 3% against a tough digital-assets comparison. Tickets and travel slowed to about 5% from 23% on online travel agency softness, and fashion and luxury grew just 4%.
* **Broader gains:** multi-product merchants grew about 55%, and eight of the top ten new logos were headquartered outside the U.S.
The breadth is real, but the step change is being driven by one vertical with meaningful regulatory exposure. One data discrepancy is worth noting. The release shows quarterly GMV of $44.6 billion, up 18% year over year, while the call analysis cites 80% GMV growth. Investors should reconcile which figure reflects the underlying volume trend before leaning on it.
Guidance carries the forward story:
* **Revenue:** $427 million to $433 million, up from $400 million to $410 million, and well above the $372 million to $384 million range set at the start of the year.
* **Adjusted EBITDA:** $39 million to $43 million, roughly a 10% margin.
* **Gross profit growth:** 14% to 16%.
* **Free cash flow:** about $45 million.
The outlook still implies Q4 revenue growth of about 29%, a clear deceleration from 41%, with muted seasonality. Management declined to offer a 2027 view.
The new catalysts are strategic rather than near-term financial. Agent Identity Risk Intelligence and the Zendesk partnership extend Riskified into AI-agent fraud and post-checkout customer service. Management said agentic commerce shows higher fraud attempt rates, but checkout adoption remains low, so monetization timing is uncertain. Capital allocation also shifted. Buybacks dropped to about 0.5 million shares from 13.7 million in Q2 as management preserves capital for possible M&A beyond checkout. Cash, deposits and investments stand near $235 million, down from about $298 million at year-end, with no debt. Shekel strength is still adding roughly $2.2 million per quarter to operating expenses; constant-currency non-GAAP opex grew only 5%.
The market had largely anticipated an improving story. Shares rose 39.9% from the $6.06 open after the August report to $8.48 heading into this release. That puts the stock 53.6% above its 200-day moving average. It sits about 8% below the $9.23 52-week high set on October 26 and well off the $5.56 inter-quarter low. Investor sentiment moved from slightly negative (-0.08) to slightly positive (+0.08). That is a meaningful improvement in direction, but hardly euphoric positioning. The Earnings Whispers trend signals are uniformly positive, consistent with the run-up.
The bottom line is that Riskified posted a genuine growth breakout, with accelerating revenue, rising guidance, operating leverage and record cash flow, but the margin structure underneath is changing. Gross margin is falling, growth is concentrating in digital finance, Q4 implies deceleration, and capital is shifting from buybacks toward possible acquisitions. With the stock already up roughly 40% since the last report, the next test is whether gross margin stabilizes as new merchants mature. Bears have legitimate ammunition if it does not.
Read our earnings preview for Riskified Ltd.: https://www.earningswhispers.com/article/RSKD/22815
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 3 hours | |
| 6 hours | |
| 7 hours | |
| 9 hours | |
| 9 hours | |
| Nov-03 | |
| Oct-28 | |
| Oct-08 | |
| Sep-15 | |
| Sep-01 | |
| Aug-17 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 |
