Reed's Narrows Its Loss On 25% Gross Margin, But Shrinking Sales And A Heavily Dilutive Raise Push The Growth Story Into 2027
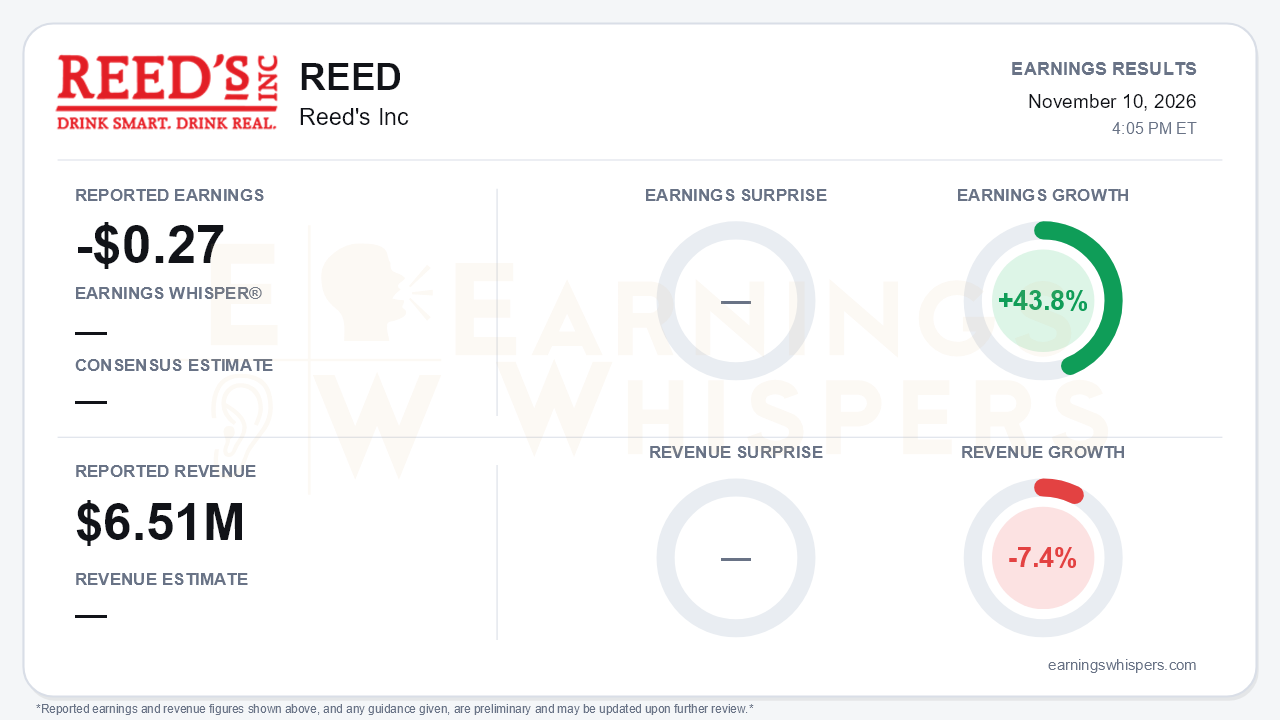
Reed's delivered another quarter of cost and margin repair, but the top line moved the wrong way again. The ginger-beverage maker reported a third-quarter loss of $0.27 per share, a 43.8% year-over-year improvement in per-share earnings from a $0.48 loss. Revenue fell 7.4% to $6.51 million. No consensus estimate was available, so there is no beat or miss to measure. The central tension is that Reed's is becoming a leaner business before it has shown it can become a growing one. The cash needed to bridge that gap came at a steep cost to existing shareholders.
The quality of the earnings improvement deserves some scrutiny. Gross margin expanded to 25% from 17% a year ago, and gross profit rose 34% to $1.6 million. The gains came from lower promotional allowances and a drop in cost of goods to $13.26 per case from $13.73. Inventory write-offs also fell to $83,000 from $114,000. SG&A dropped 15% year over year to $3.6 million and 24% sequentially. Net loss narrowed to $3.2 million from $4.0 million.
The per-share improvement looks stronger than the dollar improvement, however. Weighted shares rose to 11.8 million from 8.2 million, so the larger share base flattered the EPS comparison. Cash used in operations improved sharply to $0.3 million from $2.8 million a year earlier. Part of that conservation came from the balance sheet: accounts payable nearly doubled to $6.8 million from $3.5 million at year-end. Meanwhile, cash fell to $2.1 million and stockholders' equity swung to a $4.7 million deficit.
The call made clear that the revenue problem is not solved. Net sales of $6.5 million were down 13% from $7.5 million in the second quarter, erasing that quarter's 5% sequential gain. Management blamed lower volumes with recurring national customers. Promised inflections keep slipping:
- A year ago, management pointed to accelerated organic growth in 2026.
- Last quarter's framing said results would look very different by the fourth quarter of 2026.
- The timeline now stretches into 2027.
The Asia growth initiative, heavily promoted in earlier calls, has been scaled back. Delivery cost per case also rose to $2.69 from $2.54 in the second quarter, a small reversal in an otherwise improving cost picture. Management guided fourth-quarter gross margin to only modest sequential improvement. It did tighten its mid-30s gross margin target to a timeline of around the second quarter of 2027.
There are credible forward catalysts, though most are back-end loaded:
- **Distribution:** Reed's added more than 3,000 net new doors year over year and now sits at an estimated 32,000 to 35,000.
- **Regained accounts:** Distribution was regained with several national and regional retailers, with product expected back on shelf in the first half of 2027.
- **New product:** Management teased an undisclosed "game-changing" product in a larger category, headed for a controlled market test in early 2027.
- **Marketing:** The company plans a step-up in digital and influencer marketing next year.
- **Tone:** Management's framing shifted from stabilizing the business to rebuilding into a growth company.
Bears still have legitimate ammunition. The innovation is unproven and sits outside the core ginger franchise. Leadership remains interim. The refinanced $9.25 million senior loan now matures in June 2027, with only an optional three-month extension.
The financing is the most consequential development for shareholders. The $10.0 million private placement closed November 9 and satisfied the equity requirement under the amended credit agreement. That removes the near-term liquidity overhang that a $2.1 million cash balance implied. But the deal issued 17.4 million new shares, more than the 11.9 million outstanding at quarter end. That more than doubles the share count at an implied price of roughly $0.57 per share. Future per-share comparisons will be distorted, and any operating recovery will be spread across a far larger base.
Investor sentiment data and a current share price were not available. The context that is available points to a stock the market has already heavily discounted. Shares opened at $0.87 after the second-quarter report, less than half the $1.86 200-day moving average. The placement price sits well below even that level.
The bottom line is that Reed's is executing on the parts of the turnaround it can directly control: margins, overhead, freight efficiency and cash burn. It has also bought itself time with the refinancing and fresh equity. What it has not delivered is the revenue growth that management has repeatedly promised, and the deadline has moved again into 2027. Until regained accounts and new doors show up in sequential sales, the margin story improves the quality of a shrinking business rather than proving a growing one. Shareholders funding that wait now own a much smaller slice of the outcome.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-10 | |
| Oct-29 | |
| Oct-28 | |
| Oct-21 | |
| Sep-30 | |
| Aug-14 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Aug-11 | |
| Jul-29 | |
| Jun-03 | |
| May-18 | |
| May-13 |
