Azenta's 33% Adjusted EPS Jump Flatters A Flat Quarter, But The FY27 Outlook Raises The Stakes
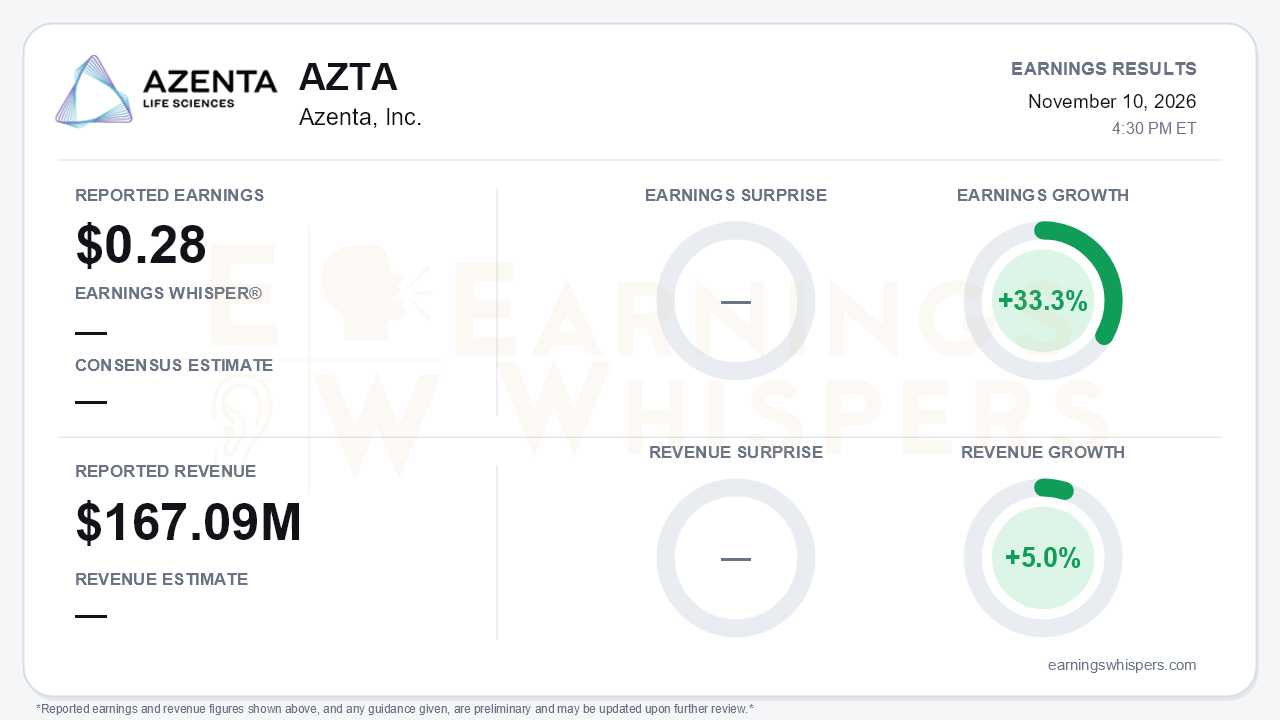
Azenta (NASDAQ: AZTA) reported fiscal fourth-quarter adjusted earnings of $0.28 per share on revenue of $167.09 million. Earnings grew 33.3% year over year and revenue rose 5.0%. No consensus estimate or whisper number was available. The headline marks a sharp turn from a year in which full-year adjusted EPS slipped to $0.48 from $0.51, and a big step up from $0.16 in the June quarter. The quality of the beat deserves scrutiny, though. The forward story is stronger than the quarter's underlying earnings power, and that is the central tension.
Several factors flattered the EPS gain. Azenta's adjusted EPS does not strip out stock-based compensation, and the quarter included a reversal of expense tied to the former CEO's unvested awards. That reversal produced a $2.4 million pre-tax credit, against a $3.9 million charge a year earlier. Buybacks also cut the diluted share count to 43.5 million from 46.0 million. On the company's own adjusted-excluding-stock-comp measure, EPS fell to $0.24 from $0.28. Adjusted EBITDA, which neutralizes the stock-comp swing, declined 7% to $19.4 million, and the margin compressed 140 basis points to 11.6%.
The top line was also less robust than the 5% headline suggests. The UK Biocentre acquisition contributed 3 points, leaving organic growth at just 2%. GAAP diluted EPS from continuing operations fell to $0.14 from $1.12, but that comparison is distorted by a one-time $45.6 million tax benefit in the prior-year quarter.
Beneath the headline, the two segments moved in opposite directions on margin and growth.
- **Sample Management Solutions** grew 4% organically, led by repository services and consumables. Its adjusted gross margin slipped 40 basis points to 48.9%, however, as Automated Stores quality remediation (roughly $6 million in FY26) and weak fixed-cost absorption weighed.
- **Multiomics** was flat as reported and down 1% organically. Sanger sequencing continued to erode, and next-generation sequencing (NGS) fell after about $3 million of orders were pulled into the June quarter.
The segment trends look better on a half-year basis. Multiomics organic growth swung from roughly -1% in the first half to about +4% in the second, and its adjusted gross margin expanded 150 basis points to 45.1%. Full-year revenue of $622 million topped management's own $613-618 million range, and organic growth of 2% beat the flat-to-1% guide. That is a meaningful recovery from the spring, when the outlook had been cut.
The forward catalysts are the bigger story.
- **Guidance:** Management guided fiscal 2027 revenue to $648-660 million, with 3-5% organic growth and 200-250 basis points of adjusted EBITDA margin expansion. That expansion absorbs about 100 basis points of dilution from the new gene-synthesis deals. Off FY26's 9.4% margin, the guide implies a full-year margin roughly in line with the 11.4%-11.6% run rate of the past two quarters.
- **Gene-synthesis deals:** These are the SynPlexity acquisition ($15 million plus up to $10 million contingent) and an exclusive Elegen license. The Elegen agreement could require $32-71 million of total capital deployment. Management is positioning the GENEWIZ business for AI-driven drug discovery demand, though fiscal 2027 is framed primarily as an integration and scale-up year. The high end of the revenue range depends on these deals.
- **Supporting factors:** An October Multiomics restructuring adds about $11 million of annualized savings on top of $7 million from earlier actions. Improved Automated Stores bookings give visibility into a return to modest growth in that unit.
Bears have legitimate ammunition. CEO John Marotta departed in August, and interim chief Martin Madaus declined to reaffirm the fiscal 2029 long-range plan, including the 18-20% margin target reiterated just one quarter earlier. Cash results also fell short.
- **Free cash flow:** FY26 free cash flow of $27 million missed the targeted 10-15% growth, and first-quarter FY27 free cash flow is expected to be negative.
- **Adjusted EBITDA:** Full-year adjusted EBITDA of $58.3 million fell below the $59-62 million range given on the third-quarter call. Management characterized the result as within its latest guidance, a discrepancy investors should note.
- **Near-term growth:** The first-quarter organic growth guide of 3-4% leaves little cushion against the full-year range.
On capital returns, the company stepped up repurchases to $68 million in the fourth quarter ($118 million for the year). It retains $132 million of authorization and $506 million in cash and securities.
Market context is thin for this report. Current sentiment and price readings were unavailable. The shares opened at $30.99 after the August report, above a 200-day moving average now at $28.37. How the stock trades relative to that level will show whether investors accept the FY27 acceleration story or price in leadership and execution risk.
The bottom line is that Azenta's 33% adjusted EPS increase overstates the quarter's earnings power. EBITDA declined, organic growth was 2%, and the stock-comp reversal and buybacks did much of the work. Still, the second-half recovery in Multiomics, firmer bookings and a credible-looking FY27 margin path give the company a real platform. Execution now rests with an interim CEO, two early-stage acquisitions and a cash-flow record that needs to improve.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 2 hours | |
| Nov-10 | |
| Oct-30 | |
| Oct-28 | |
| Sep-04 | |
| Aug-24 | |
| Aug-05 | |
| Aug-04 | |
| Aug-04 | |
| Jul-22 | |
| Jul-08 | |
| May-21 | |
| May-05 | |
| Apr-29 | |
| Apr-07 |
