Eastern Company's Third Quarter Delivers The Long-Promised Volume Inflection, But Flat Backlog And A Cash Drain Temper The Story
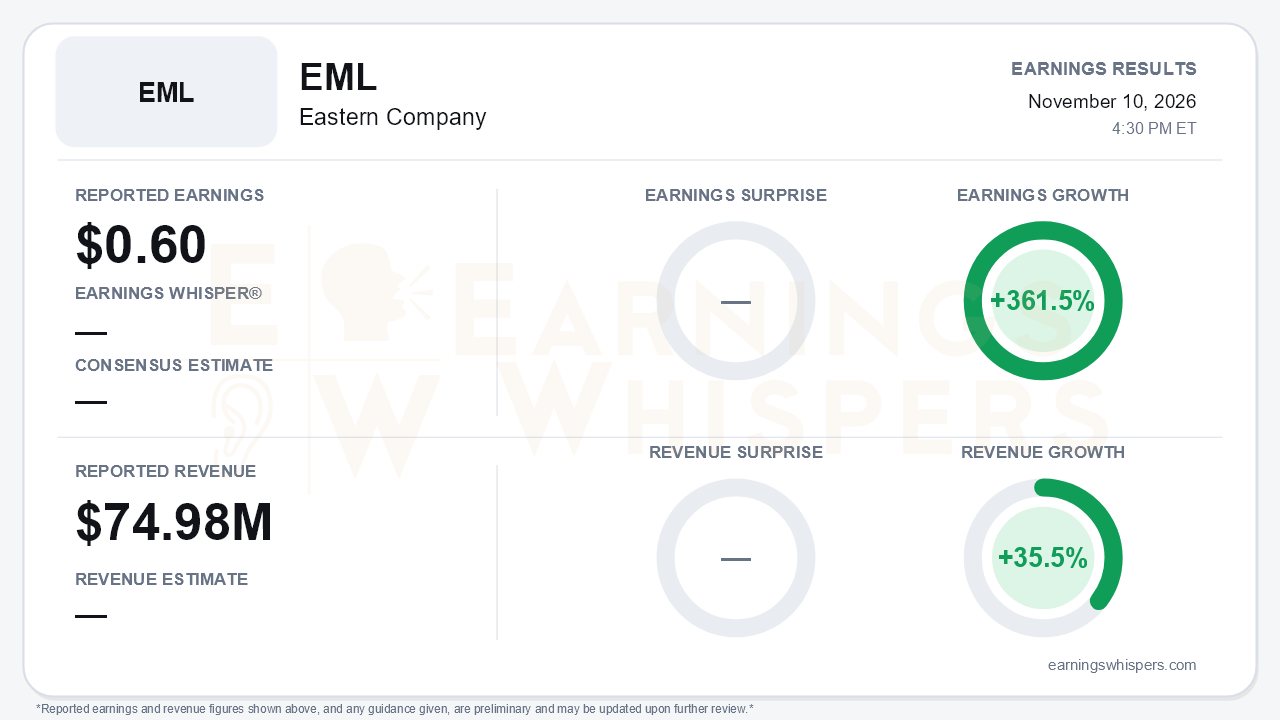
Eastern Company (NASDAQ: EML) delivered the quarter it had been promising for most of the past year. Adjusted earnings were $0.60 per share, up 361.5% from $0.13 a year ago, on revenue of $74.98 million, up 35.5%. GAAP earnings from continuing operations were $0.57 per diluted share versus $0.10, so this was not a non-GAAP story. No consensus estimate was available, so the quarter is best judged against its own trajectory. On that basis it is a sharp turn. Revenue had declined 13.7%, 6% and 12% year over year in the three prior quarters before jumping 36% in the third quarter. Management said net sales, gross margin and operating margin all reached five-quarter highs.
The beat holds up well under scrutiny. Of the roughly $19.6 million year-over-year sales increase, $5.4 million came from the newly acquired Sungear and Crown Precision aerospace and defense businesses. The rest was organic:
- truck mirror assemblies added $7.4 million;
- returnable transport packaging added $5.7 million;
- latch and handle assemblies added $1.1 million.
Gross margin rose to 23.9% from 22.3% a year ago and from 20.6% in the second quarter. Operating margin more than doubled to 7.4%. Adjusted EBITDA reached $7.6 million (10.2% of sales), up from $3.4 million in the second quarter. Selling and administrative expenses rose 16.9%, mostly on higher incentive compensation, but fell to 15.0% of sales from 17.4%. Tariff costs dropped to $2.3 million from $4.0 million a year earlier. One caution: the year-to-date picture remains weak. Nine-month adjusted EPS of $0.88 still trails last year's $1.06, and the GAAP nine-month figure of $1.61 is inflated by a $6.5 million non-cash bargain purchase gain on the acquisitions.
The call showed broad organic momentum. Existing products grew 14.2%, and new products added 2.3% as Eberhard programs won 12 to 24 months ago entered production. Management said the margin problem in Big Three returnable packaging, flagged in the first quarter, is fully behind the company. Management's tone also shifted noticeably, from 'cautiously optimistic' earlier in the year to declaring that 'the volume we said would return has returned.' Backlog stood at $126.1 million, up 70% from a year ago, and management expects it to convert over two to three quarters. The aerospace and defense acquisitions hit the top of the $5-6 million quarterly run-rate given last quarter, although they have not yet contributed much to profit.
The weaker details are the central tension. Backlog was flat sequentially after jumping 54% in the second quarter, as order intake for Velvac truck mirrors normalized, though backlog edged higher in October. Cash and the balance sheet also weakened:
- third-quarter operating cash flow was roughly -$3.2 million;
- cash fell to $7.9 million from $15.1 million at the end of the second quarter;
- receivables have climbed to $42.5 million from $30.1 million at year-end;
- payables also swelled, flattering nine-month operating cash flow of $8.9 million;
- no shares were repurchased during the quarter.
Long-term debt did fall to $39.7 million from $41.7 million. The forward-looking risks are concrete: input and logistics costs are rising, with a lag before pricing catches up. Truck build rates could moderate in 2027, and the usual fourth- and first-quarter seasonal softness is returning. No formal guidance was issued.
The catalyst list is credible but staggered. Repricing of unfavorable Sungear and Crown contracts, along with long-term agreements with key defense customers, is expected to make meaningful progress over the next three to six months. That is the clearest path to making the acquisitions profitable. A heavy automotive launch calendar supports packaging demand, and the Class 8 fleet replacement cycle supports mirror demand. Next-generation fighter work at the aerospace businesses is real but long-dated, with production around 2035.
Market context is thin for this report, with no current sentiment or price data supplied. Shares opened at $24.74 after the prior report, above a 200-day moving average now at $22.96. Investors therefore came into this quarter giving the recovery some credit, but it is unclear how the stock has traded since.
The bottom line is that Eastern produced a genuine operating inflection, driven mostly by organic volume and better gross margin rather than acquisition math or accounting adjustments. The harder questions now concern sustainability. A flat sequential backlog, a working-capital drain, cost inflation with a pricing lag, and seasonal headwinds all arrive just as the company sets a much higher bar. Converting the $126 million backlog while protecting margin, and making the defense acquisitions profitable, will determine whether this quarter proves to be a new baseline or a peak.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-11 | |
| Nov-10 | |
| Nov-10 | |
| Nov-04 | |
| Oct-23 | |
| Sep-04 | |
| Aug-25 | |
| Aug-12 | |
| Aug-11 | |
| Aug-11 | |
| Jul-20 | |
| Jul-16 | |
| Jun-02 | |
| May-13 |
