Anterix Beats On A Narrower-Than-Expected Loss, But Its Spectrum Story Is Outrunning Its Contract Book
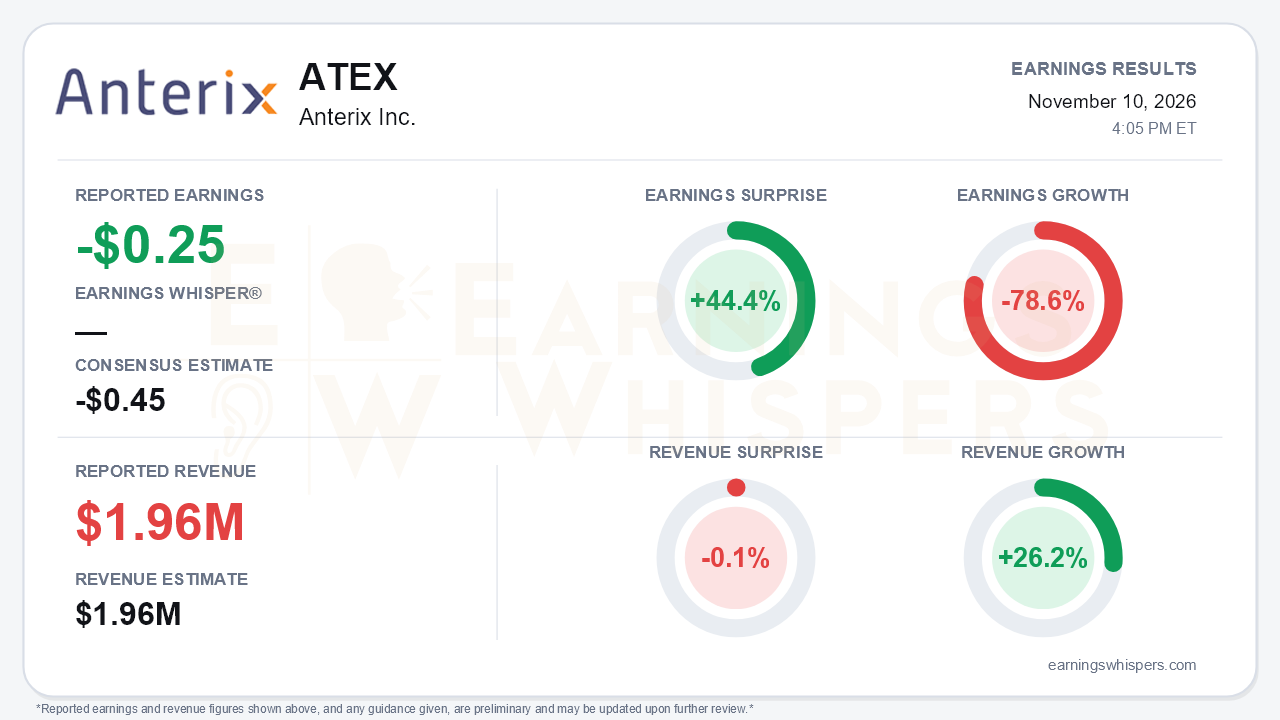
Anterix (NASDAQ: ATEX) reported a fiscal second-quarter loss of $0.25 per share, well ahead of the -$0.45 consensus estimate and a 44.4% earnings surprise. Revenue of $1.96 million matched expectations, missing by 0.1%, and grew 26.2% year over year. The beat is real, but it is not the main story. The quarter widened the gap between a strengthening strategic narrative and a contract book that has stopped growing. Management talked up Apple devices, a satellite-related FCC rulemaking and a fresh low-band spectrum price benchmark. Yet the company announced no new utility contracts for a second straight quarter. That is the central tension.
The quality of the quarter deserves scrutiny. On Earnings Whispers' basis, earnings fell 78.6% year over year. On a GAAP basis, the change was a swing from a $2.86 per-share profit to a $0.25 loss. The prior-year quarter was flattered by a $59.6 million gain on license exchanges and an $11.5 million gain on spectrum sales. This quarter's exchange gain was just $6.1 million, down from roughly $11 million in the June quarter. GAAP operating expenses rose to $13.8 million from $11.9 million, driven by higher G&A, higher sales and support costs, and $4.1 million of stock compensation. Management characterized underlying operating costs as flat at about $9.4 million versus $9.5 million. Spectrum revenue has been stuck near $2 million a quarter for three straight quarters. The year-over-year growth rate reflects the timing of past contract recognition rather than new commercial traction.
Cash is the clearest pressure point. Operating cash flow was negative $6.1 million, and the company spent another $5.4 million on spectrum clearing. Cash and equivalents fell to $107.5 million from $116.0 million at the end of June, and June's balance had been lifted by about $20 million of option exercises. Anterix carries no debt. Contracted proceeds outstanding fell to $33.1 million from roughly $50 million at the end of fiscal 2026. Only about $9.6 million is expected during the rest of fiscal 2027, slightly below the roughly $10 million cited a quarter ago. The renewed $250 million buyback authorization, running through September 2029, sounds aggressive. But no shares were repurchased despite management's undervaluation messaging, and the company says it is prioritizing liquidity. Analysts asked whether a blackout or strategic process explained the inactivity.
The call preserved a credible, and arguably improving, strategic story. The active utility pipeline grew to 16 opportunities from about 12 last quarter. At least half are late-stage, with deal sizes in the seven-to-nine-digit range. The iPhone 18 Pro and iPhone Duo are the first iPhones to run on private LTE networks using Anterix's 900 MHz Band 106, and several existing customers are trialing them. The FCC's October 29 proposed rulemaking would consider adding 900 MHz to the Supplemental Coverage from Space bands. Management also pointed to SpaceX's reported $8 billion purchase of an 800 MHz portfolio at roughly $1.70 per MHz-pop, versus Anterix's own average of about $1.40. It described Anterix as the last remaining nationwide licensed low-band asset, with about 85% of its spectrum still available. Notably, management now describes strategic counterparties in the plural, including satellite and direct-to-device players. The tone was the most confident of the past four calls.
Bears have legitimate ammunition, though. Management is pushing utilities to "sharpen their pencil" on in-flight deals to reflect higher spectrum values. That repricing could lengthen decision cycles at exactly the moment the company needs signings to replenish contracted proceeds. Full nationwide clearing costs remain undisclosed, and incumbent negotiations such as Boston are still pending. The satellite opportunity also depends on how the FCC rulemaking ultimately turns out.
Investor sentiment improved meaningfully, moving from a slightly negative -0.08 at the prior report to a positive 0.21. The stock tells a more sober story. Shares have fallen 20.4% since opening at $94.79 after the August report, to $75.47. They still sit about 12.7% above the 200-day moving average of $66.99, so the longer-term uptrend has cooled rather than broken. Earnings Whispers' AVWAP reading remains negative while price trend is neutral. That fits a market that has been taking profits on the strategic narrative while waiting for transactions.
The bottom line is that Anterix delivered a clean beat on a narrower loss, but the earnings line matters far less than deal flow. The strategic optionality looks richer than it did a quarter ago, with Apple support, a possible satellite use case, a higher spectrum price comparable and a broader set of potential counterparties. Meanwhile, revenue is flat, exchange gains are shrinking, cash is drifting lower and utility signings have stalled for two quarters. Until the larger pipeline converts into contracts at management's higher pricing, or a strategic transaction materializes, the gap between narrative and numbers will remain the defining issue.
Read our earnings preview for Anterix Inc.: https://www.earningswhispers.com/article/ATEX/22721
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-23 | |
| Oct-09 | |
| Sep-21 | |
| Aug-12 | |
| Aug-11 | |
| Aug-11 | |
| Aug-11 | |
| Jul-29 | |
| Jul-22 | |
| Jul-20 |
