Stran Breaks Even As Margins Jump, But Shrinking Quarterly Profits And A Tariff Refund Temper The Rebound
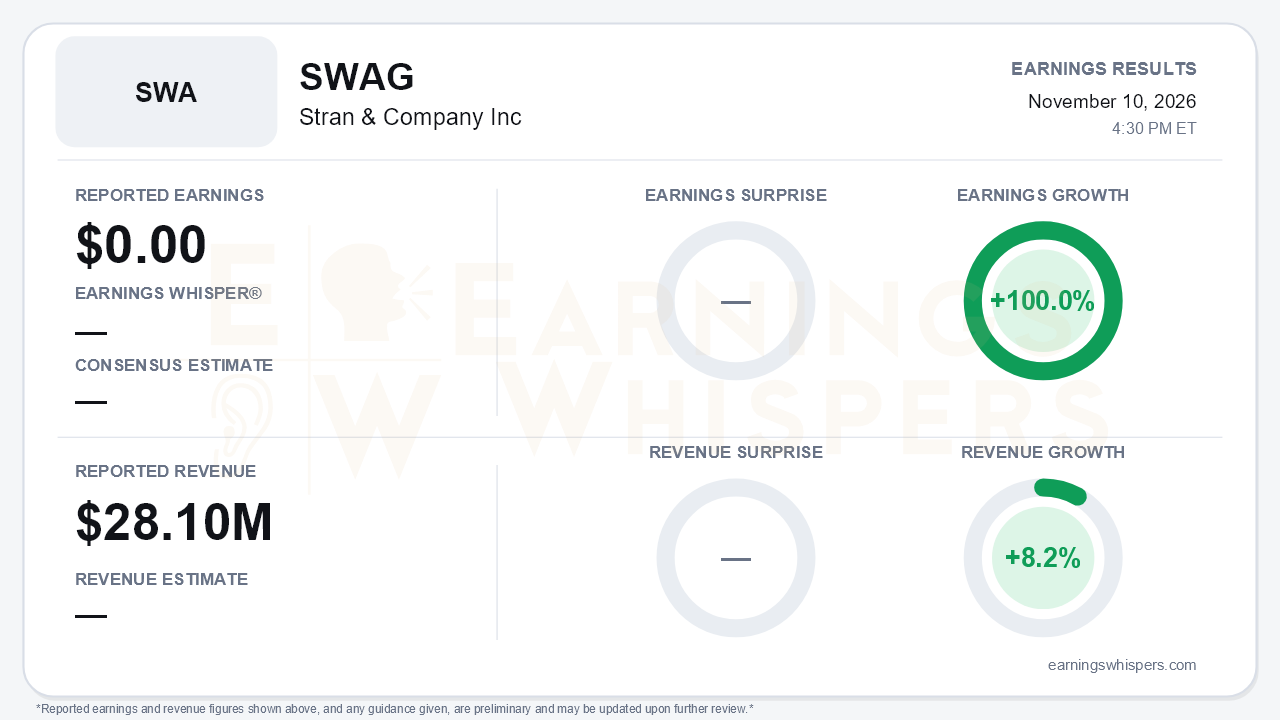
Stran & Company (NASDAQ: SWAG) reported breakeven results for the September quarter, with EPS of $0.00 on revenue of $28.1 million. Revenue rose 8.2% year over year, and Earnings Whispers calculates earnings growth of 100.0% against last year's $0.07 per-share loss. In plain terms, Stran went from a $1.2 million net loss to net income of about $35,000. No consensus estimate or Earnings Whisper was available, so the quarter has to be judged on its own trajectory. That trajectory is less flattering than the year-over-year comparison suggests. Revenue growth reaccelerated sharply from 2.4% in the June quarter, and gross margin jumped. But profits kept shrinking sequentially for a third straight quarter. That is the central tension.
The gross-profit line drove the headline. Gross profit rose 32.4% to $9.4 million, and margin widened roughly 610 basis points to 33.3%, compared with 30.0% in Q2 and 30.9% in Q1. Both segments contributed. The core Stran segment's margin improved to 34.4% from 31.2%, while Stran Loyalty Solutions (SLS) lifted its margin to 31.2% from 18.7%.
The quality of the beat-the-prior-year story deserves scrutiny, however. Approximately $0.2 million of SLS gross profit came from a tariff refund that the company itself warns may not recur. That refund is worth less than a point of consolidated margin, so the underlying improvement is real. But it exceeded the quarter's $74,000 of pretax income.
Below gross profit, the picture is thinner. General and administrative expense rose 7.5% to $9.5 million, slightly exceeding gross profit and leaving a GAAP operating loss of $153,000. Other income also fell to $227,000 from $470,000.
The call analysis frames the deterioration clearly:
- **Net income** slid from $744,000 in Q1 to $309,000 in Q2 to $35,000 in Q3.
- **EBITDA** fell from $1.0 million to $551,000 to $260,000.
- **Opex** climbed to 33.9% of sales from roughly 29% earlier in the year, and corporate costs rose on higher legal and accounting expense.
The operating leverage management touted in Q1 has largely faded.
Segment trends cut both ways. SLS was the clear bright spot. Sales rebounded 15.4% to $9.6 million after declining in Q2, segment gross profit nearly doubled to $3.0 million, and the unit swung to roughly $0.7 million of operating income from a loss. The larger Stran segment is moving the other direction. Growth decelerated from 11.9% in Q1 to 6.9% in Q2 to 4.7% in Q3, with sales of $18.5 million. Because SLS earned about $0.7 million while the company overall lost money at the operating line, the core business and corporate overhead are absorbing more than the loyalty segment generates. Notably, no new customer wins were announced this quarter, after multiple announcements in Q1 and Q2.
The most tangible new catalyst is capital-structure related rather than operational. About 10.1 million public IPO warrants, more than half of the roughly 18.6 million shares outstanding, are lapsing. Roughly 4.3 million expired unexercised on November 9, and the remainder is due by December 10. Their expiry removes a long-standing dilution overhang. Management also highlighted two newer themes:
- **AI agents** across order entry, quoting, artwork proofing, inventory and customer service, framed as a source of future operating leverage.
- **A broader M&A scope**, now extending to complementary marketing-services businesses.
Both are aspirations rather than demonstrated results. The bears have legitimate ammunition here. The company again offered no formal guidance, the call drew no analyst questions, and management's tone moderated from Q1's "genuine inflection point" language to a steadier "profitable growth" narrative.
The balance sheet remains a cushion. Cash and investments totaled $12.6 million, roughly flat for the past two quarters, with no meaningful debt. Nine-month operating cash flow was a positive $1.8 million, compared with $4.8 million used a year earlier. That figure leaned on higher payables and customer prepayments, which offset a $3.2 million inventory build. Buybacks continued but slowed to about $208,000 in Q3 from $272,000 in Q2.
Market context is limited. Shares opened at $2.02 after the August report, against a 200-day moving average now near $1.77. The removal of the warrant overhang is likely to matter as much to the near-term setup as the operating numbers.
The bottom line is that Stran delivered a respectable year-over-year turnaround: faster revenue growth, sharply higher gross margins, and a swing to profitability for both the quarter and the nine months. Beneath that, quarterly earnings have eroded steadily, and the core segment is decelerating. Overhead is now consuming essentially all gross profit, and a non-recurring tariff refund helped keep the quarter in the black. The warrant expiry cleans up the share structure, and SLS looks structurally healthier. Absent guidance or new customer wins, however, investors will need to see opex discipline restore operating leverage before the profitability story regains credibility.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-10 | |
| Nov-04 | |
| Sep-23 | |
| Aug-13 | |
| Aug-11 | |
| Aug-06 | |
| Jul-24 | |
| Jun-29 | |
| Jun-10 | |
| May-28 | |
| May-13 | |
| May-12 | |
| May-08 | |
| Apr-22 |
