Flex LNG Posts Record Third Quarter, But Softer Guidance And Shrinking Backlog Signal Fading Momentum
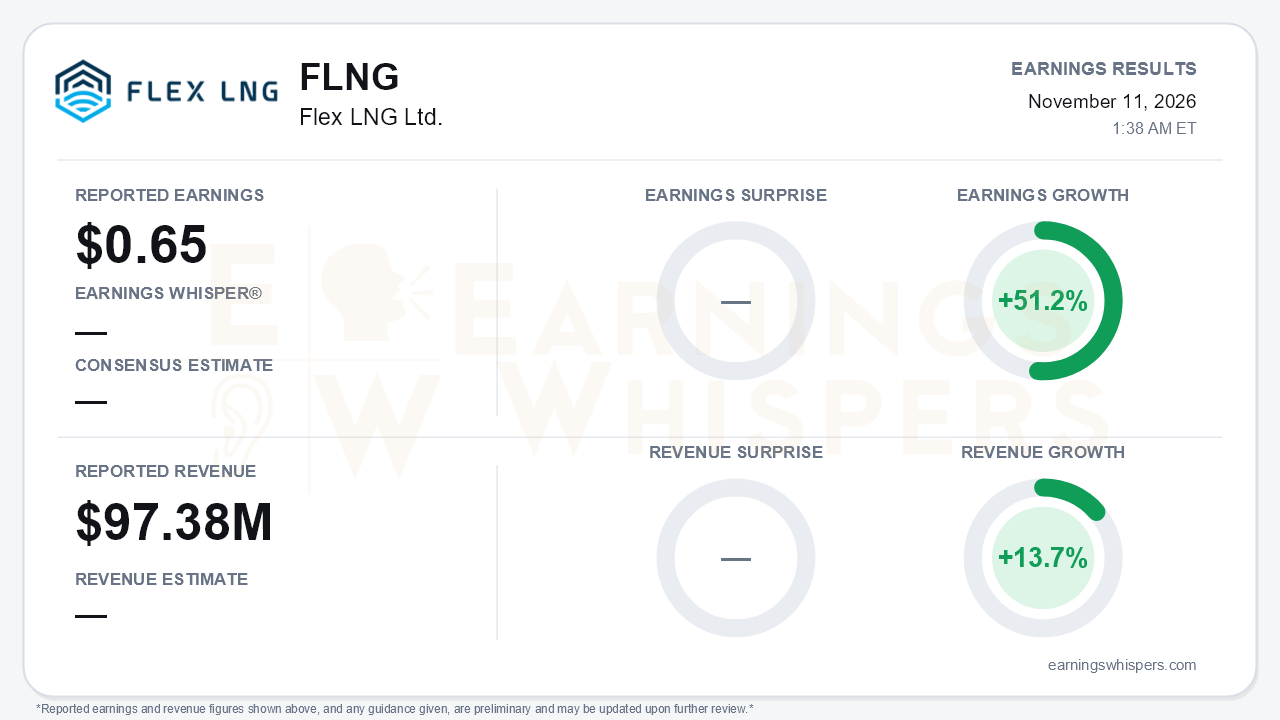
Flex LNG (NYSE: FLNG) reported adjusted earnings of $0.65 per share on revenue of $97.38 million for the September quarter. Adjusted earnings grew 51.2% year over year and revenue rose 13.7%, the company's best third-quarter revenue on record. No consensus estimate or Earnings Whisper number was available, so there is no surprise figure to measure the quarter against. That puts the focus on the trajectory, and the trajectory is the central tension. The year-over-year comparison is strong, but nearly every sequential measure moved lower. Management also used the call to steer full-year expectations toward the mid-to-lower end of its ranges.
The quality of the quarter deserves scrutiny beyond the record label. Revenue fell to $97.4 million from $106.8 million in the second quarter, or $95.2 million excluding EUAs. Fleet-wide TCE slipped to $78,875 per day from $86,119. Adjusted EBITDA declined to $72.1 million from $79.0 million, and adjusted EPS fell to $0.65 from $0.79. GAAP EPS of $0.79 ran well ahead of the adjusted figure, meaning non-operating items flattered the reported number. The call noted the interest rate swap portfolio's value rose to $30 million from $22 million, which is consistent with that gap. Investors should anchor on the $0.65 adjusted figure. Operating cash flow dropped to $56 million from $63 million, and cash fell to $371 million from $397 million. The $0.75 dividend, the 21st straight at that level and roughly $41 million in aggregate, again exceeded adjusted net income of $35.0 million.
The conference call made the deceleration explicit. In the first quarter, management raised guidance by roughly 10%, to revenue of $345–370 million, TCE of $73,000–78,000 per day and EBITDA of $255–280 million. That guidance was reaffirmed in the second quarter. Now the company expects to land at the mid-to-lower end. The formal ranges are unchanged, but the direction is unmistakable. OPEX guidance edged up to $16,200 per day from $16,000, reflecting Middle East-related crew and travel costs. Management's tone shifted as well. Earlier talk of near-record revenue gave way to shipping expectations described as "fairly low" and a "choppy" year ahead. The anticipated seasonal winter tightening has not yet arrived, and Flex Artemis is currently open.
The forward visibility story weakened the most. Minimum firm backlog has slid from 54 years in the first quarter to 51 in the second and 48 now. Management downgraded its backlog-and-visibility dividend factor to orange. Spot exposure rises in 2027 as Flex Ranger returns in the first quarter and the Flex Freedom option remains pending. That exposure comes as heavy newbuild deliveries arrive. The orderbook stands near 290 vessels, with 77 orders placed so far this year, some of them speculative. Bears have legitimate ammunition: a softer spot market, more open tonnage and a thinner contract cushion all hit at once.
The offsets are real but mostly balance-sheet and macro in nature. The new sale-and-leaseback on Flex Enterprise prices at roughly SOFR plus 25 basis points, frees about $34 million of liquidity and addresses one 2029 maturity. Amended leases on Flex Artemis and Flex Amber cut the margin from 250 to 140 basis points and reduce quarterly repayments from $4.3 million to $3.5 million. The hedge ratio rises to 70–75% into mid-2027, and the quarter had no off-hire. On demand, management cited several potential catalysts:
- the EU ban on Russian LNG taking effect January 1;
- EU gas storage at 73%, about a 15-year low;
- roughly 40 mtpa of new US export capacity ramping in the second half of 2027;
- a possible Strait of Hormuz reopening that could pull Qatari ships from the spot market and accelerate steam-vessel scrapping;
- potential El Niño-related Panama constraints.
These are plausible tailwinds, but several are timing-dependent and sit beyond the company's control.
The market context is thin. Investor sentiment readings and a current share price were not available. Shares opened at $32.00 after the August report, above a 200-day moving average now near $29.99. Without a current quote, it is unclear whether the stock has already priced in the softer outlook. The 200-day level is a reasonable reference point for how investors digest the guidance shift.
The bottom line is that Flex LNG delivered a strong year-over-year quarter and continues to sharpen its financing. The underlying earnings trend, however, is decelerating, guidance has drifted from a raise to the lower half of the range, and backlog erosion leaves the company more exposed to a soft spot market heading into a heavy 2027 delivery year. A dividend that now outruns adjusted earnings makes visibility the key variable to watch.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 11 hours | |
| 11 hours | |
| 12 hours | |
| Oct-28 | |
| Aug-24 | |
| Aug-19 | |
| Aug-19 | |
| Aug-19 | |
| Aug-05 | |
| May-13 | |
| May-13 | |
| May-13 | |
| May-05 | |
| Apr-29 |
