Sunrise Realty Trust Misses As A Shrinking Loan Book Offsets A Transformational Merger
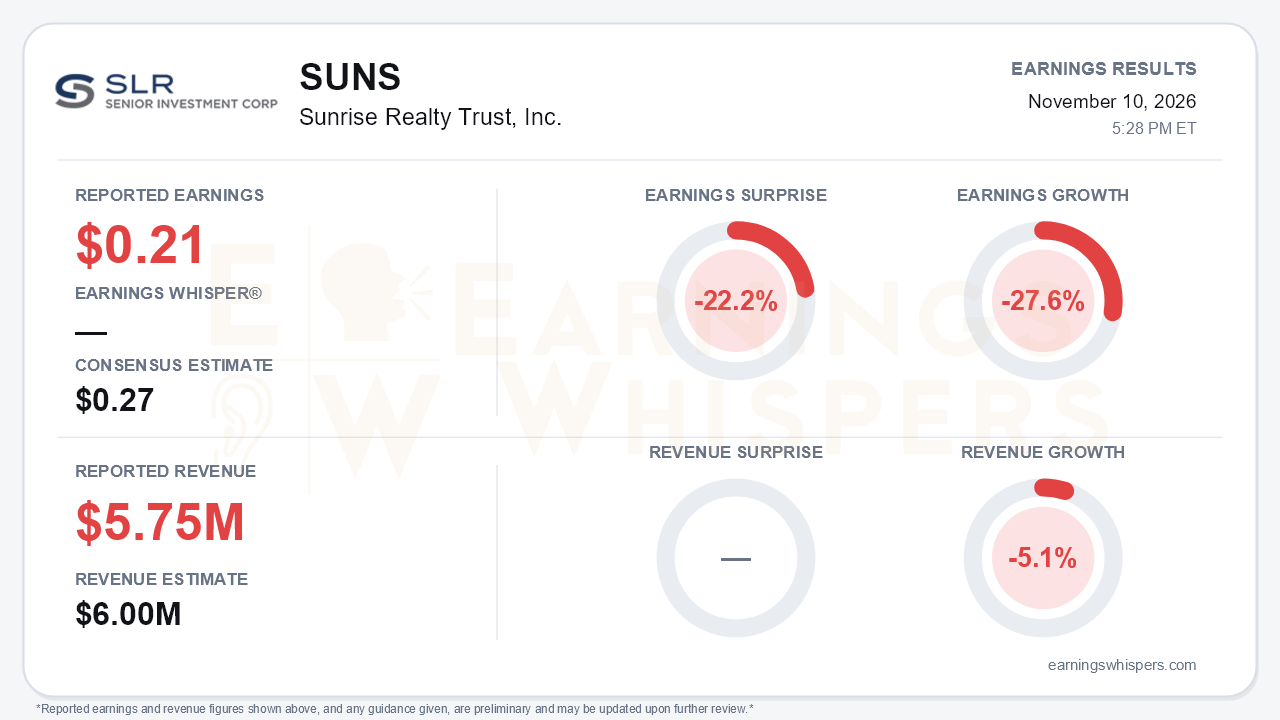
Sunrise Realty Trust (NASDAQ: SUNS) reported third-quarter GAAP earnings of $0.21 per share, missing the $0.27 consensus by 22.2% and falling 27.6% from a year earlier. Revenue of $5.75 million missed the $6.0 million estimate by 4.2% and declined 5.1% year over year. The central tension is that the quarter's most important event, the closing of the Southern Realty Trust (SRT) merger on November 5, happened after the period ended. The quarter itself showed a standalone lender whose earnings power and loan book kept contracting because new lending lagged repayments. Investors are being asked to look past a weak print toward a larger platform that has not yet proven it can put its capital to work.
The quality of the miss deserves scrutiny, but it is not purely a one-time story. Distributable Earnings, the non-GAAP measure the company uses to frame its dividend, came in at $0.24 per share versus $0.31 a year ago. That figure includes about 6 cents of one-time merger expenses. Adding those back puts the quarter roughly in line with the $0.29 reported in Q2, which helps the comparison. It does not reverse a trend that has run from $0.35 in Q1 to $0.29 to $0.24. GAAP net income of $2.9 million also benefited from a small CECL reserve reversal. The dividend math is now tight: the $0.30 quarterly payout exceeded Q3 Distributable Earnings. Nine-month Distributable Earnings of $0.89 slipped just below the $0.90 declared.
The call made clear that the problem is deployment, not credit. In Q3, SUNS funded only $17.1 million of loans against $58.9 million of repayments, largely tied to Panther National. Principal outstanding fell from $298.7 million to $256.9 million, and commitments dropped from $377.4 million to $313.9 million. Portfolio yield eased from 12.4% in Q1 to roughly 12%, while net interest income held at $5.8 million after falling from $7.3 million in Q1. Book value per share drifted lower again, to $13.39 from $13.56 earlier in the year. Leverage sits near 0.5x debt-to-equity against a target of at least 1x. Management acknowledged that deals it expected to close have not, and that roughly $200 million of additional deployment is needed.
The offsetting developments are real. The merger lifts combined equity to roughly $300 million from about $182 million on a standalone basis. Pro forma commitments now total $478.6 million and pro forma principal $393.1 million, on a share count of about 22 million. The amended management agreement improves shareholder economics in three ways:
- the incentive fee falls to 17.5% from 20%;
- the hurdle drops to 7% from 8%;
- a $1 million base-fee waiver applies in 2027.
Management also expects about $1.2 million of G&A savings next year.
The balance sheet is cleaner as well. The Thompson San Antonio REO was sold in October for $41 million at carrying value with $32 million of seller financing, leaving no owned real estate. All loans are current. The pipeline includes $169 million of signed residential term sheets plus a $31 million Texas B-note expected to close shortly. A new $20 million buyback runs through 2027. Management described itself as in "offensive mode," including openness to acquiring distressed mREIT assets or platforms.
Bears still have legitimate ammunition. The September Fed hike and a 10-year Treasury at its highest level since 2002 are pressuring borrowers and slowing deal velocity. Management considers unsecured debt too expensive until it can borrow at a sub-9% all-in cost. A Fort Lauderdale loan maturing in December may need a short extension. Most notably, no post-merger book value, dividend run-rate, or ROE targets were provided, leaving the earnings capacity of the combined company undefined.
The market had already been skeptical. Shares at $6.97 are down 8.0% since the open after the August report and sit about 12% below the 200-day moving average of $7.92. That price is roughly half of stated book value per share. Investor sentiment was essentially unchanged and remains mildly negative, moving from -0.159 to -0.162. Earnings Whispers trend readings lean negative, with AVWAP still weak even as the price trend is neutral.
The bottom line is that SUNS delivered a weak quarter driven by a shrinking, under-levered loan book, not credit deterioration. The merger, fee cuts, and REO exit give it a better structure going forward. Whether that structure translates into earnings now depends on deploying roughly $200 million in a difficult rate environment. Until management shows that pipeline converting and sets out a post-merger dividend run-rate, the discount to book is likely to reflect execution doubt rather than credit fear.
Read our earnings preview for Sunrise Realty Trust, Inc.: https://www.earningswhispers.com/article/SUNS/22769
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-10 | |
| Nov-05 | |
| Nov-03 | |
| Oct-26 | |
| Oct-23 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Oct-13 | |
| Sep-25 | |
| Sep-15 | |
| Aug-12 | |
| Aug-06 | |
| Aug-06 |
