Aytu's Exua Ramp Faces Its First Real Test As Seasonal Spending Squeezes Near-Term Profits
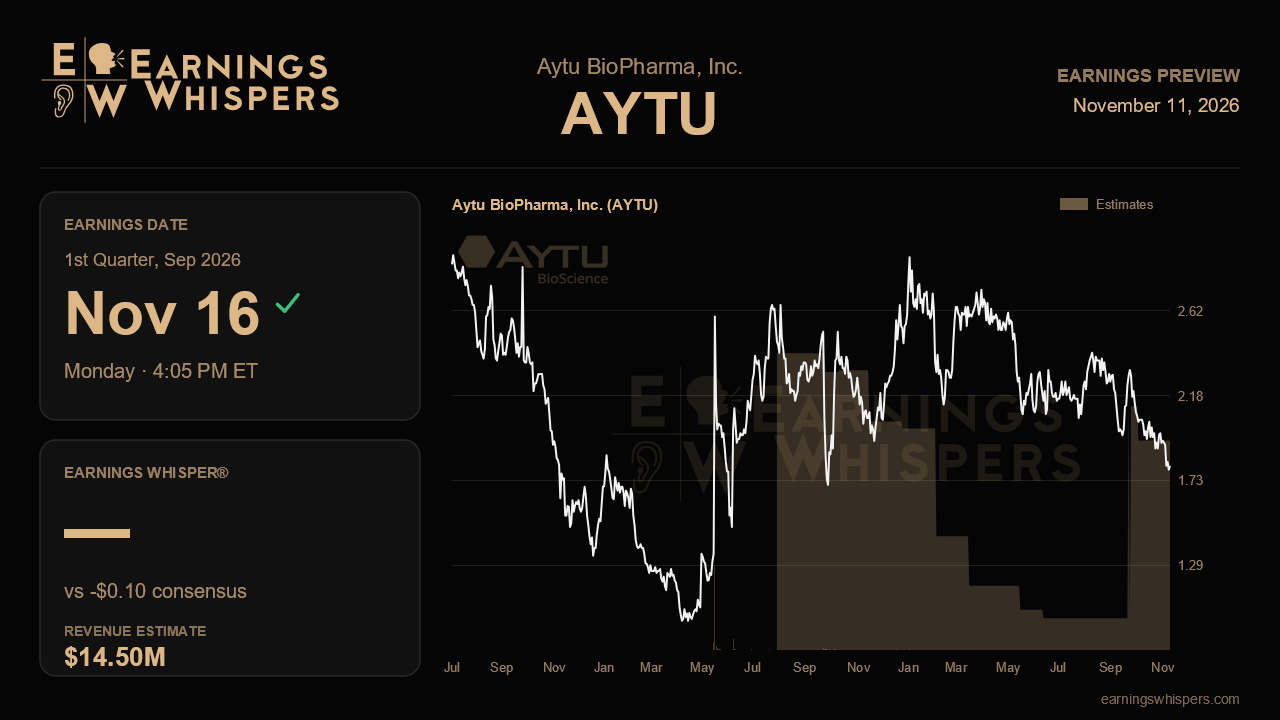
Aytu BioPharma heads into its fiscal first-quarter report with a split personality. Its Exua launch finally produced the proof points management had promised, including accelerating prescriptions and a return to positive adjusted EBITDA. Yet the company also warned that the first half of fiscal 2027 would look worse on profitability. The stock has sided with the warning. Shares are down about 23% since the last report, against a 3% slip in the S&P 500. The September-quarter release, due after the close on November 16, needs to show that the underlying launch kept compounding even as reported earnings take a step back.
The Street has largely accepted management's caution. Consensus calls for a loss of $0.10 per share, wider than the $0.08 loss a year ago and double the $0.05 loss last quarter. Revenue is expected at $14.5 million, up a modest 4.4% from a year earlier but well below the $16.1 million posted in the June quarter. Aytu does not give formal revenue guidance. The setup still lines up with what management described: about $6 million of sales and marketing spend pushed from fiscal 2026 into fiscal 2027, PDUFA fees, and seasonally softer ADHD demand. Gross operating expenses for the year are framed at roughly $49 million to $54 million. A wider loss alone should not surprise anyone. What matters is what the spending is buying.
Exua is the swing factor. Revenue from the product rose to $3.9 million in the June quarter from $2.4 million, and prescriptions more than doubled. Monthly volume climbed steadily through August. The week ending September 4 set an all-time high of 394 prescriptions, a pace well above the July and August run rate. If that weekly level held through September, Exua revenue should rise sequentially again, and anything flat would raise real concern. Prescriber breadth is the other measure. Nearly 1,200 physicians have written the drug, but many have tried it on only one or two patients. A rising prescriptions-per-prescriber figure would be the clearest sign that early trial is turning into habit.
The sales force deserves close attention. Management cut the field team to 32 reps in July before rebuilding to about 42, with plans to push past 45 territories. Its own run-rate illustration put annual Exua revenue at $26 million, $35 million and $50 million-plus at 15, 20 and 30 prescriptions per rep per week. July productivity of about 43 scripts per rep per month works out to roughly 10 a week, so the first rung of that ladder is still ahead. Evidence that new hires are productive quickly, rather than diluting the average, would validate the expansion. Gross-to-net is a related risk. Pricing has run well above launch assumptions, helped by a growing Medicaid and Medicare mix, but management has repeatedly cautioned that this may not last. Margin slippage from the 65% gross margin reached last quarter would hint that it is fading.
The legacy ADHD business is the funding engine. It rebounded sequentially on better pricing but remains down year over year. Any update on whether Teva has launched its Cotempla generic will shape how long that cash flow lasts. Sentiment has improved slightly, with bearishness easing to 23.8% from 28.1%, but the tape tells a gloomier story. At $1.81, the stock sits well below its 200-day moving average of $2.29 and just above its post-earnings low of $1.75. That leaves little cushion if the numbers disappoint.
The central question is straightforward. If Exua prescriptions and revenue kept climbing through a quarter of heavier spending and a rebuilt sales force, the guided profit dip looks like investment rather than erosion, and the selloff looks overdone. If the September spike proves to be a blip, the market's skepticism will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-10 | |
| Sep-23 | |
| Sep-22 | |
| Sep-16 | |
| Jun-01 | |
| May-18 | |
| May-14 | |
| May-13 | |
| May-06 | |
| Feb-04 | |
| Feb-03 | |
| Feb-03 | |
| Feb-03 | |
| Feb-02 |
