Omeros Faces Its First Real Test Of Whether The Yartemlia Launch Can Keep Climbing
Last quarter Omeros delivered the kind of launch inflection that rewrites a company's story: Yartemlia net sales nearly tripled to $28.5 million, the business turned cash-flow positive, and adjusted results flipped to a small profit. The harder question arrives with the September-quarter report on November 16. Can a launch that was still adding accounts at a furious pace show that the early surge was the start of a durable ramp rather than a one-time catch-up in pent-up demand?
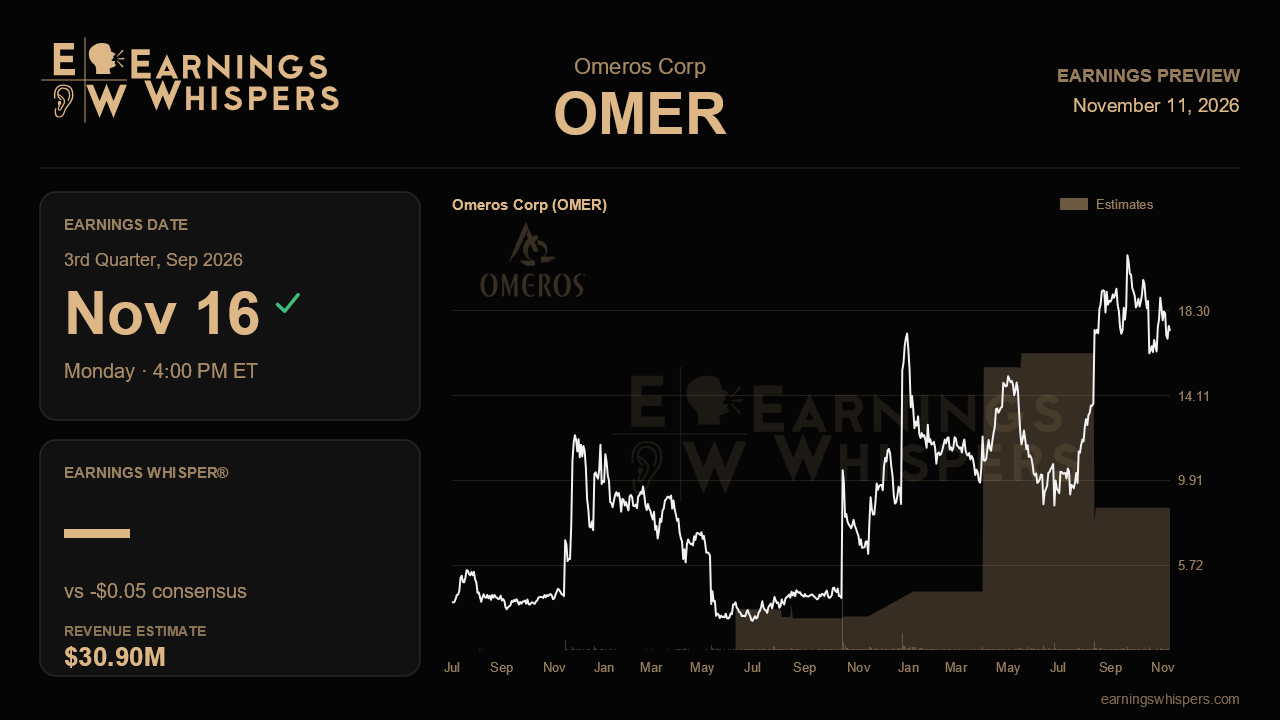
The Street is not asking for another explosion. Consensus calls for revenue of about $30.9 million, only around 8% above the prior quarter's net sales, and a loss of $0.05 per share. That would still be a large improvement from the $0.19 loss a year ago, roughly 74% better, but it marks a step back from last quarter's $0.02 adjusted profit. Some of that slippage is mechanical. Management warned that interest and other income would fall because a one-time $3.3 million inventory reimbursement from Novo will not recur, so a modest loss would not by itself signal a stalled launch. Omeros again declined to offer revenue guidance, saying it needs more experience with prescribing patterns, which leaves analysts building forecasts with little help and makes the revenue line the cleanest scorecard.
The operating details behind that number matter more than the headline. Unique ordering accounts jumped from 30 to 73 in the June quarter, and adults climbed to roughly three quarters of sales, approaching the historical mix the company expects. Continued growth in accounts, and evidence that existing centers are reordering rather than trialing the drug once, would validate management's repeated claim that the company is only scratching the surface of the transplant-associated TMA market. Further gains in formulary approvals beyond the 55% to 60% coverage reached across tracked hospital cohorts would also help, as would signs that residual off-label eculizumab use is fading. A quarter in which sales flatten while accounts stall would challenge the idea that demand is broadening.
Reimbursement is the other piece of the puzzle. The permanent J-code took effect July 1, so this is the first quarter fully under cleaner billing, and commentary on whether it smoothed ordering will be telling. The new technology add-on payment, worth up to $287,000 per course for Medicare patients, only started October 1, so it should show up in the outlook discussion rather than the reported numbers. Investors will also want an update on the European reexamination after the negative CHMP opinion, along with a balance sheet that now reflects the July repurchase of 43% of the 2029 convertible notes, which trims future interest and potential dilution.
Expectations have warmed. Sentiment has improved to about 33% bullish from roughly 13% ahead of the last report, and the stock has gained 3.9% since then while the S&P 500 fell 3.2%. More striking is the re-rating: shares traded between $6.70 and $14.72 in the prior quarter but have held a $15.85 to $21.24 range since, and at $17.30 the stock sits comfortably above its 200-day average of $13.67, though well off its post-earnings peak. That suggests the market has already accepted the launch thesis but has cooled on paying up for perfection.
The central issue is whether Yartemlia's sequential growth, account expansion and reorder behavior confirm a steady commercial ramp heading into the NTAP-boosted fourth quarter. A clean revenue print at or above $30.9 million with rising account counts keeps the turnaround narrative intact; a stall would suggest last quarter's leap captured demand that had simply been waiting for the drug.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-10 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Oct-16 | |
| Sep-22 | |
| Aug-12 | |
| Aug-12 | |
| Aug-12 | |
| Aug-10 | |
| Aug-03 | |
| Aug-03 | |
| Jul-27 |
