IceCure Heads Into Seasonally Soft Q3 Needing Proof That CHOICE Enrollment And US Installs Are Real
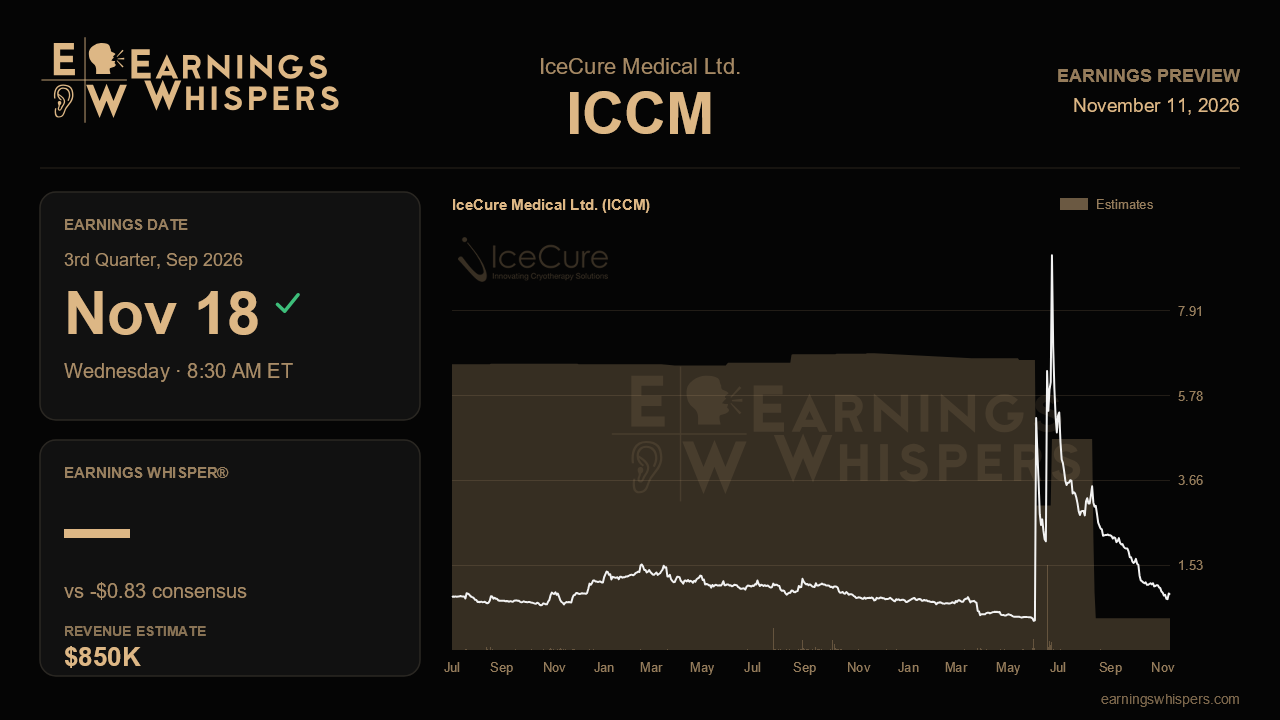
IceCure Medical enters its third-quarter report with a striking disconnect. Three months ago, management described a company crossing from evidence-building into genuine commercial traction, with a growing US install base, better sales mix and a refreshed balance sheet. Since then, the stock has lost roughly 74% of its value while the S&P 500 slipped about 3%. Either the market sees risks the conference call glossed over, or a beaten-down stock is about to be handed a chance to reprice. Tuesday morning's release should help settle which.
The Street is not asking for much on the top line. Consensus calls for revenue of about $850,000, essentially flat with the year-ago quarter and a touch below the roughly $0.9 million booked last quarter. That modest bar is consistent with management's own framing. The company does not issue formal guidance, but it flagged the third quarter as seasonally softer and the fourth as typically strongest. A flat print would therefore not break the story. A meaningful step down, however, would undercut the claim that revenue growth was broadening after first-half sales rose 45%. The expected loss of $0.83 per share compares with a $0.06 loss a year ago and a $3.11 loss last quarter, a sequence where per-share figures have swung wildly. Dollar losses and cash are the more useful yardsticks.
The commercial narrative rests on a few measurable claims. US active commercial sites had climbed above 30 following the October 2025 FDA clearance, up from 19 the quarter before. Continued growth in that count, even in a soft revenue quarter, would support the self-reinforcing adoption cycle management described. The shift toward outright system purchases rather than placements is equally important, because higher-value sales should lift gross margin, which reached 30% in the first half despite a shekel headwind. If margin slips back toward the high 20s, the currency drag may be overwhelming the mix benefit.
The bigger test is execution on promises that have already slipped once. Management previously suggested most of the 30 CHOICE study sites would be identified and onboarding within months; by last quarter only two had signed contracts and no patients had been enrolled. The company said its first patient would be enrolled before September 1, with 80 patients targeted by March 2027. This report is the first chance to confirm that milestone landed and to gauge the pace of site activation. A second deadline also fell inside the quarter: breast cancer cryoablation was on the agenda for the American Medical Association's September meeting, a step toward a CPT code. Confidentiality may limit what management can say, but any clarity matters, since reimbursement benefits would not arrive until around early 2028. Japan deserves attention too, after a firm Terumo submission target softened into talk of constructive engagement.
Spending is the swing factor behind all of it. The first-half net loss widened to $8.8 million as CHOICE costs and currency effects pushed R&D higher, against roughly $12 million in cash after an $8.5 million raise. Investors will want a sober read on runway, since another capital raise at these prices would be painful. Sentiment has improved from uniformly bearish heading into last quarter to only mildly negative now, suggesting fatigue more than optimism. The stock, at $0.79, sits well below its 200-day average of $1.66 and near the bottom of its post-earnings range of $0.65 to $3.40.
Ultimately, the quarter will be judged less on revenue than on credibility. If IceCure shows a rising install base, steady margins, an enrolled CHOICE study and disciplined burn, the improving narrative survives the soft season intact. If enrollment has stalled again or cash is draining faster than expected, the market's harsh verdict since August will look justified.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-11 | |
| Nov-09 | |
| Nov-09 | |
| Oct-27 | |
| Oct-21 | |
| Oct-20 | |
| Oct-13 | |
| Oct-06 | |
| Sep-10 | |
| Aug-24 | |
| Aug-20 | |
| Aug-19 | |
| Aug-13 | |
| Aug-12 |
