Evogene's Cash Runway And Collaboration Count Face A Test As Shares Slide Toward Lows
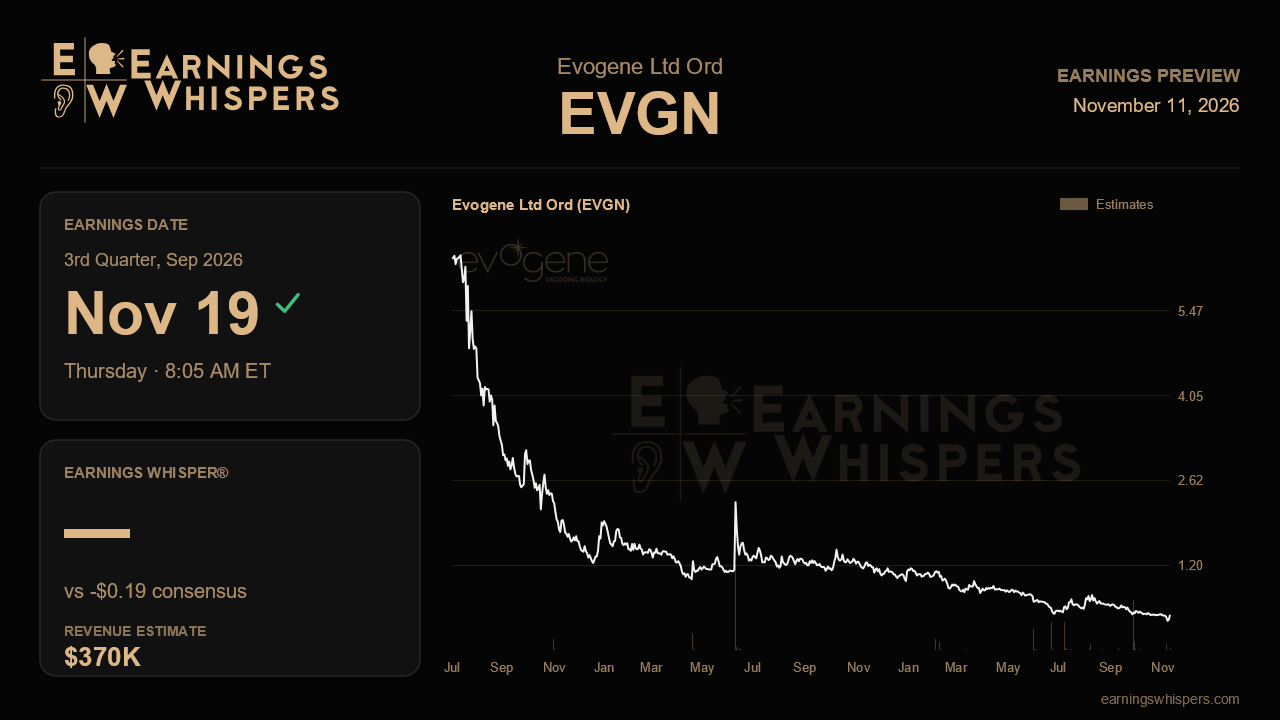
Evogene enters its third-quarter report with a split personality that the market has so far resolved in one direction. Management spent the last call arguing that its AI-driven transformation had moved from story to reality, pointing to a jump in partnerships and a far leaner cost base. Shareholders answered by selling: the stock has fallen about 34% since that report, trailing the S&P 500 by roughly 31 percentage points, and at $0.37 it sits well below its 200-day moving average of $0.64. The report due before the open on November 19 needs to show that improving science can translate into something closer to a self-sustaining business.
The Street's numbers are small and not very revealing on their own. Consensus calls for a loss of $0.19 per share on revenue of about $370 thousand. That revenue figure would be up roughly 19% from the year-ago quarter, but off a base so tiny that the percentage means little. The more interesting wrinkle is the loss estimate. It implies a meaningful improvement from the $0.31 loss a year ago, yet a wider loss than last quarter's $0.13. That gap likely reflects a higher share count from continued at-the-market issuance and the possibility of more non-cash warrant swings, which added about $3.8 million of financial expense in the first half. Per-share figures could be noisy, so operating loss and cash usage are the cleaner gauges.
Management's only formal financial guidance is a 2026 cash burn range of $8.5 million to $9.5 million, which it reaffirmed last quarter and which compares with roughly $20.5 million in 2024. That is the number to hold the company to. Consolidated cash fell from about $13.1 million at the end of March to about $9.3 million at the end of June, and the company leaned on roughly $2.4 million of ATM sales during the third quarter. A September cash balance that, adjusted for those proceeds, shows burn tracking inside the guided range would support the cost discipline narrative. A steeper decline, or signs that dilution is doing more of the heavy lifting than operations, would reinforce the market's skepticism.
On the operating side, the momentum claims are specific enough to check. Disclosed collaborations climbed from one to four to six over three quarters, two partners finished first-stage validation with results that management said beat expectations, and the virtual chemical library expanded to about 110 billion molecules. Validation this quarter would look like additional agreements, partners moving into later stages, and, most importantly, evidence that the R&D reimbursement management said now features in most new discussions is showing up in signed terms or revenue. The Septoria fungicide finishing lead optimization and heading into greenhouse or field work would be another tangible milestone, particularly after the Bayer herbicide program was terminated. A stalled partnership count or vague timelines would undercut the confident tone.
Governance adds a further variable. A dissident group sought to replace the entire board at a contested September election, while board member Leon Recanati made a large personal investment and two new directors were slated to join. Whatever the outcome, this report should clarify who is steering strategy and whether the cost and partnering plan survives intact.
The stock's slide from a prior-quarter range of $0.37 to $0.80 into a post-report range of $0.25 to $0.61 suggests expectations are already depressed. That lowers the bar, but it does not remove it. The central question is whether Evogene can show its partnerships beginning to fund themselves before its shrinking cash pile forces more dilution. Evidence of paying collaborations and burn within guidance would keep the turnaround thesis alive; another quarter of scientific progress without financial follow-through would leave it looking like a race against the balance sheet.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| Nov-05 | |
| Oct-28 | |
| Oct-26 | |
| Oct-20 | |
| Oct-06 | |
| Sep-30 | |
| Aug-31 | |
| Aug-25 | |
| Aug-18 | |
| Aug-18 | |
| Aug-18 | |
| Aug-17 | |
| Aug-17 | |
| Aug-14 |
