DoubleDown Misses On FX-Hit EPS As Revenue Slips, But The $16.25 Buyout Now Defines The Stock
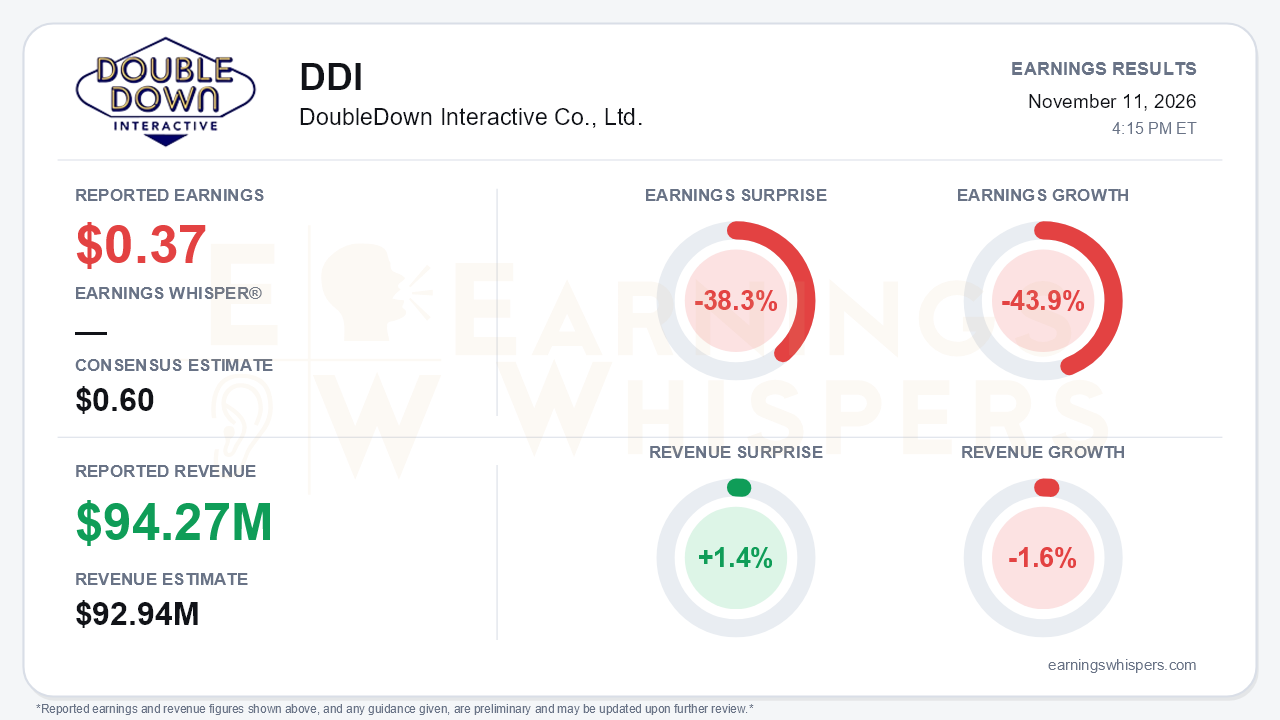
DoubleDown Interactive's third-quarter earnings miss matters less than the buyout announced two days before it. The company earned $0.37 per ADS, 38.3% below the $0.60 consensus and down 43.9% from a year ago. Revenue of $94.27 million beat the $92.94 million consensus by 1.4% but fell 1.6% year over year. On November 9, controlling shareholder DoubleU Games signed a definitive agreement and launched a tender for all ADSs it does not own at $16.25 in cash. That price is up from the $11.25 non-binding proposal disclosed in the spring. The board, acting on a special committee's recommendation, unanimously urged holders to tender. For most public shareholders, the question is no longer what the next few quarters look like. It is whether $16.25 fairly prices a business with strong margins and slowly shrinking revenue.
The EPS miss deserves scrutiny, because it came from below the operating line. Operating profit rose to $37.5 million from $35.0 million. Adjusted EBITDA increased 7.2% to $40.2 million, and its margin widened to 42.7% from 39.1%. The damage came from finance costs and taxes:
- Finance cost swung to a $10.0 million charge from a $1.6 million benefit, mostly from foreign currency losses on dollar-denominated financial assets.
- Finance income fell to $1.8 million from $4.5 million.
- Income tax expense rose to $10.9 million from $8.4 million.
Profit therefore fell to $18.4 million from $32.7 million. It was also well below the $32.9 million earned in the second quarter. Much of the shortfall is non-operating and, in part, unrealized. Even so, the quarter was not uniformly clean. Operating cash flow fell to $23.6 million from $33.4 million on higher tax payments, and general and administrative expense climbed to $16.5 million from $13.0 million.
The operating story is a margin engine running against a shrinking core. Direct-to-consumer revenue reached $44.6 million. That is a record 58% of social casino revenue, up from 52% in Q2, 44% in Q1 and roughly 21% a year ago. The shift away from app-store platform fees cut cost of revenue to $22.2 million from $27.9 million and has lifted adjusted EBITDA margin in every quarter this year. Underneath, however, revenue growth has decelerated sharply now that the WHOW Games acquisition has been lapped. Consolidated growth went from +17% in Q4 2025 to +13%, +11% and now -1.6%. Social casino revenue fell 3.5% to $76.8 million, driven by the legacy DoubleDown titles. The year-over-year gains in ARPDAU and payer conversion mostly reflect WHOW's inclusion rather than organic improvement.
On the call, management sounded more cautious about the outlook:
- It now expects the 2026 social casino market to shrink about 7%, worse than the more-than-5% decline it cited in Q2.
- It acknowledged the company has fewer players than in the past.
- It said further DTC gains will get harder as the mix rises.
That last point matters most, because DTC has been the margin lever. SuprNation's iGaming revenue grew 7.4% to $17.4 million on the Los Vegas brand, but growth has slowed from 78% in Q4 2025, 30% in Q1 and 10% in Q2. Management said the UK tax increase is largely mitigated. Fifth and sixth iGaming brands are planned, along with a simplified mobile lobby, a linked jackpot system and broader use of AI in 2027. No formal guidance was given, and the Q&A was brief.
The market setup is now governed by the deal. Shares closed at $15.70 on November 10, about 3.5% below the offer price. That is up 28.2% since the open after the August report, just off the $15.78 52-week high set on the announcement day, and about 40% above the 200-day moving average. Investor sentiment improved substantially, from -0.55 to -0.28, but remains negative. The Earnings Whispers price and AVWAP trend signals are positive, while sequential growth and momentum are neutral, which fits a stock tied to an offer price rather than to its operating trajectory.
The main risks are the deal terms themselves. The offer requires a minimum tender and a majority-of-the-minority approval, and completion is not assured. If it goes through, holders give up all upside for a fixed cash price. Some minority holders may also note that the company carries about $545 million of net cash, which equals roughly $11 per ADS against a $16.25 bid.
The bottom line is that the EPS miss was largely a currency and tax event layered on top of a genuinely softening top line. DTC-driven margin expansion and cash generation masked declining players and a weaker industry, but they cannot hide them indefinitely. With the stock pinned just below $16.25, the quarter matters mainly as evidence in the debate over the offer price. That evidence is a business with excellent margins and a cash-heavy balance sheet, but with revenue now shrinking and fewer growth levers left.
Read our earnings preview for DoubleDown Interactive Co., Ltd.: https://www.earningswhispers.com/article/DDI/22960
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-11 | |
| Nov-10 | |
| Nov-09 | |
| Nov-05 | |
| Oct-28 | |
| Sep-11 | |
| Aug-12 | |
| Aug-11 | |
| Jul-28 | |
| Jun-01 | |
| May-13 | |
| May-12 | |
| Apr-29 | |
| Apr-28 |
