Alpha Cognition Beats As ZUNVEYL Volume Climbs And Cash Burn Shrinks, But Slower Growth And Payer Delays Temper The Setup
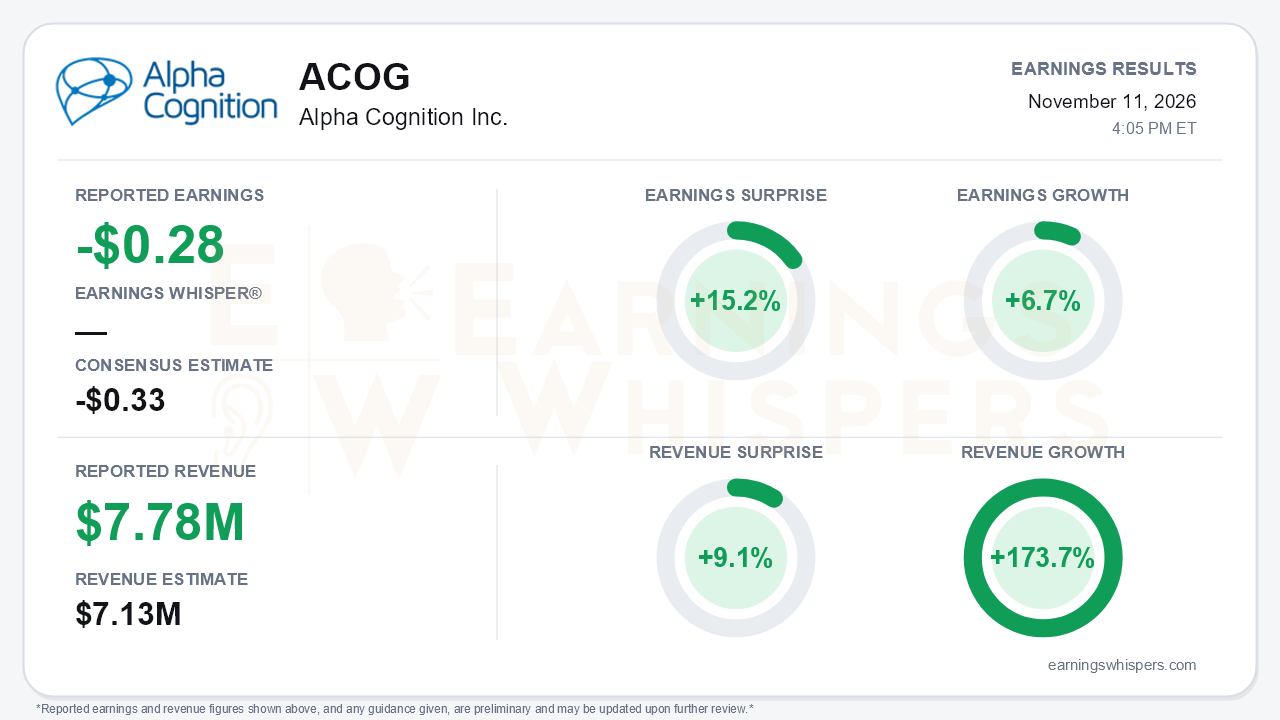
Alpha Cognition (NASDAQ: ACOG) delivered its strongest ZUNVEYL quarter since launch. It reported an adjusted loss of $0.28 per share against a consensus estimate of a $0.33 loss, a 15.2% earnings surprise. Revenue of $7.78 million topped the $7.13 million consensus by 9.1% and grew 173.7% year over year. Earnings improved 6.7% from the year-ago period. The central takeaway is that the commercial engine is working and the operating model is getting leaner. The quarter also showed that sequential growth is moderating, and the external catalysts that were supposed to add the next leg of growth keep slipping.
The quality of the quarter is better than the GAAP bottom line suggests, but investors should understand the gap. GAAP net loss was $7.6 million, or $0.35 per share. That figure includes a roughly $1.5 million non-cash charge from the change in fair value of warrant liabilities, which accounts for most of the difference from the normalized $0.28 figure. The cleaner signal is the operating line. Operating expenses rose only modestly, to $13.7 million from $12.9 million in Q2, while product revenue rose about 30% to $7.75 million, so the operating loss narrowed to $6.4 million from $7.1 million. Gross product margin held near 94%. The headline year-over-year revenue growth also understates product momentum. Product revenue alone grew more than 230%, while licensing revenue fell to a negligible $27,000 from about $507,000 a year earlier.
The call reinforced that growth is volume-driven and broad-based. Management cited net price stable at roughly $650 per bottle, and every key adoption metric improved:
- Bottles dispensed rose about 31% sequentially to 10,896.
- Quarterly prescribers grew about 22%.
- Prescriptions per prescriber climbed to roughly 6.6 from 6.2.
- Repeat-prescriber rates edged up to about 77% to 78%.
- Facilities generating prescriptions rose to roughly 1,400 from 1,095.
- Conversion of called-on prescribers jumped to more than 50% from about 35%, a meaningful efficiency gain for a lean sales force.
Cumulative prescribers passed the original 2,000 full-year goal a quarter early, and the target is now 2,500. The release and call cite slightly different counts (2,410 versus 2,438), but both clear the original goal. Notably, all of this happened without any meaningful change in formulary access. The caveat is trajectory. Sequential revenue growth slowed to about 30% from about 71% in Q2, and incremental quarterly revenue was smaller than in the prior quarter. Management offered no revenue guidance, only the assurance that growth is continuing into Q4.
That payer gap is both the biggest risk and the biggest catalyst. Medicare Part D contracts with two major PBMs cover about 45 million lives, and supported prior authorizations are approved roughly 95% of the time. Effective coverage, however, remains unchanged. Management now expects no formulary wins before year-end and hopes for traction in early 2027, a repeated slip from earlier expectations of Q2 traction and broad Q3 implementation.
The pipeline also took hits:
- A sublingual pharmacokinetic study was inconclusive, so a repeat study begins in January 2027, pushing out the IND.
- On the call, RESOLVE completion was guided to the second half of 2027, even though the press release still cites Q2 2027. Investors should treat the later date as the operative one.
- Asia approvals and a CMS milestone remain without timing visibility.
On the positive side, the CONVERGE real-world data are a genuine commercial tool. About 79% of new-to-therapy ZUNVEYL residents reached a therapeutic dose versus 37% on generics, and polypharmacy declined. That analysis is retrospective and unadjusted, but further dataset updates and publications through 1H27 should help payer dossiers.
The balance sheet improved in practice. Cash fell only $3.6 million to $37.8 million, and that figure was helped by about $1.4 million of option and warrant proceeds. Q2's roughly $12.8 million decline included a royalty buyout. The company carries no debt, reaffirmed 2026 opex guidance of $50 million to $54 million, and reiterated its goal of operating profitability in 2027.
Investor enthusiasm cooled sharply heading into the print. Earnings Whispers sentiment fell from 0.35 to roughly neutral at 0.01. Shares were down 6.5% from the open after the August report. They peaked at a 52-week high of $10.14 on August 24 and slid to $7.98 in late October before recovering to $8.73. The stock still sits about 21% above its 200-day moving average, so the longer-term trend remains intact even after the stock gave back its post-Q2 gains. Short-term momentum readings have turned positive while AVWAP remains negative. That mix fits a stock caught between solid execution and fading near-term catalysts.
The bottom line is that Alpha Cognition delivered a clean commercial beat. Rising prescriber productivity, stable pricing and sharply lower cash burn make the 2027 profitability target more credible. Bears still have legitimate ammunition: sequential growth is decelerating, there is no revenue guidance, payer access keeps slipping, and pipeline timelines moved out. Formulary implementation in early 2027 is now the swing factor for whether growth reaccelerates or merely continues.
Read our earnings preview for Alpha Cognition Inc.: https://www.earningswhispers.com/article/ACOG/22959
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-11 | |
| Nov-09 | |
| Nov-06 | |
| Nov-05 | |
| Nov-02 | |
| Oct-13 | |
| Oct-06 | |
| Oct-02 | |
| Oct-01 | |
| Sep-09 | |
| Sep-01 | |
| Aug-17 | |
| Aug-13 | |
| Aug-03 |
