Walmart's Guided Profit Dip Meets A Rallied Stock And An 11,000-Rollback Price Push
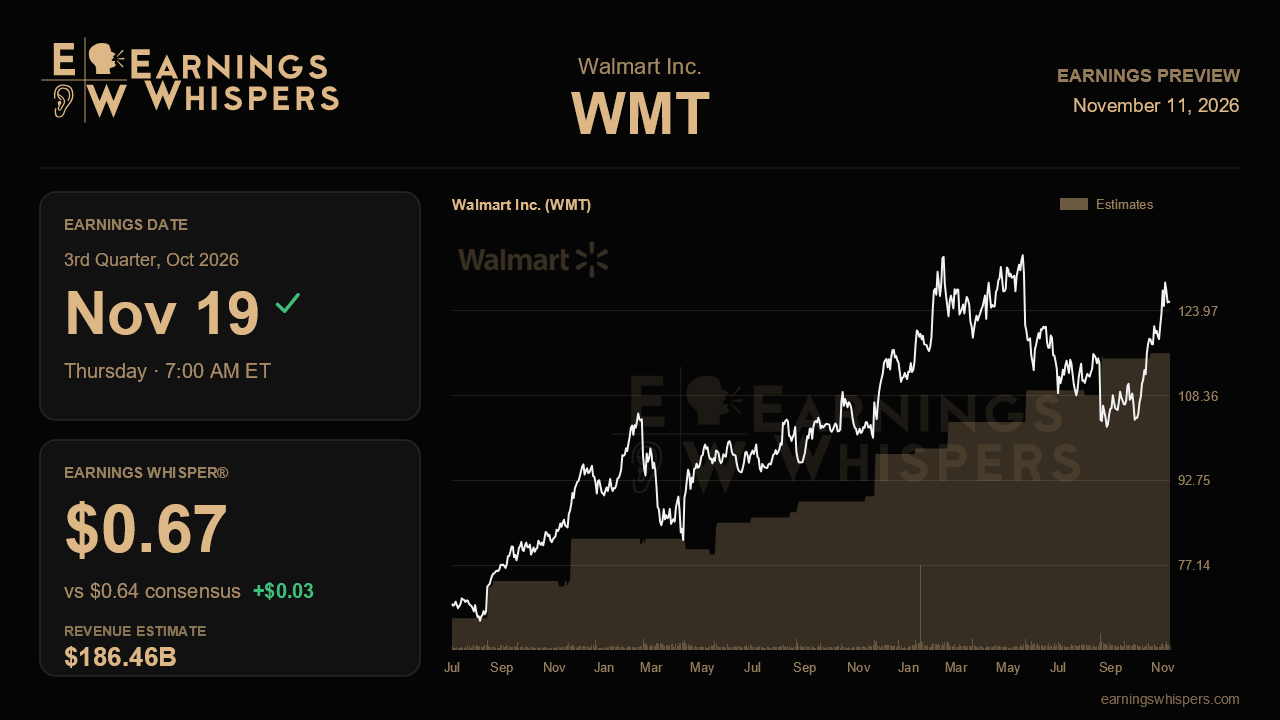
Walmart heads into its third-quarter report having told investors, in effect, to expect an air pocket. After a second quarter in which operating income jumped more than 17% in constant currency, helped by a $2.9 billion tariff refund, management guided third-quarter operating income growth to just 2% to 4% as that windfall gets plowed back into lower prices. The stock has climbed 18% since that call, against a 2.1% slip in the S&P 500. The market has bought the long-term story, so the report on November 19 is less about one soft quarter than about whether the reinvestment is earning its keep.
The Street is looking for earnings of $0.64 a share, up 3.2% from $0.62 a year ago, on revenue of $186.46 billion, up 3.9%. That is modest growth by design. Management guided to $0.62 to $0.64, so consensus sits squarely at the top of the range after drifting down from $0.68 when the outlook was issued. The Earnings Whisper of $0.67 is a few cents above both, which suggests the market expects Walmart's usual conservatism to leave room for a beat. The revenue bar looks tougher. Consensus is above the company's guided range of roughly $183.1 billion to $184.5 billion, even though management warned that lapping Flipkart's Big Billion Days event would cost more than a percentage point of sales growth. A revenue print inside guidance would technically be on plan but could still read as a miss.
The central operating question is whether the slowdown in Walmart US comparable sales stays mechanical. Comps cooled to 2.6% last quarter from 4.1% in the first quarter, but management attributed most of that to pharmacy. It raised the maximum fair pricing drug headwind to about 125 basis points for the year and halved its GLP-1 tailwind estimate. Core comps outside health and wellness held at a steady 3% to 4%. If that core pace holds, the explanation stands. If core comps slip, attention will turn to the low-income shopper, who was strained by gas above $4 last quarter, and to in-store comps, which were already down low single digits.
The second test is whether 11,000 rollbacks, up from 7,200 in the first quarter, are producing food share gains durable enough to justify the margin sacrifice. Price investment that wins traffic supports a strong second half and next year. Price investment that merely defends share in a weaker consumer environment is a costlier proposition, especially with more than $2 billion in incremental fuel costs and roughly 20 basis points of drag from the Vibe advertising acquisition.
The offset is Walmart's higher-margin flywheel, and it needs to keep spinning. Last quarter global e-commerce grew 23%, US marketplace 52%, advertising 38% and membership fee revenue a record 17%. US e-commerce posted double-digit incremental margins in the first half, and management said those margins could keep drifting higher as advertising outgrows the base. Continued strength there, plus early reads on Vibe, the Subway partnership and Walmart Plus in Canada, would support the idea that profit growth is decoupling from comps.
Sentiment is cooler than before the last report, with bullishness easing to 6.9% from 13.3%, even as the stock has rallied. Shares trade above their 200-day moving average and about 5% below the post-earnings high of $131.82, after a wider trading range than the prior quarter. That points to a valuation that already reflects confidence. Management asked investors to judge the second and third quarters together, at roughly 10% average operating income growth. The verdict depends on whether a 2% to 4% quarter arrives with steady core comps, intact high-margin growth and a full-year outlook of $2.80 to $2.87 that is reaffirmed or nudged higher. Any of those would keep the narrative intact. A cut, or weaker core demand, would make the quarter's soft profit look less like reinvestment and more like strain.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 6 hours | |
| 8 hours | |
| 13 hours | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 | |
| Nov-10 |
Walmart Upgraded Ahead Of Earnings; These Retail Stocks Are Breakout Ready
WMT
Investor's Business Daily
|
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 | |
| Nov-09 |
