Valvoline Heads Into Fiscal Q4 With Sales Booming But Base-Oil Costs Squeezing Margins
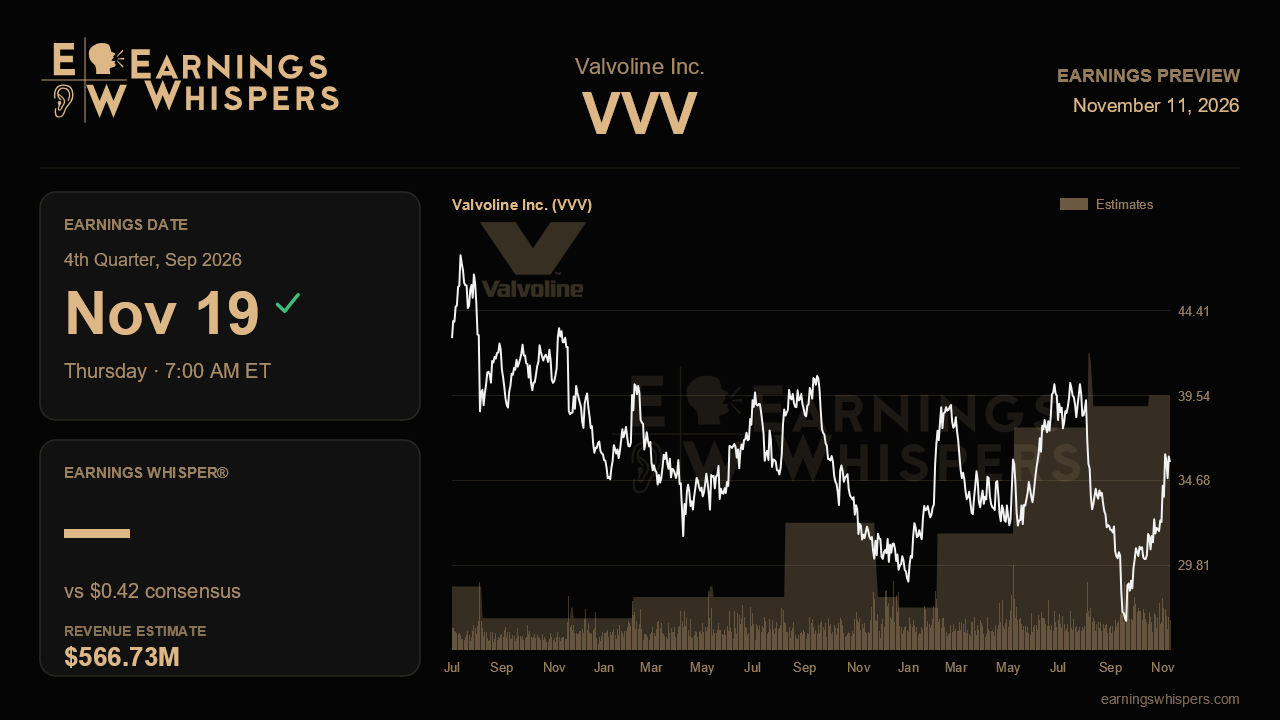
Valvoline enters its fiscal fourth-quarter report with a split personality. Customers keep showing up and spending more per visit, yet the cost of the oil going into their engines has surged so fast that the company has shifted from chasing margin expansion to simply protecting gross-profit dollars. The report due before the open on November 19 is the first full quarter to absorb the base-oil shock tied to the Strait of Hormuz closure, and it will show whether pricing can catch up with costs as quickly as management promised.
The consensus numbers capture that tension neatly. Analysts expect earnings of $0.42 per share on revenue of $566.7 million. Revenue would be up nearly 25% from a year ago, helped by the Breeze acquisition and strong comparable sales, while earnings per share would slip about 7% from $0.45. Sales are also expected to rise sequentially from the $544.6 million posted last quarter even as profit per share falls from $0.57. That is the signature of a cost pass-through quarter: more dollars flowing through the register, fewer staying on the bottom line.
Management's guidance frames the bar. Valvoline narrowed its fiscal 2026 outlook to earnings of $1.70 to $1.75 per share and revenue of $2.05 billion to $2.10 billion, trimming the low end rather than raising anything. The Street's full-year earnings estimate of $1.75 sits at the very top of that range, and revenue expectations of $2.05 billion sit at the bottom. In other words, analysts are betting Valvoline squeezes out profit at the high end without needing much extra sales help. That leaves little cushion if lubricant costs proved stickier than planned.
The prior call supplies the checklist. Management said finished lubricant costs had climbed roughly 60% above March levels, adding about $5 to $7 per oil change, and that the implied fourth-quarter outlook embedded 300 to 400 basis points of EBITDA margin compression. Executives also said price and cost should be back in balance by the end of the quarter. Margin compression at or below that range, along with commentary that pricing has fully caught up, would validate the defensive plan. Compression beyond it, or a suggestion that the lag is stretching into fiscal 2027, would challenge it, especially since management already warned elevated costs could linger four to six months after the Strait reopens.
Demand quality is the second test. Comparable sales grew 8% last quarter, with ticket accounting for about three-quarters of the gain, and the full-year comp guide was lifted to 7.5% to 8%. Because much of that ticket growth is now cost-driven pricing, transaction counts matter more than the headline comp. Management flagged softer growth among lower-income households and weaker non-oil-change service penetration in June. Steady traffic would support the idea that oil changes are essentially non-discretionary and that Valvoline is winning share as smaller rivals face supply allocation. Further softening would suggest price increases are starting to bite. Updates on Breeze conversions, which were running slightly ahead of plan, and on free cash flow and leverage, which fell to 2.8 times, will indicate whether buybacks can restart soon.
The market has taken a measured view. Shares are down 1.8% since the last report but have beaten the S&P 500 by 1.5 percentage points, and sentiment is mildly bearish, essentially unchanged from last quarter. At $35.73 the stock sits above its 200-day moving average and has rebounded well off a post-earnings low of $26.21, though it remains below the $41 level reached the prior quarter. The verdict will hinge on a single question: did price and cost truly converge by quarter's end, allowing Valvoline to enter fiscal 2027 with its margin recovery story intact?
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-02 | |
| Oct-29 | |
| Oct-13 | |
| Oct-01 | |
| Sep-29 | |
| Sep-29 | |
| Sep-25 | |
| Sep-02 | |
| Aug-31 | |
| Aug-13 | |
| Aug-13 | |
| Aug-05 | |
| Aug-05 | |
| Aug-05 |
