ESCO's Fourth Quarter Must Prove Navy And Test Strength Outrun NRG Drag As Stock Slumps
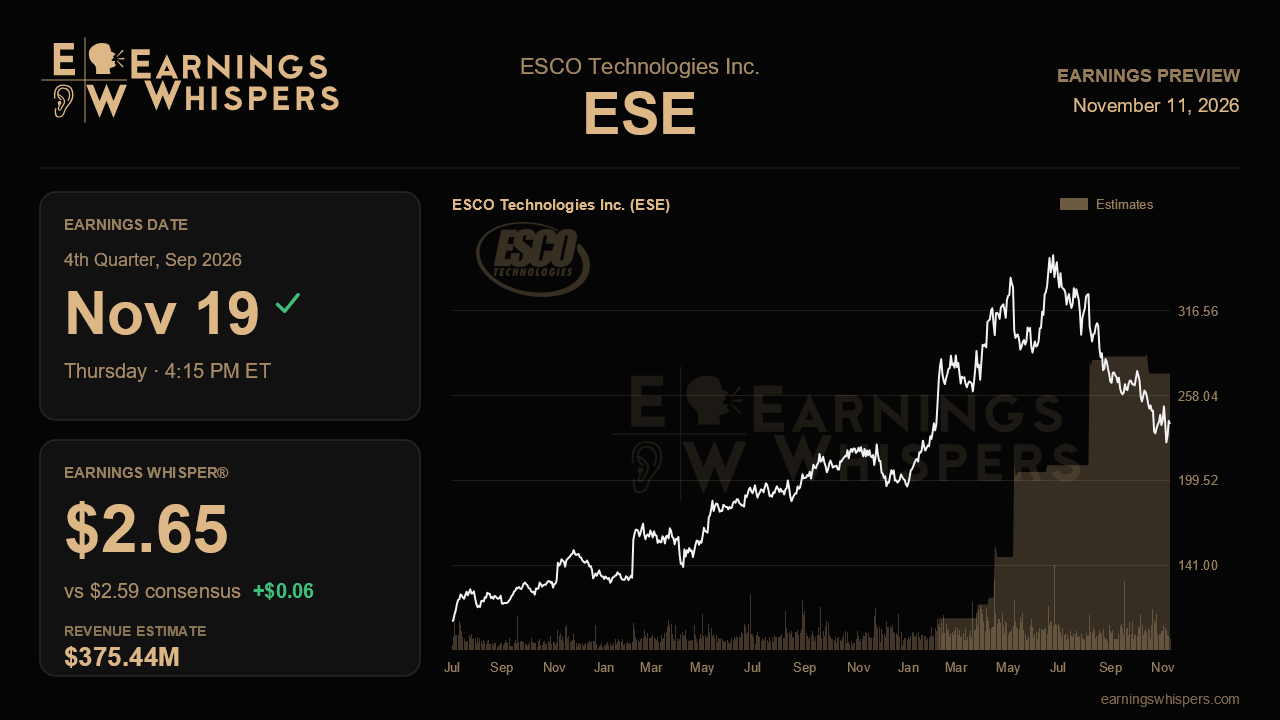
ESCO Technologies heads into its fiscal fourth-quarter report with an odd disconnect. Management has raised its full-year earnings outlook at every call this year, backlog sits at a record $1.54 billion, and defense margins keep climbing. Yet the stock has fallen about 23% since the last report, trailing the S&P 500 by roughly 20 percentage points. The results due after the close on November 19 need to show whether that selloff reflects a real crack in the story or simply a market that has stopped paying for good news.
The Street is looking for earnings of $2.59 per share on revenue of about $375.4 million. That works out to EPS growth of roughly 12% and revenue growth near 6.5% against last year's $2.32 and $352.7 million, a solid but not spectacular step up and a clear sequential improvement from the $2.20 and $339.0 million posted last quarter. Management guided the quarter to $2.55 to $2.65, and consensus has drifted up from $2.53 when that range was issued to just below the midpoint. The whisper number of $2.65 sits at the top of the range, which signals that the more engaged crowd expects ESCO to land at its high end again. Given the company's pattern this year, a result near the bottom of the range would read as a stumble even though it technically meets guidance.
The strongest evidence for the bull case should come from Aerospace and Defense. Segment margins rose from 26.5% in the first quarter to 28.6% and then 30%, helped by 9% organic growth across commercial, defense and Navy work. Holding margins around that level would confirm that the gains reflect mix and the company's continuous-improvement program rather than a one-quarter bump. The record Navy submarine award, covering Virginia-class and Columbia-class boats where ESCO already holds contracts with the primes, should support orders and cash, and operating cash flow, which more than doubled year to date on Navy advance payments, is worth checking for durability. Any update on surface-ship program timing also matters, since management described the recovery plan as on track.
Test is the second pillar. Its revenue outlook climbed from an original 3% to 5% growth to 10% to 12%, while orders jumped 42% last quarter on industrial shielding and data-center EMI filters. Investors should want to see that order surge converting into revenue and another book-to-bill above one, which would show data-center demand is broadening rather than lumpy. Doble, where orders rose 30% and condition monitoring surged 67%, needs to deliver on its raised low-double-digit growth outlook, ideally without the unfavorable high-voltage mix that weighed on the third quarter.
The weak spot remains NRG, the renewables business. Management already warned that it would decline again in the fourth quarter after tax credits expired, and its drag pulled Utility Solutions margins down 130 basis points last quarter. A known decline is not the issue; a deeper one, or early signs of the component and memory-chip cost inflation management flagged, would be.
Sentiment has warmed from slightly bearish before the last report to modestly bullish, even as the shares sit well below their 200-day moving average near $288 and only about 6% above the post-earnings low of $225. That combination suggests a relatively low bar from the stock's perspective but firm operating expectations. The fourth-quarter report has historically been where ESCO introduces its next fiscal-year framework, and with the Megger acquisition set to close in the first quarter of fiscal 2027, the forward view may matter more than the quarter itself. The central question is whether management can pair a top-of-range quarter with an outlook showing that Navy, Test and Doble momentum outweigh NRG weakness and new integration risk. If it can, the gap between fundamentals and the share price becomes hard to ignore.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| Nov-03 | |
| Oct-21 | |
| Oct-01 | |
| Aug-07 | |
| Aug-07 | |
| Aug-06 | |
| Aug-06 | |
| Jul-22 | |
| Jul-10 | |
| May-07 | |
| May-07 | |
| Apr-23 | |
| Apr-15 | |
| Apr-15 |
