Natural Grocers Must Prove Its Margin Slip Was A One-Off As Guidance Points To The High End
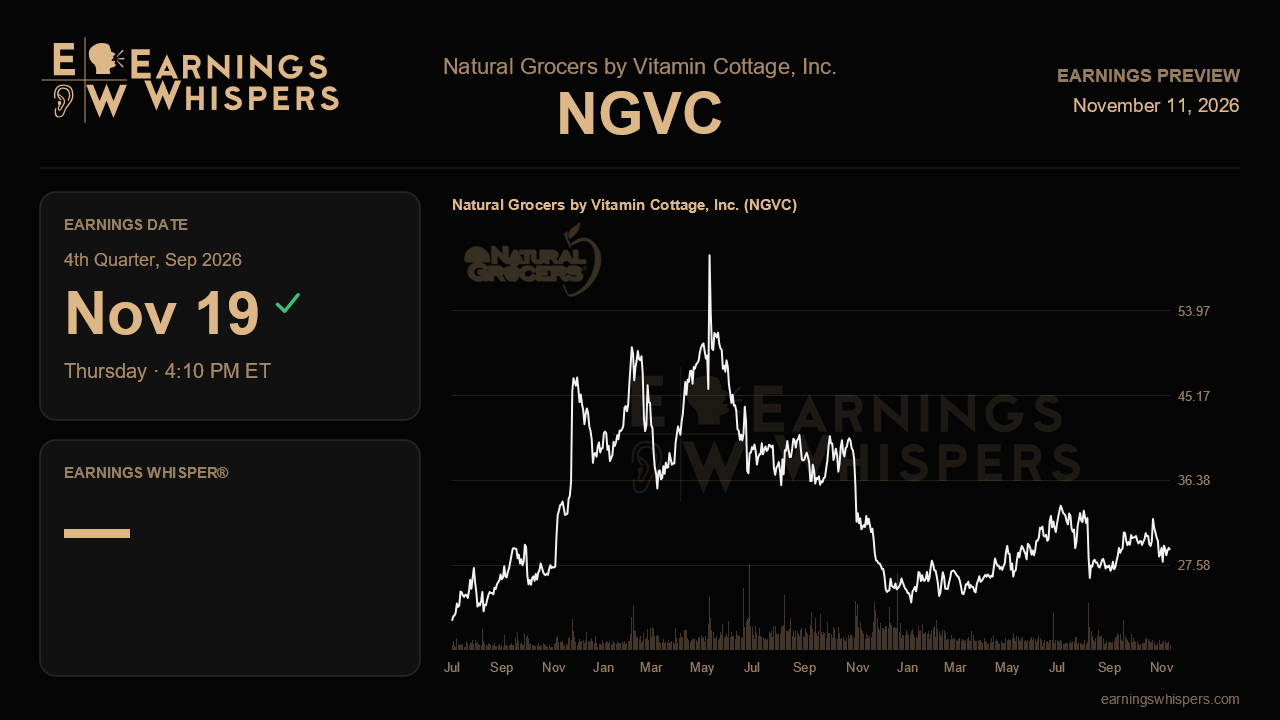
Natural Grocers heads into its fiscal fourth-quarter report with a story that sounds better than its last set of numbers. Comparable sales re-accelerated, new stores are opening with record first-day sales, and a DoorDash partnership has given the company its first real e-commerce lever. Yet gross margin dropped 60 basis points last quarter, earnings slipped below the prior year, and management quietly trimmed the top of its annual outlook. The report due after the close on November 19 should show whether that margin stumble was the isolated hiccup management described or the start of something more stubborn.
The cleanest yardstick is the company's own guidance. Management narrowed its fiscal 2026 earnings range to $2.07 to $2.11 per share from $2.07 to $2.15, and the Street's full-year estimate sits at $2.11, the very top of the revised range. That leaves essentially no cushion. To get there, the fourth quarter needs to come in near the $0.51 per share earned a year ago on roughly $336 million in revenue, despite one fewer selling day from Labor Day closures and roughly $0.08 of full-year pre-opening costs tied to the faster store build. A result that lands analysts at the low end of guidance would suggest third-quarter pressures carried over.
Gross margin is the swing factor. It fell to 29.3% last quarter as unfavorable mix, higher shrink and freight costs bit, with part of the shrink tied to an ERP system transition. Management argued much of the damage reflected one-time and comparability issues, including lapping last year's supplier cybersecurity disruption. Validation would look like margin recovering toward the 29.5% posted in the year-ago fourth quarter, along with commentary that shrink has normalized now that the ERP upgrade is behind the stores. Another decline, particularly if management again cites mix or freight, would shift the narrative from temporary noise to structural pressure, and adjusted EBITDA, which fell 7.6% last quarter, would likely stay under strain.
On the top line, the trajectory is encouraging but thin. Daily average comps improved to 1.2% from 0.5% the quarter before, entirely on a 3.1% larger basket, while transactions worsened to a 1.8% decline. Management had flagged easier comparisons from June through September, so a further step up in comps is the reasonable expectation rather than a bonus. The more telling detail is traffic. If DoorDash, which went live across the full store base in mid-July, and the curbside pickup rollout begin to stem transaction losses, the growth story gains real substance. Rising private-label penetration, which reached 9.7%, and loyalty sales at 84% of revenue also matter because both support margin as well as frequency. Investors should also look for confirmation that the store target of six to seven openings holds and that newer units keep ramping well after their strong debuts.
The market has leaned optimistic in price while growing cautious in mood. Shares have gained 5.8% since the last report, outpacing a 1.5% decline in the S&P 500 by about seven points, and at $29.15 they sit just above the 200-day moving average, in the middle of a post-earnings range between $26.02 and $32.50. Sentiment, however, has turned noticeably more bearish than before the prior report, suggesting a fair number of observers doubt the margin recovery.
Ultimately, this quarter comes down to whether gross margin rebounds. Better comps and new-store momentum are already partly assumed. If margins recover while traffic stabilizes, the high end of guidance looks credible and the growth narrative holds. If margins slip again, the improving sales picture will not be enough to offset the doubts.
This earnings preview was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-11 | |
| Nov-06 | |
| Nov-05 | |
| Oct-27 | |
| Oct-08 | |
| Oct-01 | |
| Sep-17 | |
| Sep-16 | |
| Sep-08 | |
| Sep-03 | |
| Aug-31 | |
| Aug-27 | |
| Aug-24 | |
| Aug-24 | |
| Aug-22 |
