Xunlei's Growth Stalls As Heavier Marketing Spend Pushes The Core Business Deeper Into Losses
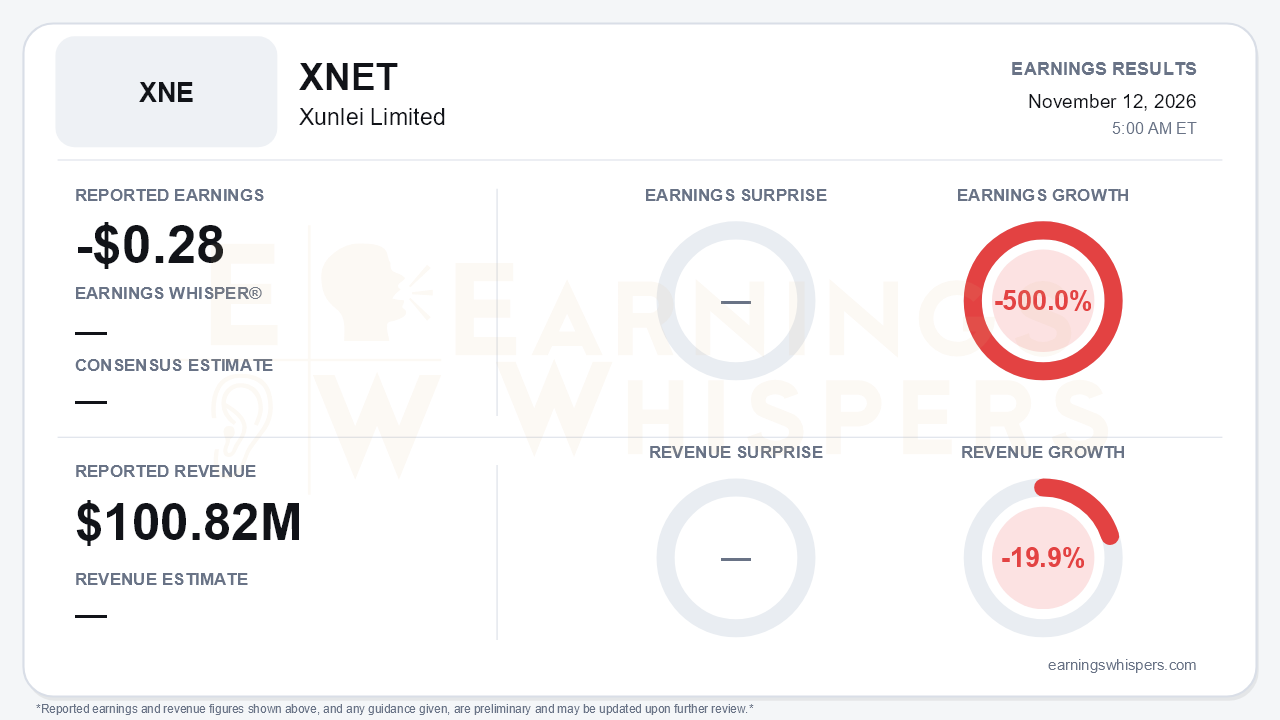
Xunlei's third quarter marked a clear break in the growth story that carried the stock through the first half of 2026. Earnings Whispers recorded a loss of $0.28 per share on revenue of $100.82 million, with earnings down 500.0% year over year. No consensus or Whisper estimate was available, so this report is best judged on its operating trajectory rather than a beat or miss. That trajectory is poor. Revenue fell sequentially, the core business swung further into the red, and management's own language shifted from confidence to caution.
The revenue picture needs one clarification. Earnings Whispers' normalized figures show revenue down 19.9% year over year. Xunlei's release, which restates prior periods to exclude the Shenzhen Onething cloud computing business sold in March, shows total revenue up 12.9% to $101.3 million. The difference appears to reflect the comparison basis rather than a dispute over the quarter itself. Either way, the direction is the same. Restated growth has collapsed from 54.1% in Q1 to 38.9% in Q2 to 12.9% in Q3, and revenue slipped from $102.7 million in Q2.
The GAAP loss of $3.74 per ADS is dominated by a $219.2 million other loss, mostly a $217.9 million fair-value markdown on the stake in Arashi Vision. Investors can set that line aside, but they should not set aside the operating deterioration beneath it:
- Operating income went from $4.3 million in Q1 to a loss of $4.8 million in Q2 and a loss of $14.8 million in Q3.
- Non-GAAP net income moved from $4.1 million to a $2.1 million loss and then a $16.4 million loss, or $0.26 per ADS.
Both growth engines lost speed together, which is the most troubling development. Subscription revenue grew just 8.5% to $44.1 million, down from 26.2% in Q1 and 22.6% in Q2, and it declined slightly from the prior quarter. That is the slowest growth in years. Live-streaming and other revenue grew 16.6% to $57.2 million, compared with 89.3% and 54.8% in the two prior quarters. On the call, management cited rising user-acquisition costs and tougher competition in the Middle East, Turkey and Latin America.
The cost structure moved the wrong way at the same time:
- Gross margin fell to 55.7% from 62.0% a year earlier, as lower-margin overseas audio live-streaming made up more of the mix and revenue-sharing costs outran revenue.
- Sales and marketing rose to 32.9% of revenue, up from 27.2% in Q2 and 22.8% in Q1.
- R&D rose to 25.3% of revenue.
That is the central tension: Xunlei is spending considerably more to acquire users while getting markedly less growth in return.
Management's tone tracked the numbers. The language moved from Q1's "robust momentum" and Q2's "clear validation" to Q3's "moderated pace" and "transitional headwinds." CEO Jinbo Li acknowledged "softer near-term momentum" in the release.
The call did offer a recovery case, but it rests on promises rather than results. Management said the subscription user-acquisition reset, under way since Q2, targets higher-retention, higher-lifetime-value users and should lift growth in later quarters. It also guided qualitatively that Q4 marketing spend would be controlled or deliver better returns than in Q3. Hupu advertising benefited from the World Cup year, with both brand and performance ads growing. That boost is event-driven and cyclical, however, and should not be extrapolated.
Bears have legitimate ammunition beyond the operating trend:
- **Shrinking cash:** Cash and short-term investments fell from $303.6 million in Q1 to $276.9 million in Q2 to $265.1 million, driven by operating outflows and buybacks.
- **Arashi Vision exposure:** The 7.8% stake is above a 5% regulatory threshold, management gave no timeline for divesting it, and mark-to-market losses continue. Long-term investments have dropped from $1.07 billion at year-end to $454.6 million.
- **Regulatory status:** Management described the company's position against the Investment Company Act's 40% threshold as "borderline."
- **Litigation:** Provisions for legal matters are inflating G&A expense.
Capital return is the clearest shareholder-friendly signal. Xunlei repurchased about 2.7 million ADSs for $13.8 million in Q3, exhausting the original program, and the board approved a new $20 million authorization. Management framed the pace of buybacks as conviction that the share price undervalues the business. Still, a company running operating losses and funding repurchases from a declining cash balance is trading flexibility for signaling. Investors should weigh both sides of that choice.
Investor sentiment and current price data were not available for this report. The stock opened at $5.00 after the August report, below its 200-day moving average of $5.39. That suggests the market was already skeptical before this quarter's slowdown became visible. Nothing in this release gives that skepticism obvious reason to fade.
The bottom line is that Xunlei's Q3 moves the debate from how fast the company can grow to whether its spending can restore growth at all. Revenue stalled sequentially, both segments decelerated sharply, and the core operation is losing money at an accelerating rate. The large GAAP losses are mostly Arashi Vision noise, but the operating losses are not. The buyback and management's promised Q4 marketing discipline offer some support, but the burden of proof now sits firmly with management. Next quarter needs to show that the user-acquisition reset is producing better returns, not simply higher costs.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-05 | |
| Aug-13 | |
| Aug-13 | |
| Aug-06 | |
| Jun-26 | |
| May-28 | |
| May-28 | |
| May-19 | |
| Apr-28 | |
| Mar-16 | |
| Mar-12 | |
| Mar-12 | |
| Mar-05 |
