Acurx Misses Q3 Loss Estimate As Dilution Drives The Per-Share 'Improvement'; PATHFINDER Starts Early But Funding Pressure Grows
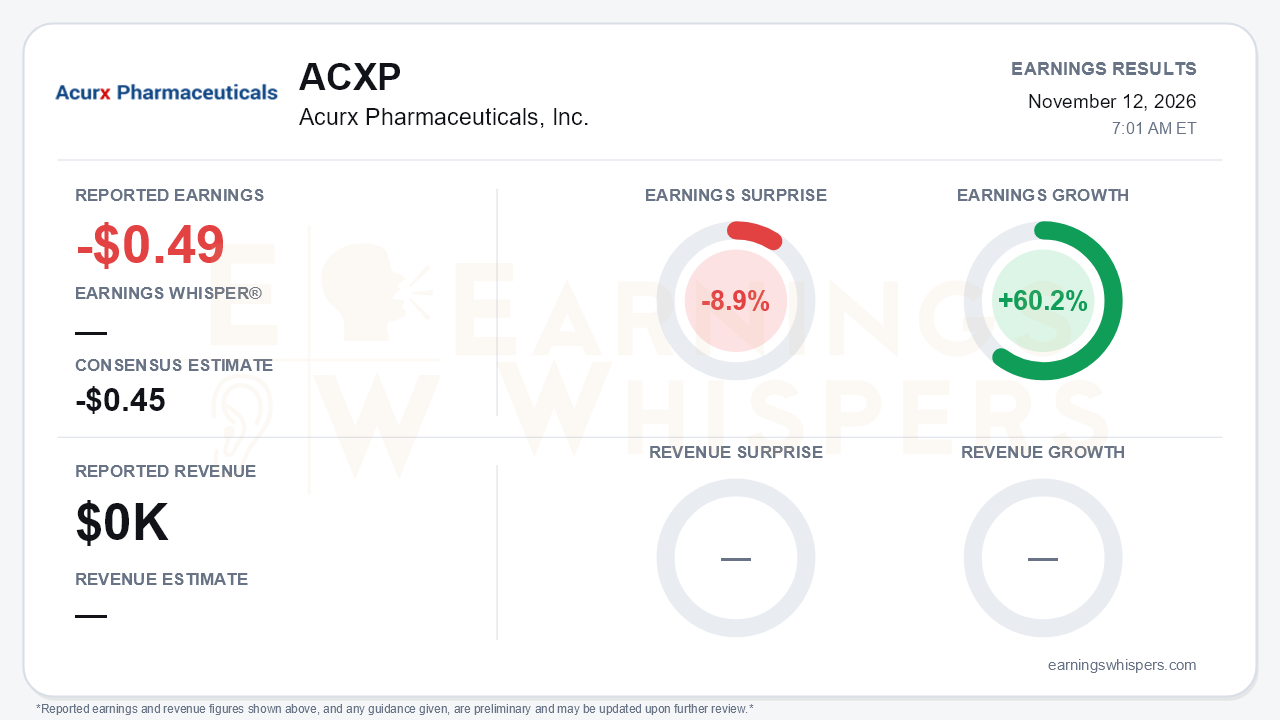
Acurx Pharmaceuticals reported a third-quarter loss of $0.49 per share, worse than the consensus estimate of a $0.45 loss, an 8.9% miss for the pre-revenue antibiotic developer. On paper, earnings improved 60.2% from a year ago, when the company lost $1.23 per share. That comparison is misleading. Net loss actually widened to $2.6 million from $2.0 million. The per-share gain comes almost entirely from a share base that has exploded: weighted average shares rose to 5.3 million from 1.6 million. That is the central tension. Acurx is finally turning its clinical plan into execution, but it is paying for that progress with steady dilution, a thinning cash cushion, and growing questions about its capital-markets standing.
The spending mix shows where the money is going. R&D expense rose to $1.1 million from $0.4 million a year earlier. Management attributed nearly all of the increase to consulting costs for the new recurrent C. difficile (CDI) program. G&A edged down to $1.5 million, and nine-month G&A fell to $4.1 million from $4.9 million, so overhead discipline is real. Spending is shifting toward the clinic, which is the right direction for a development-stage company. The sequential trend is less flattering. Net loss has climbed from $1.7 million in Q1 to $2.3 million in Q2 and $2.6 million in Q3.
Cash ended the quarter at $9.7 million, down from $10.7 million at the end of Q2. The company raised only about $1.5 million through its equity line in Q3, versus $3.3 million in Q2. Shares outstanding reached 5.88 million, up from 4.68 million at mid-year and 2.35 million at year-end 2025. Management said only about 12 months of funding is secured, which implies more equity-line draws, stock offerings, or a partnership.
Operationally, the call delivered genuine progress. PATHFINDER, the 20-patient trial in multiply-recurrent CDI, began enrolling September 29. That beat the Q4 start guided on the Q2 call, though it slipped from the August first-patient hope floated earlier in the year. Enrollment completion is now targeted for the second half of 2027.
The more strategically important disclosure was a sketch of PATHFINDER II. This would be a pivotal trial of about 350 patients, run internationally under the FDA's LPAD pathway, possibly using Vowst as the active comparator, with 1.5 to 2 years of enrollment. If PATHFINDER succeeds, this route could precede the still-unfunded ASPIRE Phase 3 in acute CDI, with ASPIRE becoming a supplemental filing. The regulatory picture remains uncertain:
- The FDA said only that it is open to discussing the totality of evidence at a pre-NDA meeting.
- It has not confirmed that a single acute-CDI trial would suffice.
- No pharma partnership has reached public disclosure.
Supporting milestones included FDA conditional acceptance and trademark allowance for the CIFBEZY brand name, new Japan and Mexico patents protecting ibezapolstat into June 2042, and continued preclinical microbiome publications. These add to the asset's profile but do not change the funding equation.
The risk section of the call grew more defensive. Nasdaq listing compliance came up explicitly in stakeholder Q&A. Management also disclosed a bylaw amendment cutting the stockholder quorum from a majority to 33.33%, citing a fragmented shareholder base. Neither item is decisive alone. Together, they signal a company managing the side effects of serial dilution: a widely dispersed retail holder base and a share price hovering around $1.
The market has treated the stock harshly. Shares fell 28% from the $1.43 open after the August report to $1.03. They sit roughly 46% below the 200-day moving average and 43% below the quarter's $1.82 high, set just days after the last report. The stock touched a 52-week low of $0.95 on November 5 and entered earnings only about 9% above that level. Earnings Whispers trend readings lean negative, with sequential growth and AVWAP both pointing lower. Investor sentiment, however, moved in the opposite direction. It improved sharply from deeply negative (-0.66) to roughly neutral (-0.04) ahead of the report. That suggests some investors are looking past the price damage toward the PATHFINDER start, although it is not a signal in itself.
The bottom line is that Acurx's quarter was better operationally than its headline miss suggests and worse financially than its 60% per-share improvement implies. PATHFINDER enrolling ahead of the Q2 guidance and a credible LPAD shortcut give the story a clearer clinical path. But the company's survival depends on continued equity raises at depressed prices. With a widening absolute loss, about a year of secured runway, an unfunded Phase 3, and listing-compliance questions now on the table, the burden of proof sits on financing and partnership news rather than science.
Read our earnings preview for Acurx Pharmaceuticals, Inc.: https://www.earningswhispers.com/article/ACXP/22986
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
