Absci Matches The Whisper, But Endometriosis Delay And Rising Burn Make December's Hair-Loss Readout The Whole Story
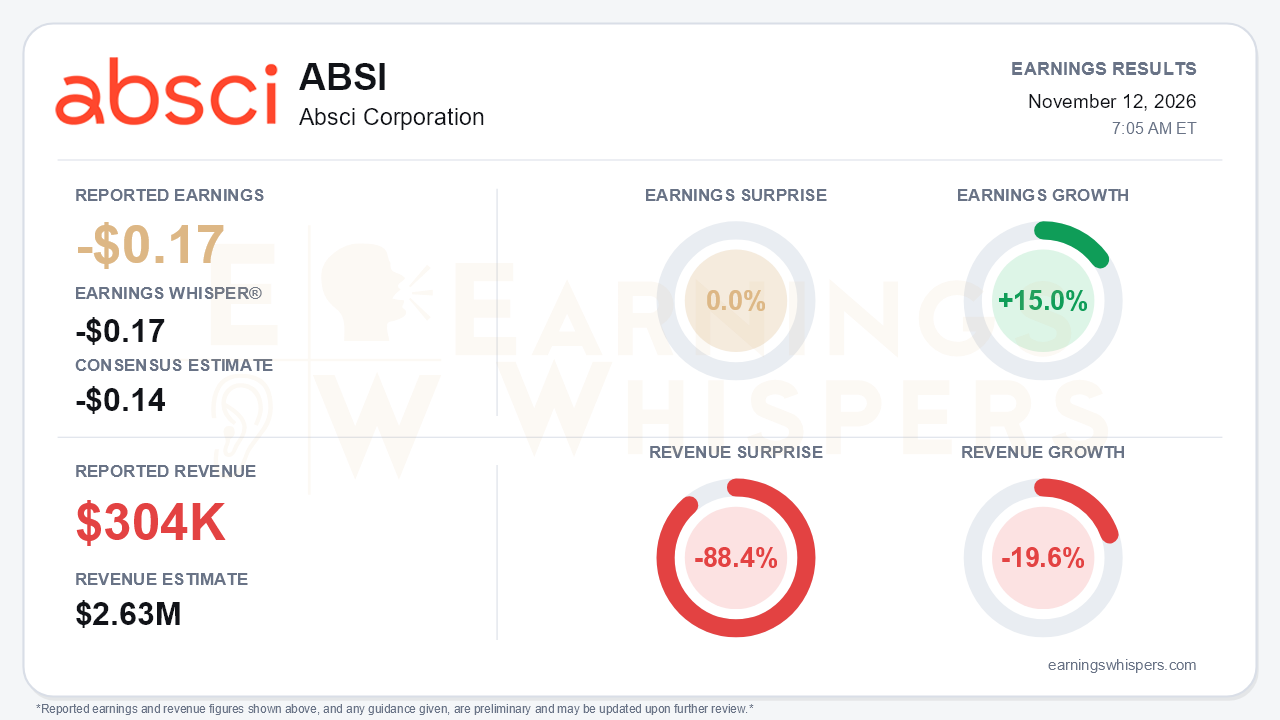
Absci reported a third-quarter loss of $0.17 per share, exactly matching the Earnings Whisper number for a 0.0% surprise, though wider than the -$0.14 consensus. Earnings improved 15.0% year over year. Revenue of $0.3 million missed the $2.63 million consensus by 88.4% and fell 19.6% from a year ago. For a clinical-stage biotech, the revenue miss matters little. Partner program revenue is now a rounding error. The real development was on the pipeline calendar: ABS-201's hair-loss interim readout was pinned to December, while the endometriosis Phase 2 start slipped roughly two quarters. That is the central tension. The near-term catalyst got more concrete just as the secondary indication moved further out and cash consumption kept climbing.
The quality of the per-share improvement deserves scrutiny. The release's GAAP statement shows a net loss of $0.19 per share versus $0.20 a year ago, which differs from the normalized -$0.17 figure. On either basis, the improvement reflects a larger share count rather than a smaller loss. Weighted shares rose to 171.8 million from 143.8 million after this year's equity raise. In dollar terms, the net loss widened to $33.3 million from $28.7 million.
Research and development rose to $23.6 million from $19.2 million a year ago. That figure has climbed steadily from $19.3 million in Q1 and $22.6 million in Q2 as ABS-201 clinical spending ramps. SG&A edged up to $9.0 million, which the company attributed to stock-based compensation. Partner revenue for the first nine months fell to $0.8 million from $2.2 million, underscoring that the drug-creation partnership business is not offsetting the burn.
On the call, management presented the HEADLINE trial as on track. The 1200mg multiple-ascending-dose cohort is fully enrolled, and two open-label female pattern hair loss cohorts (300mg and 1200mg) have begun enrolling. The December 13-week update will cover all 300mg patients, most of the 600mg cohort and an early look at 1200mg. Full 26-week data are due in early 2027. A half-life of roughly 60-65 days still supports the targeted two or three injections over six months.
The framing, however, has shifted in a way investors should note:
- Management leaned harder on total hair count, including vellus hairs.
- It called the 13-week data "directional."
- It said it will disclose only the week-13 timepoint, with safety aggregated by blinded dose group rather than unblinded against placebo.
That reads as expectation-setting. It lands as a competitor's strong one-year hair-loss data drew analyst questions and raised the competitive bar.
The endometriosis program is where guidance clearly moved backward. The STORYLINE Phase 2 had been guided to start in Q4 2026 on each of the prior three calls; it is now expected in mid-2027. Prior 2H27 proof-of-concept timing was not reaffirmed. The trial design is now detailed: about 150 patients across 10+ countries, testing two or three dose levels, with pain endpoints. The doses depend on HEADLINE data, effectively tethering the second indication to the first.
The Eli Lilly collaboration was a centerpiece of the Q2 call and included $40 million of the recent $100 million raise. It went unmentioned this time. That may be nothing, but bears have legitimate ammunition. On the constructive side, the appointment of former Galderma executive Gerry Muhle as the company's first Chief Commercial Officer signals intent to build direct-to-consumer infrastructure ahead of data.
Cash and securities fell $27.4 million in the quarter to $173.7 million. Management reaffirmed runway into the second half of 2028, so financing is not an immediate issue. Still, rising R&D means the cushion is being consumed faster.
Investor sentiment deteriorated meaningfully, falling from 0.53 to 0.15. It remains positive, but enthusiasm has clearly cooled. Price action tells a more forgiving story. Heading into the report, shares sat at $10.12, up 12.2% from the $9.02 open after the August release and nearly 50% above the 200-day moving average of $6.75. The stock has already been volatile within the quarter: it ran to a 52-week high of $12.54 on October 29 before giving back about 19%, and it remains roughly 30% above the September low of $7.79. Earnings Whispers momentum and AVWAP trend readings remain positive. That suggests the market has been positioning for the December readout even as sentiment softened.
The bottom line is that Absci delivered a quarter that matched whisper expectations but changed little fundamentally, aside from pushing endometriosis further out and lifting the spend rate. With a cooler tone around the 13-week data and a tougher competitive benchmark, the stock's sizable run since summer leaves the December interim readout carrying nearly all of the weight for the investment case.
Read our earnings preview for Absci Corporation: https://www.earningswhispers.com/article/ABSI/22857
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 6 hours | |
| 6 hours | |
| Nov-04 | |
| Oct-27 | |
| Oct-13 | |
| Sep-24 | |
| Sep-03 | |
| Sep-01 | |
| Aug-30 | |
| Aug-11 | |
| Aug-10 | |
| Jul-24 | |
| Jul-15 | |
| Jul-14 |
