Aurora Mobile Posts Record SaaS Quarter, But A Steep Guidance Cut Undercuts The Story
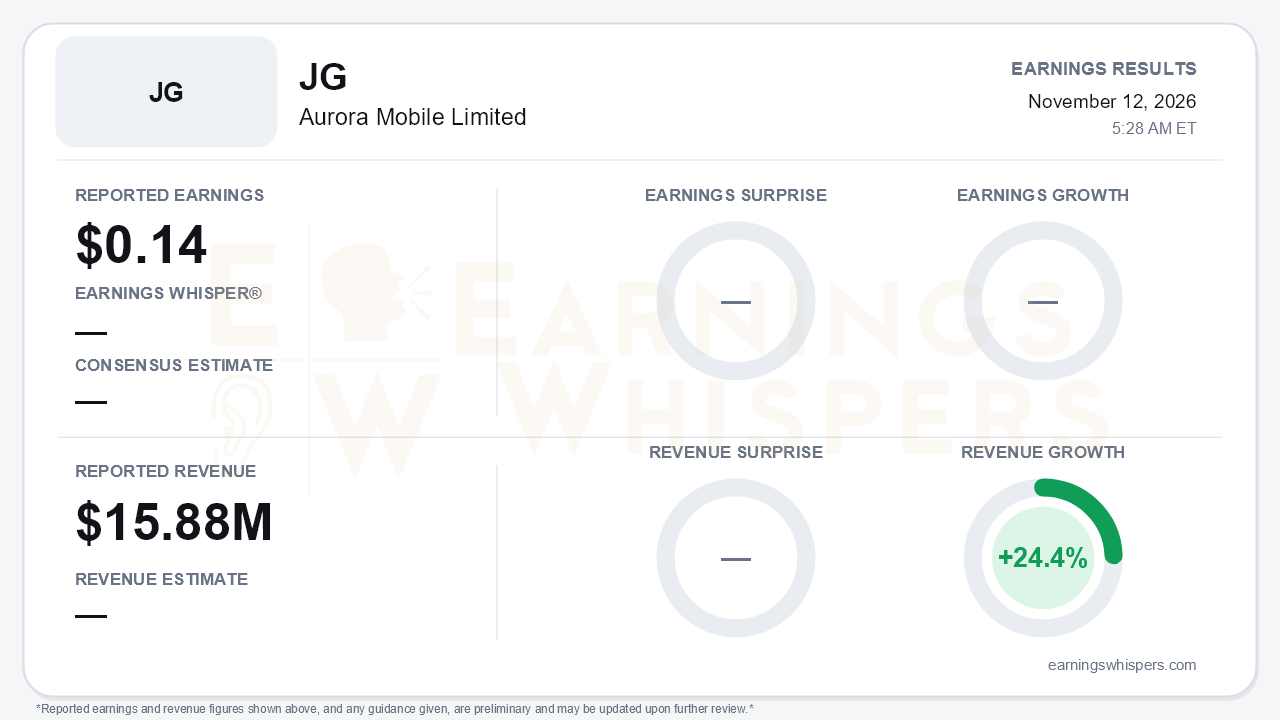
Aurora Mobile (NASDAQ: JG) delivered the strongest core quarter of its pure-SaaS era and, in the same release, cut its full-year revenue outlook by roughly 12% at the midpoint. That is the central tension. The company reported earnings of $0.14 per share on revenue of $15.88 million for the September quarter, with Earnings Whispers measuring year-over-year revenue growth at 24.4%. The release reports 17% growth in local currency, rising to RMB106.5 million from RMB90.9 million. That gap likely reflects currency translation, since the company reports in RMB. No consensus or whisper figures were available, so the quarter cannot be judged as a beat or miss. The more useful comparison is with management's own targets, and there the news was clearly negative.
The headline numbers hold up on the surface. Revenue growth accelerated for a third straight quarter, from 5% in Q1 to 13% in Q2 and 17% in Q3. Developer Services rose 37% year over year. Subscription revenue hit a record RMB77.0 million, up 34%, and value-added services jumped 57%. GAAP net income attributable to shareholders was RMB4.7 million, compared with a fractional loss a year ago. That marked a sixth straight profitable quarter and the company's best net profit since adopting the pure-SaaS model in 2021. The quality of the earnings deserves scrutiny, however:
- RMB2.7 million of other operating income accounted for about half of the RMB5.5 million operating profit.
- General and administrative expense fell 24%, helped by a RMB1.9 million lower bad-debt provision.
- A RMB3.1 million foreign-exchange loss was partly offset by a small tax benefit.
- Gross margin slid to 66.6%, from 68.3% in Q2 and 70.2% a year ago. Cost of revenues rose 31% on media costs and overseas direct costs tied to OTP, WhatsApp push and GPTBots.ai.
- Gross profit growth slowed to 11% from 16% in Q2.
- Operating cash inflow dropped to RMB6.6 million, from RMB23.3 million in Q2 and RMB35.1 million in Q4 FY25.
The call kept a credible growth story intact for the international business. EngageLab, the global flagship, posted record revenue of RMB29.5 million. It also signed a best-ever RMB32.8 million in new contracts, up from RMB27.4 million in Q2, and its customer count passed 2,430, up 86%. Net dollar retention held at a record 106%, and deferred revenue reached a record RMB185.2 million. Management said overseas revenue is now roughly a third of the group total; the CFO characterized it as closer to 30%. The trajectory is cooling, though. EngageLab's growth slowed from 210% in Q1 to 186% in Q2 and 124% in Q3, and the company stopped disclosing its ARR metric. Dropping a key growth metric just as growth decelerates rarely builds investor confidence.
The damage is concentrated in Vertical Applications, which fell 31% year over year. Within that segment, financial risk management revenue dropped 36% year over year and 19% sequentially, worse than the 17% decline in Q2. Management said regulatory tightening in China's consumer credit and loan-facilitation industries has run deeper and longer than it expected, as customers curb new origination and budgets. As a result, the company lowered FY2026 revenue guidance to RMB405–415 million (8–11% growth), from RMB450–480 million (20–28% growth). Nine-month revenue of RMB301 million implies Q4 revenue of roughly RMB104–114 million, little changed from Q3 at the low end. Bears have legitimate ammunition on credibility: on the Q2 call, management said the company remained on track for the original target.
There are offsetting positives:
- A three-year MOU with Southeast Asia-based Exabyte broadens regional distribution for EngageLab and GPTBots.ai.
- New subscription wins include Tesla China, Bilibili, Kai Tak Sports Park and Civic Bank.
- Market intelligence returned to growth, up 18% year over year.
- Buybacks more than doubled to 99,432 ADSs, about $532,000.
The balance sheet is thin rather than strong. Cash, restricted cash and short-term investments totaled RMB165.0 million, down from RMB173.4 million at year-end. A RMB5 million short-term loan and RMB3.7 million in digital assets also appeared on the books.
Market context is sparse. Shares opened at $6.27 after the August report, but current price, sentiment readings and technical levels were not available. As a result, how investors were positioned going into this guidance cut cannot be assessed.
The bottom line is that Aurora Mobile's core developer and overseas SaaS engine is accelerating while its China financial-risk business shrinks. The guidance cut shows the decline is outpacing management's ability to forecast it. Investors get a better-quality mix tilted toward subscriptions, but with thinner margins, weaker cash generation, a less transparent EngageLab disclosure and a credibility discount on future targets. The next few quarters need to show that FRM has stabilized and that EngageLab's deceleration is levelling off rather than continuing.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-12 | |
| Nov-10 | |
| Nov-10 | |
| Nov-03 | |
| Oct-30 | |
| Oct-28 | |
| Oct-23 | |
| Oct-16 | |
| Oct-15 | |
| Oct-09 | |
| Sep-29 | |
| Sep-28 | |
| Sep-22 |
