Rockwell Medical's Sales Acceleration Is Overshadowed By Withdrawn Guidance And A Deal That Redefines The Story
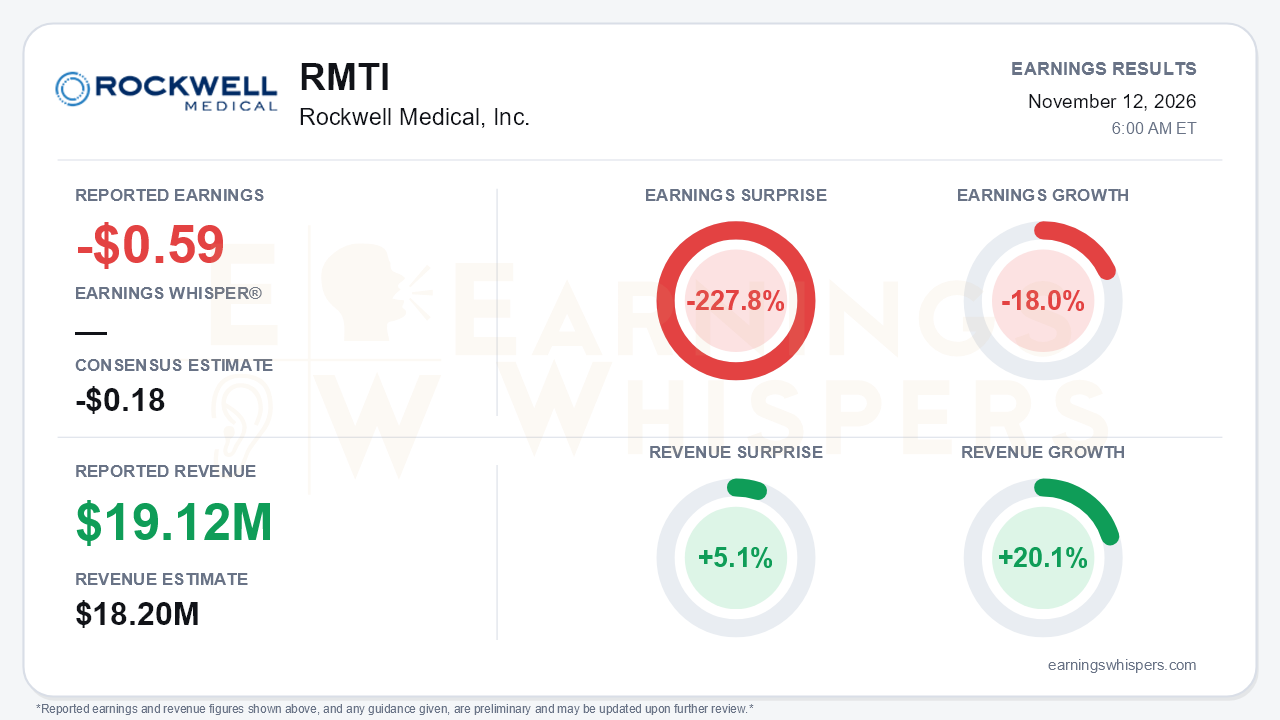
Rockwell Medical's third quarter delivered a strong top line, but the operating picture underneath it got worse. The company reported a GAAP loss of $0.59 per share, well short of the -$0.18 consensus. That is a 227.8% miss, and earnings fell 18.0% from a year ago. Revenue was the opposite story. Net sales of $19.12 million beat the $18.2 million consensus by 5.1% and grew 20.1% year over year. Hanging over both numbers is the pending acquisition of Vantive's global hemodialysis business, which management calls transformational. To make room for it, the company withdrew every piece of its fiscal 2026 guidance. That is the central tension: the core business is selling more product than at any point this year, but it is not turning that volume into profit, and the guidance that anchored the story is gone.
The headline miss needs context. The GAAP loss includes $847,000 of transaction-related expenses tied to the Vantive deal. Per-share comparisons also absorbed a roughly 10% rise in weighted shares from a year earlier. The company's own adjusted EPS, which it derives from Adjusted EBITDA, was -$0.07. Investors should weigh the size of the miss with that basis difference in mind. Even setting deal costs aside, though, the underlying trend is soft. Adjusted EBITDA was -$0.3 million, versus a small positive result a year ago and +$1.0 million in the fourth quarter of 2025. General and administrative expense rose to $3.8 million from $3.3 million. Cash fell to $22.5 million from $24.8 million in June, which management attributed to higher receivables, prepaid expenses and automation spending.
Revenue is plainly accelerating. Sales fell 8% year over year in the first quarter, grew 11% in the second and grew 20% in the third, the third straight sequential gain. Nine-month sales are now up 7% after a flat first half. Management credited three drivers:
- heavier purchasing from existing customers, including higher volumes from all five of the largest U.S. dialysis providers;
- new customers in the western United States;
- competitor FDA recalls that opened doors for share gains.
The weak point is margin. Gross margin of 16% improved from 14% a year earlier but slipped from 18% in the second quarter and 21% in the fourth quarter of 2025. Freight, material and diesel-driven supply costs were the main pressures. Gross profit rose 37% on volume, but the company is not yet showing the operating leverage that would make that growth self-funding.
The guidance withdrawal is the most consequential change in the setup. Management pulled its $70-75 million sales target, its 18-22% gross margin range, its $1-2 million Adjusted EBITDA target and its goal of positive operating cash flow. Management cited deal expenses as the reason. Even before the withdrawal, those targets looked difficult. The nine-month gross margin of 17% sits below the low end of the margin range, and nine-month Adjusted EBITDA of -$0.7 million made the $1-2 million target hard to reach. The withdrawal also ends the company's frequently repeated record of meeting or exceeding guidance for three straight years. New guidance is not expected until around March 2027.
The bull case now rests on Vantive. The combination is projected to generate $400-450 million in annual revenue, about 90% of it recurring. That dwarfs Rockwell's prior goal of more than $100 million in sales by 2029. The deal brings machines, water treatment systems, consumables and a one-million-square-foot manufacturing campus in Medolla, Italy. Management says existing customers are already asking about cross-selling the broader portfolio. The execution risks are substantial:
- financing terms were not disclosed, leaving the scale of dilution or debt unknown;
- closing is targeted for mid-2027 and depends on regulatory approvals;
- the cross-border integration relies on transition service arrangements with Vantive and on maintaining supply continuity;
- more deal costs are expected in the fourth quarter.
Investor sentiment swung sharply ahead of the report, from -0.66 to +0.11. That shift coincided with the deal announcement and suggests expectations moved from pessimistic to cautiously constructive. The stock has not followed. At $7.08 entering the report, shares were down 8.1% since the open after the prior release. They sat 12.9% below the 200-day moving average and about 20% below the September high of $8.90. The price was only 6% above the October low of $6.68, so the stock had given back most of its earlier strength. AVWAP remains negative, consistent with buyers still sitting on losses since the last report.
The bottom line is that Rockwell Medical is no longer being judged on quarterly guidance. It is being judged as a small company attempting a roughly fourfold leap in scale. The accelerating sales and share gains give that ambition a credible operating base. Shrinking margins, negative EBITDA, a falling cash balance and an undisclosed financing plan give bears legitimate ammunition until the deal's terms and integration path come into focus.
Read our earnings preview for Rockwell Medical, Inc.: https://www.earningswhispers.com/article/RMTI/23000
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 4 hours | |
| 4 hours | |
| Nov-06 | |
| Nov-03 | |
| Nov-03 | |
| Nov-03 | |
| Oct-15 | |
| Oct-14 | |
| Oct-07 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Jul-22 | |
| Jul-20 |
