LASE Narrows Its Loss And Returns To Sales Growth, But Negative Gross Margins And A Going-Concern Warning Put The Counter-Drone Pivot On A Financing Clock
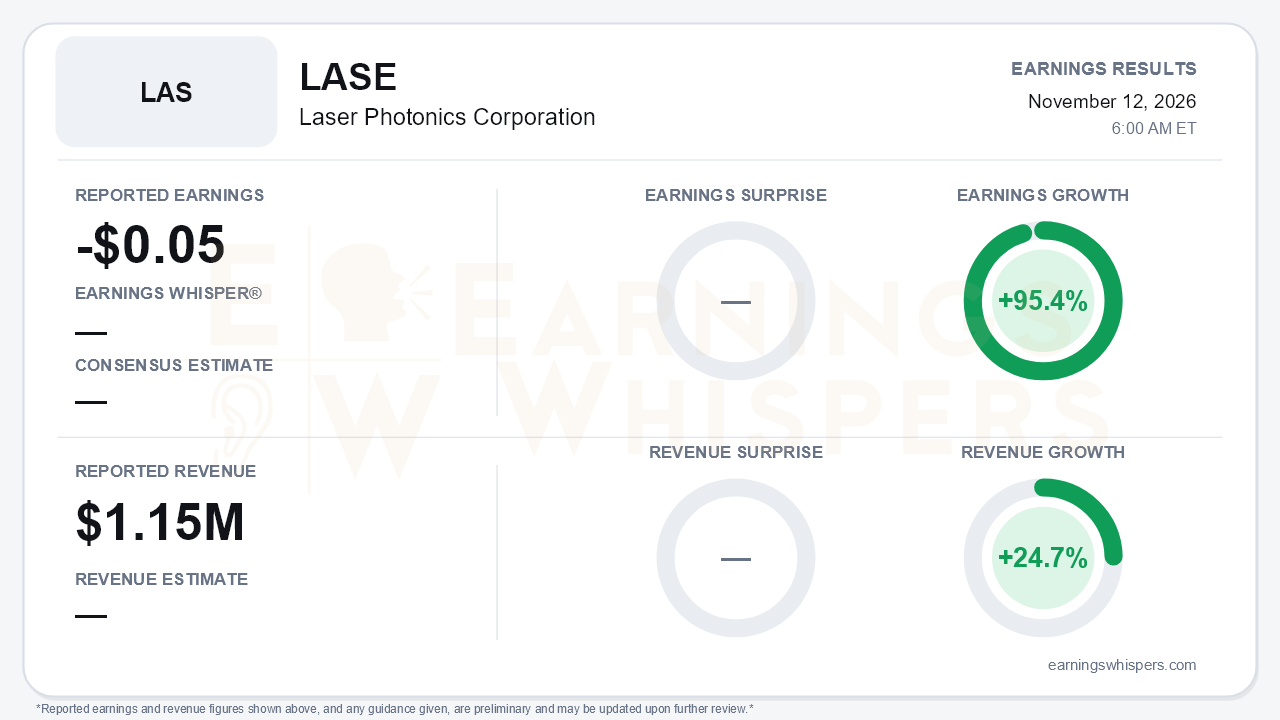
LASE Corp., the former Laser Photonics, reported a third-quarter loss of $0.05 per share on revenue of $1.15 million. Earnings improved 95.4% year over year and revenue grew 24.7%. It was the company's first year-over-year sales gain since Q4 2025 and its first year-over-year improvement in quarterly net results since Q4 2024. There was no consensus estimate or Whisper to measure against, so the quarter has to be judged on its own terms. On those terms, the headline improvement is real but narrow. The company fixed its balance sheet and cut overhead. It has not yet shown that its core laser business can sell product at a profit, and that is the central tension of the report.
The quality of the per-share improvement deserves scrutiny. The prior-year $1.09 loss per share attributable to common stockholders was inflated by roughly $14.1 million of deemed dividends tied to a common-control acquisition and a warrant exchange. Weighted shares also tripled, from 17.1 million to 51.6 million. Net loss itself narrowed 46% to $2.5 million from $4.7 million. Two levers drove that improvement:
- Net interest expense fell to about $0.2 million from $1.4 million after all notes, including related-party debt, were repaid.
- General and administrative expense dropped by more than half, to $1.1 million.
Sales and marketing and R&D both rose. More tellingly, gross loss slightly widened in dollar terms to $449,000. Gross margin improved 8 points year over year but remained at -39%. That is a striking collapse from the 85.8% the company posted in Q3 FY24 and the 51-52% levels of early FY24. Year-to-date sales fell to $3.9 million from $5.8 million, with laser cleaning down $1.1 million and affiliate sales down $0.8 million.
The call made clear how much the story has changed. The FY24 cleantech narrative has largely vanished from management's pitch: Acuren, Navy work, the Brokk partnership and the $70 million pipeline went unmentioned. In its place is a four-market strategy anchored by directed energy. There are genuine operating datapoints beneath the rebrand:
- The first semiconductor molecular-splitting system has shipped.
- CMS Laser carries pharma orders expected to convert in 2027.
- The acquired Beamer cutting line, now relocated to Lake Mary, is reporting strong bookings.
The balance sheet supports the bookings commentary. Contract liabilities more than doubled since year-end to $2.8 million, which suggests customer deposits are building ahead of revenue. Management's tone was markedly more expansive and governance-focused under Executive Chairman Dmitri Nikitin and new CFO Timothy Peterman. Demand commentary was essentially flat, and the company offered no quantitative guidance beyond a stated goal of operating cash-flow breakeven.
The Quantum Bullet counter-drone platform is the main catalyst, with its debut at I/ITSEC in Orlando from November 30 through December 3. Investors should note a gap in how it is framed. The call presented it as a product launch, with integration into the Lattice C2 platform completed. The release states that development, integration, testing and customer evaluation remain necessary before commercialization. Management itself called defense revenue unpredictable and in its infancy. Expect a showcase, not a revenue event, in the near term.
The risks are concrete:
- **Going concern.** The 10-Q carries substantial doubt about the company's ability to continue as a going concern.
- **Cash burn.** Operating cash burn reached $7.4 million over nine months, including $2.7 million in Q3.
- **Runway.** Cash and short-term investments of $7.6 million are the highest since September 2023, but cover only about three quarters at the recent burn rate.
- **Dilution.** The share count rose from 22.9 million at year-end to 60.7 million. Management says it will keep evaluating debt and equity financing, so bears have legitimate ammunition on further dilution.
- **Turnover.** Heavy leadership and board changes, plus ongoing controls remediation, add execution risk.
The market setup offers little external anchor. With no consensus, no Whisper and no sentiment reading, the stock trades on financing and narrative rather than against an estimate bar. Shares opened at $1.43 after the August report, and the 200-day moving average sits at $1.12. The more relevant overhang is the near-certainty of additional capital raises at whatever price the market offers.
The bottom line is that LASE delivered a cleaner balance sheet, a leaner cost structure and a return to modest sales growth, which is a meaningful repair job after a difficult stretch. The per-share improvement, however, owes much to the absence of last year's deemed dividends and to a far larger share base. Gross margins remain deeply negative, and the business still depends on outside capital to fund a counter-drone ambition that is not yet commercial. Until gross margin turns positive and defense interest converts into contracts, this is a financing-dependent turnaround story rather than an earnings story.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-19 | |
| Nov-12 | |
| Nov-12 | |
| Nov-09 | |
| Nov-03 | |
| Oct-28 | |
| Oct-22 | |
| Oct-20 | |
| Oct-16 | |
| Sep-15 | |
| Sep-10 | |
| Sep-03 | |
| Aug-27 | |
| Aug-24 | |
| Aug-14 |
