Hyperion DeFi's $1.23 EPS Rides HYPE's Rally, But Its Real Milestone Is A First Positive Core Operating Quarter
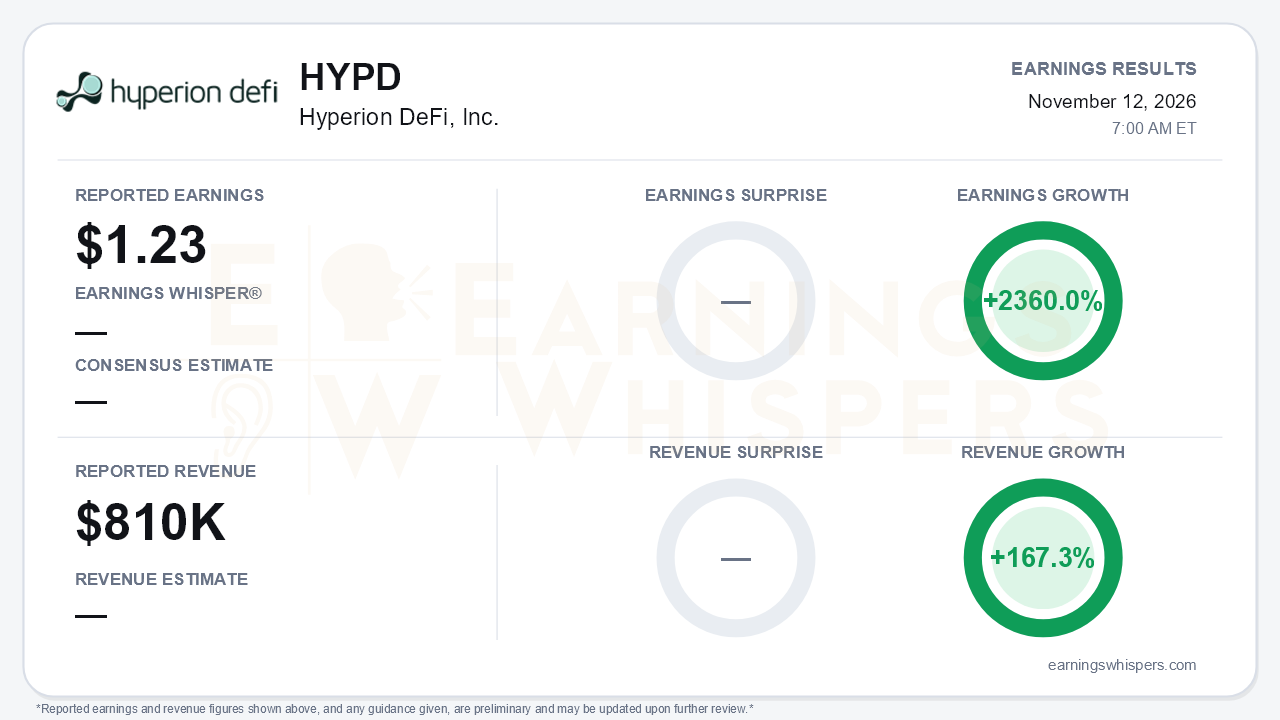
Hyperion DeFi reported third-quarter earnings of $1.23 per diluted share on GAAP revenue of $0.81 million. Earnings grew 2360.0% year over year and revenue rose 167.3%. There was no consensus estimate to measure against, and the headline EPS says more about the price of HYPE than about the business. GAAP net income reached a record $39.6 million, the company's third straight record. Nearly all of it came from roughly $44 million of realized and unrealized digital-asset gains as HYPE climbed from $65.0 to $90.8 during the quarter. The more meaningful development sits beneath that. Core operating earnings turned positive at $0.6 million, the first positive quarter since the DeFi pivot, compared with a $1.2 million loss in Q2. Adjusted net operating cash flow also edged positive at $0.1 million. Management had targeted breakeven by year-end, so it arrived one quarter early.
The quality of the operating beat deserves scrutiny. Adjusted gross profit rose 143% sequentially to $2.8 million, above the $2.0 to $2.5 million guided on September 8. However, $1.3 million of that came from ecosystem rewards, about 46% of the total. Those rewards consisted of a $505,000 receipt of 2Z tokens and a $750,000 mark on Skew equity the company is owed, valued at Skew's latest raise. Management itself calls this segment volatile and timing-dependent. Excluding ecosystem rewards, adjusted gross profit grew 45%, a healthy acceleration from the 17% to 20% sequential pace earlier in the year but well short of the headline 143%.
Common shareholders should also note the capital structure. Of the $39.6 million in net income, about $19.4 million was allocated to preferred holders, leaving roughly half for common stock.
The operating mix shows real progress alongside some softer spots.
- **DeFi monetization:** Up 112% to a record $334,000. This validates the redeployment of 1 million HYPE into the Entropy (HIP-3) and Skew (HIP-4) partnerships after the USDH stablecoin sunset depressed Q2.
- **Yield enhancement:** Up 14% to $381,000.
- **Staking yield multiple:** Rose to 3.6x base from 2.2x.
- **Staking:** The 49% gain in staking yield was purely a price effect. HYPE earned from staking and validating was flat at about 10.9 thousand tokens versus 11.1 thousand.
- **Validator commissions:** Stalled at $41,000 despite adding Gemini and Blockdaemon as delegation partners.
- **Operating expenses:** Fell just 4% to $2.2 million, short of the 10% to 20% decline floated on the Q2 call. Residual biotech costs are expected to end in Q4.
Guidance is where bears have legitimate ammunition. Management reiterated full-year adjusted gross profit of $7 million to $8 million. That target has already been raised twice, from $4 million to $6 million at the start of the year to $5 million to $7 million and then to the current range in September. But with $4.9 million booked year-to-date, the reiterated range implies Q4 of roughly $2.1 million to $3.1 million. The low end would be a sequential decline. The balance sheet also changed in two directions:
- **Debt and buybacks:** The $8.6 million Avenue Capital loan is gone, leaving no long-term debt. A $20 million buyback has started, with 240,124 shares repurchased at about a 30% discount to net assets.
- **Token base:** Funding the payoff required selling about $13 million of HYPE. Gross tokens fell to 1.85 million from 2.04 million, shrinking the base that generates staking income.
The catalyst list did lengthen. It includes the DoubleZero data-feed business, an Anchorage collateral integration for natively staked HYPE, and a potential DOMA token allocation through D3. Management also pointed to moves by Kraken and ICE toward regulated HIP-3 access, which could create demand for 500,000-HYPE deployer stakes. Many of these depend on early-stage partners and regulatory outcomes.
The market setup is more complicated than the fundamentals imply. Net asset value jumped 36% to $182.4 million during the quarter, yet the stock sat at $2.71 heading into the report. That is 2.5% below the $2.78 open after the August release and 19% below the 200-day moving average of $3.35. Shares peaked at $4.17 on September 24 and slid to a $2.36 low on November 6. They entered earnings 35% off that high and only modestly above the bottom of the inter-earnings range. Investor sentiment turned from slightly positive (0.03) to slightly negative (-0.09). That is a modest shift, but it points the same way as the price action. The AVWAP trend reading remains negative.
The bottom line is that Hyperion DeFi delivered the operating inflection it promised. Core profitability and positive operating cash flow arrived early, the debt is retired, and capital is now being returned. The headline earnings, however, are a HYPE-price story, and nearly half of the operating beat came from lumpy token and equity receipts. The guidance math leaves room for a flat-to-lower Q4. The persistent discount to net assets suggests investors are not yet paying for the operating layer. Sustaining ex-rewards growth while working from a smaller token base is the test for the next quarter.
Read our earnings preview for Hyperion DeFi, Inc.: https://www.earningswhispers.com/article/HYPD/22880
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 1 hour | |
| 2 hours | |
| 4 hours | |
| Nov-04 | |
| Oct-19 | |
| Oct-02 | |
| Sep-30 | |
| Sep-28 | |
| Sep-24 | |
| Sep-08 | |
| Aug-24 | |
| Aug-13 | |
| Aug-12 | |
| Aug-12 | |
| Jul-29 |
