Franco-Nevada Beats On EPS, But A Slipping Precious-Metals Core And Mid-Range GEO Guidance Temper The Quarter
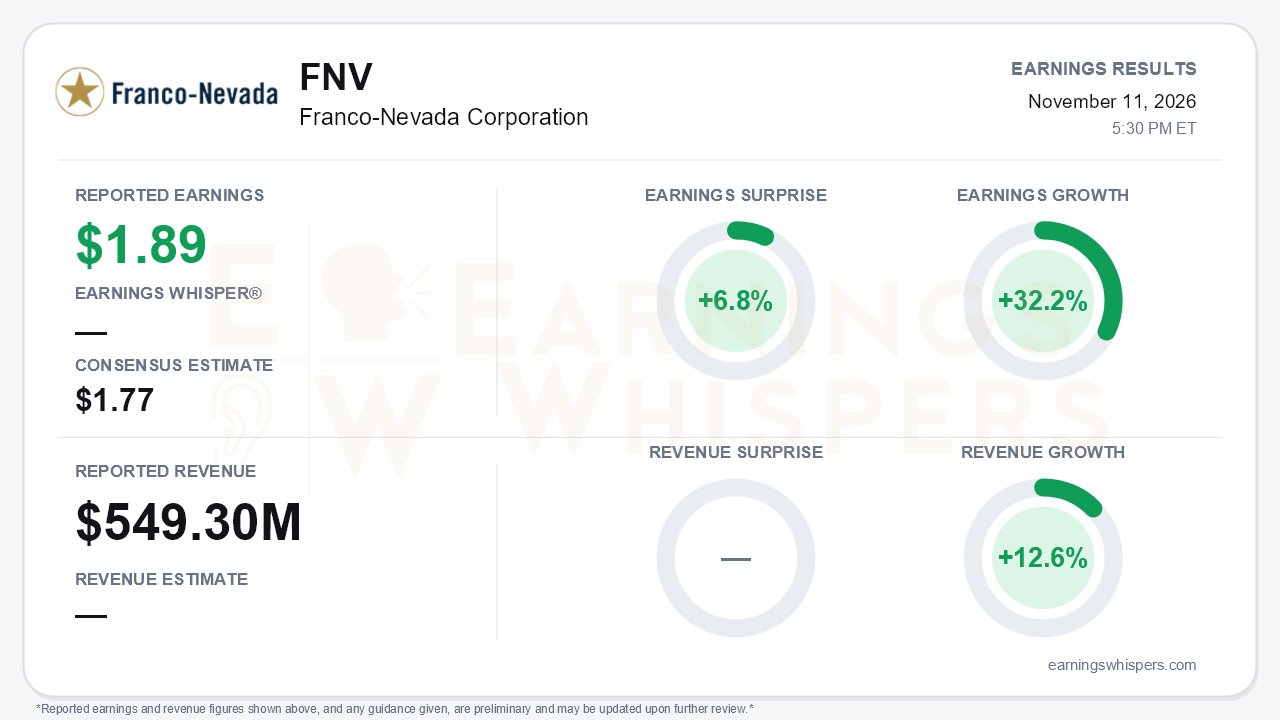
Franco-Nevada reported third-quarter adjusted earnings of $1.89 per share, beating the $1.77 consensus estimate by 6.8% and rising 32.2% from a year ago. Revenue grew 12.6% to $549.3 million. The headline is clean, but it does not reflect the more important development. Revenue growth slowed sharply from +77% in Q1 and +57% in Q2. Gold equivalent ounces sold fell 6% to 130,435, and management pulled its full-year outlook from the 'upper half' of the GEO range back to the 'mid-range.' Higher commodity prices delivered the beat. Volumes did not, and that is the central tension.
The quality of the beat deserves scrutiny. Adjusted net income rose 33% to $364.5 million, but the call analysis notes this included a $32.8 million Barbados tax reversal. Income tax expense fell to $59.2 million from $74.9 million despite much higher pre-tax income. GAAP net income of $395.5 million ($2.05 per share) was further lifted by a $10.3 million Cobre Panamá impairment reversal and $22.1 million of foreign exchange and other income. The call summary cited a $10.6 million reversal, but the release figure is $10.3 million.
Underlying profitability remains exceptional. Adjusted EBITDA margin was 89.9%, up from 87.6% a year ago, yet it slipped from about 91.2% in Q2. Margin per GEO eased to roughly $4,200 from $4,534 in Q1. Revenue of $549.3 million also sat below Q1's $650.7 million, so sequential momentum has clearly faded.
The operating story beneath the numbers is a weaker precious-metals core propped up by oil:
- **Precious metals:** Precious-metal GEOs fell 7% year over year to 110,904, against gains of 23% in Q2 and 17% in Q1. The shortfall came from heavy rainfall at Guadalupe-Palmarejo and Candelaria, delivery timing at Antapaccay, and lower Cobre Panamá volumes.
- **Diversified assets:** Revenue climbed to $86.8 million from $67.1 million, with U.S. energy rising to $50.8 million on Permian well activity, Continental volumes and stronger realized prices.
- **Guidance mix:** Gold guidance dropped to 355,000-385,000 ounces from 360,000-400,000, and the silver and PGM ranges also came down. Diversified revenue guidance was raised to $300-$330 million from $245-$285 million. Total GEO guidance narrowed to 525,000-555,000 from 510,000-570,000.
The mid-range call stands even though Cobre Panamá stockpile ounces (about 10,000 GEOs in 2026) and oil upside are now baked in. That implies the core mining portfolio is running below plan. Management itself described oil prices above $85 WTI as volatile, so bears have legitimate ammunition on the durability of the upside.
The forward catalysts are real but cut both ways:
- **Côté buyback:** IAMGOLD's exercise of its 50% buyback brings at least $525 million in cash in December. It also halves the royalty to 3.75% from January 2027, the same year the Candelaria stream steps down.
- **Cobre Panamá:** The Interministerial Commission recommended negotiating a settlement and potential restart framework, and the first 3,716 stream GEOs arrived. The call flagged the October earthquake as a source of delay in the negotiation process, although stockpile processing resumed after one day.
- **Development pipeline:** Copper World reached a final investment decision, Ottawa committed C$1 billion to Ring of Fire roads, Coroccohuayco land access was secured, and Bullabulling is now fully funded. Exploration success at Porcupine, Hemlo and Musselwhite adds longer-dated optionality.
- **Capital deployment:** Available capital climbed to $4.8 billion from $3.1 billion at the end of 2025, with no debt. Management called the deal pipeline 'exceptionally vibrant' and skewing toward $1 billion-plus transactions. A large acquisition is the most obvious way to refill the 2027 volume gap.
Investor sentiment moved from essentially neutral (0.006) to modestly positive (0.160). That is a meaningful but not dramatic shift toward optimism heading into the print. Price action has been far more muted. Shares have gained just 3.1% since the open following the August report and sit about 3.7% above the 200-day moving average of $239.81. That is a modest cushion for a company posting record year-to-date revenue, EBITDA and cash flow. The Earnings Whispers trend readings lean negative, with AVWAP negative and price trend only neutral. That fits a market treating Franco-Nevada as a high-quality but fully appreciated gold proxy rather than a growth story.
The bottom line is that Franco-Nevada beat on earnings largely because of commodity prices, a tax benefit and energy strength, while its precious-metals volumes went backward and GEO guidance lost its upper-half tilt. The balance sheet and the Côté cash give management unusual firepower, and Cobre Panamá offers genuine upside. Even so, the 2027 setup now depends heavily on whether that capital is deployed into meaningful new production before the Côté and Candelaria step-downs bite.
Read our earnings preview for Franco-Nevada Corporation: https://www.earningswhispers.com/article/FNV/22831
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 12 hours | |
| Nov-11 | |
| Nov-11 | |
| Nov-11 | |
| Nov-11 | |
| Nov-03 | |
| Oct-13 | |
| Oct-05 | |
| Oct-01 | |
| Sep-30 | |
| Sep-30 | |
| Sep-28 | |
| Sep-16 | |
| Sep-13 | |
| Sep-09 |
