Data I/O's Loss Widens As Organic Sales Slip, But The V-TEK Deal Puts A Rebuilt Company In Play
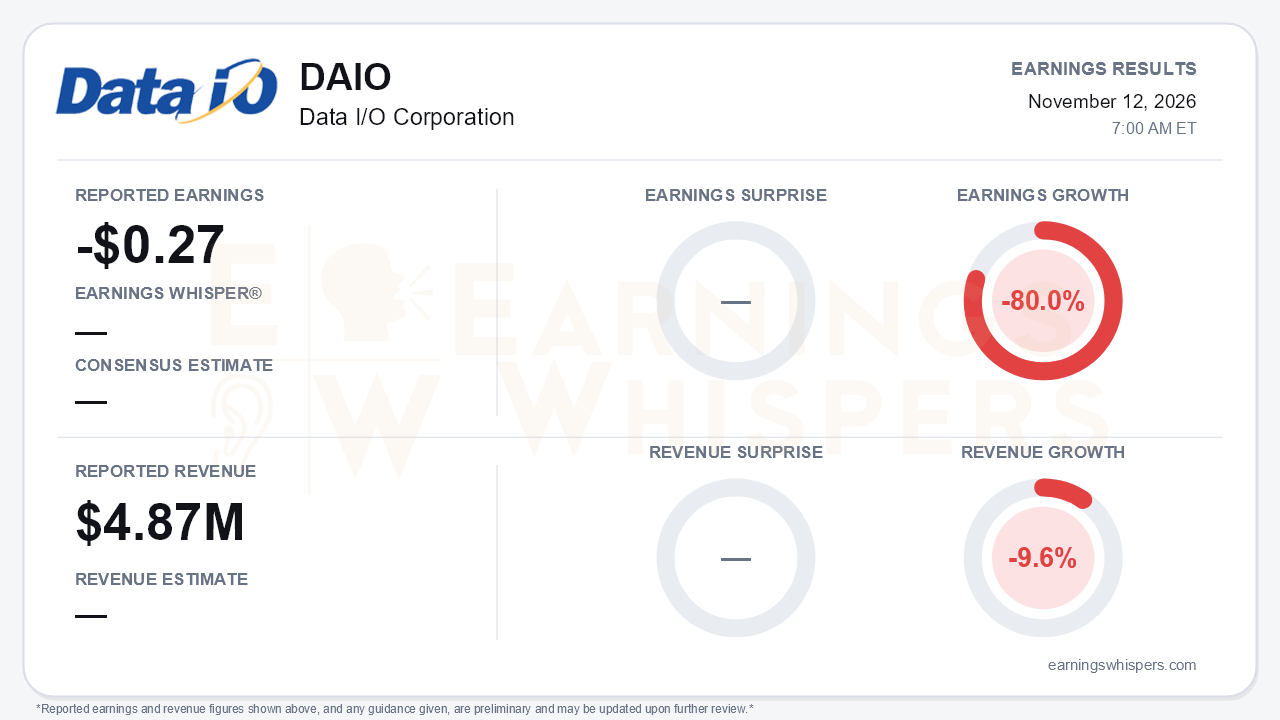
Data I/O's third quarter matters less for what the legacy business reported than for what management closed after it. On the reported numbers the quarter was weak. The company lost $0.27 per share on revenue of $4.87 million. Earnings fell 80.0% year over year as the net loss widened from $0.15 per share, and revenue declined 9.6%. There was no consensus estimate to measure against. Still, the deterioration is clear on a sequential basis too: sales slipped from $5.2 million in Q2, and the net loss grew from $1.6 million to $2.7 million. That is the central tension. The standalone business is still shrinking at the top line, while the investment case has shifted to the $23 million V-TEK acquisition, which management expects to roughly double revenue and be accretive to earnings.
The quality of the organic quarter is mixed. Gross margin was the bright spot, rising to 58.0% from 57.0% in Q2, 49.5% in Q1 and 43% in Q4 of last year, and well above 50.7% a year ago. That improvement deserves some scrutiny. Management credited the sale of several lower-cost units alongside value-based pricing and operating efficiencies, so part of the gain reflects product mix rather than purely structural improvement.
The cost side moved the other way. Operating expenses rose to $4.9 million, driven by roughly $1.4-$1.5 million of one-time items:
- deal and financing costs of about $0.8 million;
- the IT/ERP transition;
- a non-cash inventory reserve adjustment.
New interest expense of $624,000 also widened the loss. Stripping out those items, adjusted EBITDA was a loss of just $71,000, near breakeven for a second straight quarter. That compares with a $563,000 loss a year ago, though it slipped from a slight positive of $39,000 in Q2.
Beneath the headline, the order book tells a split story. Bookings edged up to $5.0 million from $4.9 million in Q2, $4.2 million in Q1 and $3.1 million in Q4. Management argued that platform demand has inflected after a prolonged downturn, helped by edge AI and robotics. Platform sales rose to 52% of revenue, while consumable adapters, the recurring base, were soft. Automotive remains weak. More concerning, standalone backlog fell to $1.5 million from $2.1 million in June and $2.6 million in March, and deferred revenue continued to decline. Bookings are stabilizing, but they are not yet building a cushion.
The call is where the story improved, and management's tone was notably more confident. Pro forma for V-TEK, Q3 revenue would have been about $10 million with roughly $8.8 million of backlog, and some V-TEK core systems are booked out through Q2. The deal adds:
- immediate Programming-as-a-Service capability through A&J Programming;
- exposure to AI photonics customers such as Ciena;
- aerospace and defense, and satellite communications.
Management also cited a first purchase order from Tesla's Optimus robotics program, with one to three more systems expected in Q4. It said about half of cost synergies would be actioned within 90 days. A security platform acquisition announcement is expected within roughly 30 days from a remaining pipeline of about $80 million, and new core products are slated for Q1 2027. The organic cash-neutral revenue threshold also fell to about $5 million per quarter, from $5.25-$5.5 million in Q2.
Bears have legitimate ammunition, however. Management gave no forward revenue or synergy guidance. It also did not explicitly reaffirm its earlier target of organic positive operating cash flow by the end of 2026. Cash fell to $9.4 million from $10.8 million and is expected to fluctuate over the next 60 to 90 days. Funding the deal required a $13.25 million private placement on top of the June raise, plus a $7.5 million credit line. That means further dilution and new leverage at the same time the company takes on integration of a business as large as itself. A second acquisition close behind the first raises execution risk further.
The market has not given management the benefit of the doubt. Shares fell 20.8% from the $3.13 open after the August report to $2.48 heading into this release, leaving them about 16% below the 200-day moving average of $2.96. Investor sentiment was essentially unchanged and still negative, edging from -0.257 to -0.243. The Earnings Whispers trend signals are mostly negative, with only momentum reading positive.
The bottom line is that Data I/O delivered a weak standalone quarter, with lower sales, a wider loss and shrinking backlog. Those results were offset by real margin gains and a near-breakeven adjusted cost structure. The investment setup now rests almost entirely on V-TEK: whether the combined company can deliver the promised revenue doubling and accretion without guidance, while absorbing dilution and a fast-moving acquisition agenda. Investors arrived skeptical, and the next two quarters of integrated results will need to prove that this is more than a rebranding of a shrinking core.
Read our earnings preview for Data I/O Corporation: https://www.earningswhispers.com/article/DAIO/22990
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| Nov-12 | |
| Nov-12 | |
| Nov-06 | |
| Nov-03 | |
| Nov-02 | |
| Oct-21 | |
| Oct-19 | |
| Oct-19 | |
| Aug-13 | |
| Aug-12 | |
| Aug-11 | |
| Jul-30 | |
| Jul-29 | |
| Jul-16 | |
| Jul-10 |
