BK Technologies Posts Record Q3 Revenue, But Slowing Growth And A Roof-Collapse Guidance Cut Overshadow The Quarter
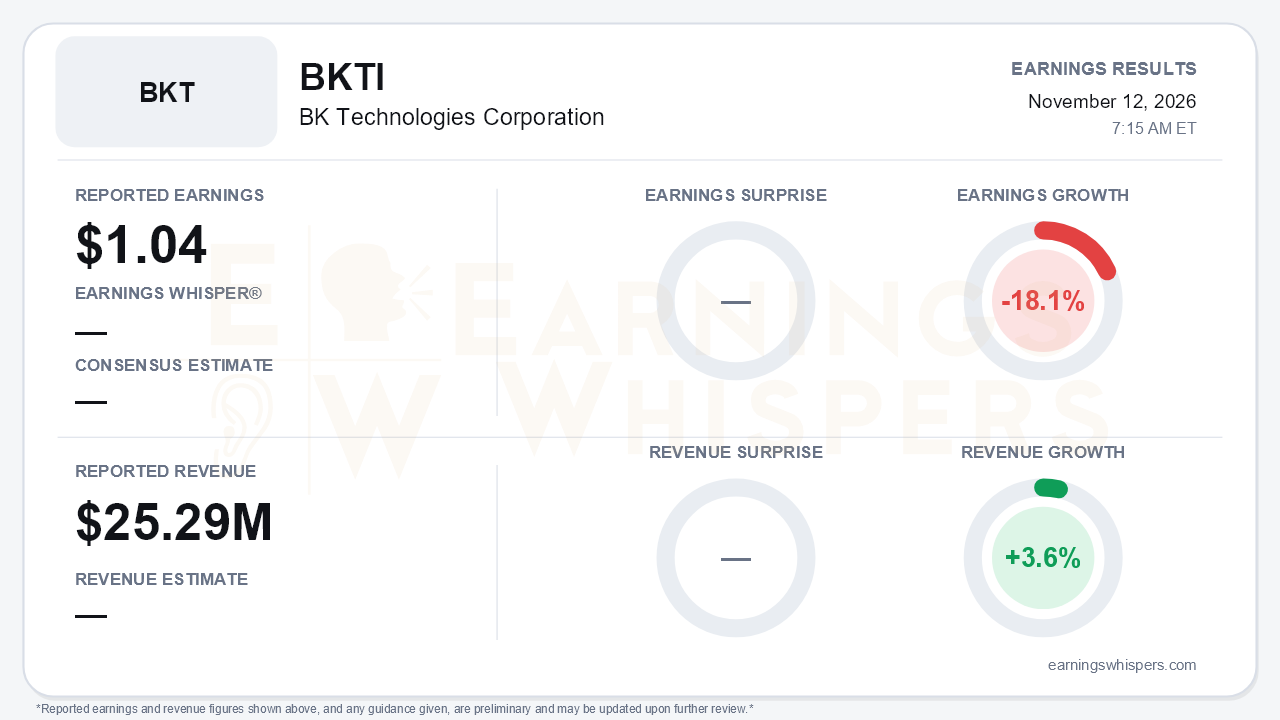
BK Technologies reported third-quarter earnings of $1.04 per share on revenue of $25.29 million. Earnings fell 18.1% year over year and revenue grew 3.6%. No consensus estimate or Earnings Whisper was available, so the quarter cannot be framed as a beat or miss. That leaves the underlying trends to carry the story, and they point to deceleration. Management called the $25.3 million a record third quarter. Even so, revenue growth slowed sharply from 11.8% in the first quarter and 10.6% in the second. The company also cut full-year guidance for the first time this year after an October 8 roof collapse at its West Melbourne headquarters disrupted BKR 9000 production. The central tension is whether investors view the guidance reset as a one-time timing issue, as management insists, or whether it obscures a growth slowdown that was already visible before the storm.
The quality of the quarter deserves scrutiny. Management highlighted a 9% increase in GAAP net income to $3.7 million, or $0.93 per diluted share, which outpaced revenue growth. That gain came below the operating line. Operating income fell to $4.4 million from $4.8 million, and operating margin compressed to 17.5% from 19.8%. The net income increase depended on a lower tax provision and higher interest income. On the company's non-GAAP basis, adjusted diluted EPS declined to $1.16 from $1.24, and adjusted EBITDA margin slipped to 20.5% from 21.5%. Gross margin of 50.7% rose from 49.9% a year ago and stayed above the 50% target. However, it fell from 51.9% in the second quarter and 51.8% in the first, so the mix tailwind appears to be fading. SG&A rose to $8.4 million from $7.3 million, driven by BKR 9500 hardware spending and BK ONE software development. That is deliberate investment, but it is now absorbing most of the revenue growth.
The composition of demand is also narrowing. Federal orders accounted for more than 60% of third-quarter revenue, led by delivery of 3,000 BKR 5000 Orange radios to the U.S. Forest Service, which has adopted the radio as its new standard. That is a meaningful franchise win. However, recognized state and local revenue declined year over year. A quarter carried by one large federal customer while the broader public-safety base contracts is less durable than the headline record suggests.
The guidance cut is substantial:
- Full-year revenue is now about $85 million, down from at least $90 million.
- GAAP EPS is now $2.40, down from $3.15.
- Adjusted EPS is now $3.15, down from $3.55.
Nine-month GAAP diluted EPS already stands at $2.39 and adjusted EPS at $3.04, so the new outlook implies a nearly breakeven fourth quarter on a GAAP basis. Management says deferred BKR 9000 orders have seen no cancellations, expects production to normalize during the first quarter, and does not expect 2027 to be materially affected. Bears have legitimate ammunition, though:
- Roof remediation costs have not been quantified.
- Those costs are not excluded from EPS guidance.
- The "upside" framing management used earlier in the year has disappeared.
The call preserved a credible longer-term growth story. FCC certification for the BKR 9500 in-vehicle multiband radio is now expected by year-end, earlier than the "early 2027" timing cited last quarter. Mass production remains on track for March 2027, with materials for the first 2,000 units largely secured. The $3 million Tango Tango convertible note adds a software foothold and a sales channel to more than 1,500 public-safety agencies. The new El Paso distribution center has cut lead times to two to five days from seven to ten. The board doubled the buyback authorization to $10 million, with about $8.4 million available. Potential business-interruption insurance recoveries and tariff refunds are excluded from guidance and could offset some of the damage. The balance sheet supports all of this: $29.2 million in cash, no debt, and $18.9 million in trailing-twelve-month after-tax free cash flow. Growth in that cash flow measure has slowed, however, from 49% to 25%.
Current sentiment and price data were not available. For reference, shares opened at $80.00 after the August report, almost exactly in line with the current 200-day moving average of $79.91. That suggests the stock entered this period with little directional cushion in either direction.
The bottom line is that BK Technologies delivered a record revenue quarter that was weaker than it looks. Growth decelerated to low single digits, operating margins contracted, and results leaned heavily on one federal customer while state and local revenue declined. The roof collapse provides a clear explanation for the guidance cut, and management's timing argument is plausible. Still, the slowdown predates the storm. The BKR 9500 ramp in early 2027 now carries more of the burden of proving that growth can reaccelerate.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 7 hours | |
| Oct-29 | |
| Sep-16 | |
| Sep-11 | |
| Aug-26 | |
| Aug-13 | |
| Aug-13 | |
| Aug-13 | |
| Aug-12 | |
| Aug-03 | |
| Jul-30 | |
| May-14 | |
| Apr-30 | |
| Apr-21 |
