Octave Intelligence Beats Its Own Q3 Bar, But A Flat Q4 Revenue Guide And Slowing SaaS Keep The Recovery Story Unproven
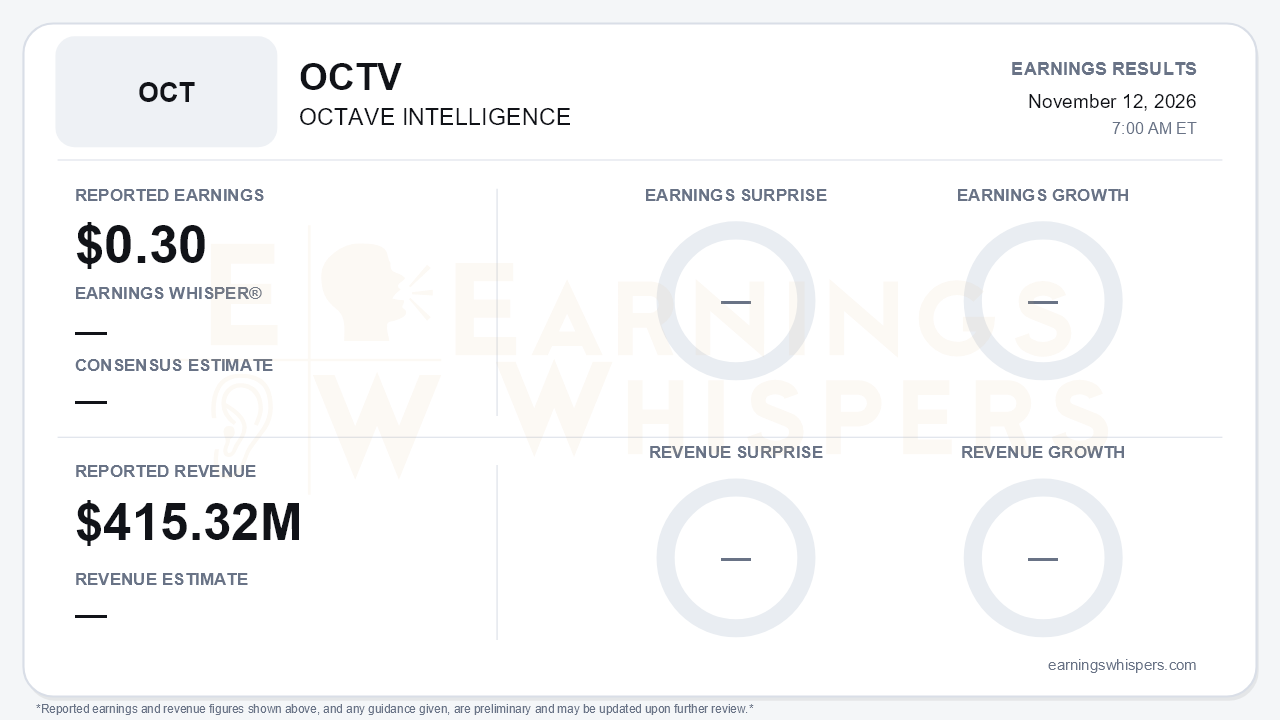
Octave Intelligence (NASDAQ: OCTV) reported earnings of $0.30 per share on revenue of $415.32 million for the September quarter. No consensus estimate was available, so the useful benchmark is management's own guidance, and Octave cleared it. Total revenue grew 6% on an organic constant-currency basis, ahead of the 2-4% ($400-410 million) range set on the second-quarter call. That is a sharp turn from the 1% organic decline in Q2. The central tension is that this beat-and-nudge quarter came alongside a fourth-quarter outlook implying roughly flat organic revenue. Investors are left with a business that executed better in Q3 but has not yet shown durable top-line acceleration.
The earnings figures need some untangling. Earnings Whispers' normalized $0.30 sits between the company's GAAP diluted EPS of $0.22 and its adjusted EPS of $0.32. On Octave's own adjusted basis, per-share earnings were flat year over year at $0.32, and adjusted net income slipped to $86 million from $87 million despite the revenue growth. Two post-spin costs absorbed the operating improvement:
- New interest expense of about $5 million on the term loans taken on to fund a $625 million payment to Hexagon.
- A higher tax charge.
GAAP net income jumped to $59 million from $14 million, but that comparison is flattered. The quarter included a $26 million gain on the sale of buildings, and the prior-year period carried $39 million of restructuring charges. Year to date, a $2.13 billion impairment still leaves Octave deep in a GAAP loss. Free cash flow of $65 million was essentially unchanged, though operating cash flow fell to $95 million from $102 million. Lower software capitalization kept capital spending down.
Beneath the headline, the mix is improving more convincingly than the total. Recurring revenue rose 5% to $291 million, at the top of guidance. ARR grew 7% to $1.17 billion. Monthly subscription licenses improved to 6% growth from 5% in Q2, and management called September the strongest month. Large-customer counts also rose: 450 customers above $500,000 in ARR (from 438) and 200 above $1 million (from 186). Cross-sell accounted for more than 10% of new ARR, and EMEA grew double digits. Adjusted operating margin reached 28%, ahead of the roughly 27% guide and up about 100 basis points year over year. Management put the underlying improvement nearer 300 basis points once lower R&D capitalization is excluded.
The weak spot is the growth engine itself. The CEO cited 18% SaaS growth in the release, while the call put it at 17%. Either way, that is a deceleration from 21% in Q2. Gross margin also eased to 76% from 77%. The call's tone shifted from the defensive posture of the Q2 guide cut to something more confident, but the guidance did not change much:
- Full-year recurring revenue was nudged up to 5.5-6% organic growth.
- Full-year total revenue was only narrowed, to 0.5-2% organic.
- Q4 total revenue is guided to a range of -2% to +2% organic, as perpetual license revenue is expected to fall high-teens to roughly 20%.
- Large public-safety perpetual deals again failed to close and remain excluded from the outlook.
The forward catalysts are real but back-end loaded. Octave announced the acquisition of Cerebre (spelled "Cerebrae" on the call), an AI-driven plant-modeling company. Management said it generates roughly $8 million in revenue and cost about $130 million, around 16 times revenue. The deal is meant to anchor the context layer of an agentic AI platform targeted for general availability in early 2027, with consumption-based pricing under test. Multi-tenant SaaS releases are slated for the first half of 2027, alongside Azure Marketplace listings and a push toward Microsoft co-sell. Bears still have legitimate ammunition:
- Pro forma net debt rises to about $350 million.
- Cerebre's ARR contribution is being offset by currency headwinds in reported ARR, so the 6-8% ARR outlook was held rather than raised.
- China was softer, APAC mixed, and the Middle East remains uncertain.
The $200 million buyback, running through 2029, is framed primarily as dilution offset with flexibility for more. Its cap of 10.75 million shares implies an average price ceiling of roughly $18.60. That sits close to the stock's 200-day moving average of about $18.18. No sentiment readings, current price or inter-earnings range data were supplied, so the market setup has to be judged largely on fundamentals. The 200-day average is the most relevant reference point as investors digest the outlook.
The bottom line is that Octave delivered the clean, above-guidance quarter it needed after Q2's stumble. Recurring revenue, large-customer growth and margins are moving the right way. However, the Q4 guide implies a flat top line, SaaS growth is slowing, and the AI platform payoff is a 2027 story. Until perpetual declines stabilize and SaaS reaccelerates, this reads as improving execution rather than a confirmed growth inflection.
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 4 hours | |
| 8 hours | |
| Nov-11 | |
| Nov-09 | |
| Oct-27 | |
| Oct-15 | |
| Oct-06 | |
| Sep-23 | |
| Sep-15 | |
| Sep-14 | |
| Sep-02 | |
| Aug-31 | |
| Aug-19 | |
| Aug-13 | |
| Aug-12 |
