Ascendis Pharma Beats As YORVIPATH Scales And Margins Jump, But The 42% Margin Flatters The Run Rate
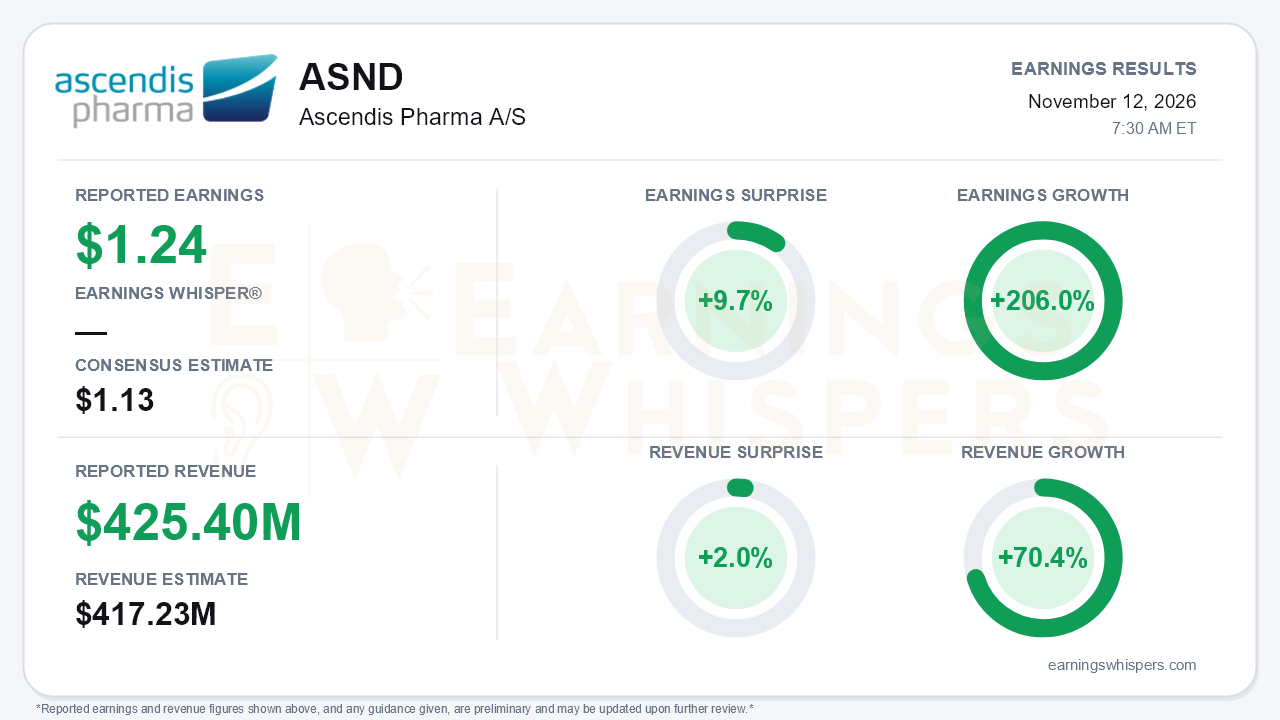
Ascendis Pharma delivered a clean beat in the third quarter. Earnings were $1.24 per share, ahead of the $1.13 consensus by 9.7%, and revenue was $425.4 million, 2.0% above the $417.23 million estimate. Earnings grew 206.0% year over year and revenue grew 70.4%. In the company's own euro reporting, IFRS net profit was €74 million, or €1.08 per diluted share, against a €61 million loss a year earlier. The company is now solidly profitable rather than narrowing losses. The central takeaway is that Ascendis is generating real operating leverage from a three-product rare endocrine franchise. The sharpest part of the improvement, the margin step-up, was helped by spending timing that may not repeat.
The top line was driven overwhelmingly by YORVIPATH, which reached €291 million, up 103% year over year. Total product revenue was €366 million, up 89%. Headline total revenue grew more slowly than product sales because the prior-year quarter included €13 million of milestone revenue that did not recur, so the commercial trend is stronger than the reported total suggests. Earnings quality is reasonable at the operating level. IFRS operating profit was €125 million, a 34% margin, versus €11 million and 5% a year ago. Non-IFRS operating profit was €156 million, a 42% margin, with share-based compensation of about €31 million as the main adjustment. Non-IFRS EPS of €1.71 compares with €0.40 a year ago.
The sequential progression is impressive. Non-IFRS operating margin rose from 22% in Q1 to 27% in Q2 to 42% in Q3. But operating expenses fell to €217 million from €249 million in Q2, and the call made clear that part of that drop reflects the timing of commercial initiatives and lower litigation costs. That is the quality question beneath the beat. A 42% margin is a high-water mark, not a new floor.
The underlying demand picture is healthier than the margin math alone. YORVIPATH sales moved from €197 million in Q1 to €252 million in Q2 to €291 million in Q3. The sequential dollar gain narrowed from Q2 to Q3, however, and U.S. new-patient demand was described as steady at roughly 1,000 per quarter rather than accelerating. Incremental momentum is increasingly coming from outside the U.S. The drug is now available in more than 40 countries, 13 of them fully commercial, with 15 more full-commercial markets expected in 2027. A national U.S. direct-to-consumer campaign launched in September is the domestic lever to watch. YUVIWEL doubled to €16 million in its second launch quarter. U.S. enrollments rose to about 340 from more than 220 at the end of July, and reimbursement approvals improved to more than 80% from more than 65%. SKYTROFA rose to €59 million but remains a 'relatively stable' U.S. story.
Guidance moved in the right direction. Full-year operating cash flow is now expected to be at least €600 million, up from more than €500 million in Q2 and roughly €500 million at the start of the year. The nine-month figure includes €158 million from the priority review voucher sale. Cash rose to €964 million even as the company repurchased about $459 million of stock year to date. Management also layered a €10 billion 2035 revenue ambition on top of its €5 billion 2030 goal and teased a new metabolic/cardiovascular therapeutic area. Forward catalysts include:
- the EC decision for TransCon CNP before year-end;
- a Germany launch in Q1 2027;
- infant pivotal data in Q3 2027.
Bears have legitimate ammunition, however. The Phase 3 CNP-plus-hGH combination trial was redesigned after FDA feedback with an added hGH-only arm, which enlarges the study and delays it by a few months. An oral FGFR3-targeting competitor is expected to enter achondroplasia next year, and Ascendis has responded with a citizen petition on safety. The company is also ending regular disclosure of new-patient enrollment metrics just as YUVIWEL's launch trajectory becomes a key debate, which reduces visibility for investors.
Investor sentiment improved meaningfully into the report, rising to 0.34 from 0.13 at the prior release. Sentiment is clearly positive but not euphoric. Price action has been choppier than the fundamentals. Shares closed at $259.28 ahead of the report, only 3.6% above the opening after the August release. They have rebounded about 18% from an October 8 low of $219.52 but remain roughly 5% below the September high of $272.47. The stock sits 8.3% above its 200-day moving average, and the Earnings Whispers trend readings are broadly positive. The market has been rewarding the story, but it has not yet priced in a breakaway.
The bottom line is that Ascendis posted a high-quality commercial quarter, with YORVIPATH scaling globally, YUVIWEL gaining reimbursement traction and a raised cash flow outlook. These results support management's long-range ambitions. The 42% non-IFRS margin is partly a timing benefit, and U.S. YORVIPATH demand is steady rather than accelerating. The combination-trial delay, an oral competitor and thinner enrollment disclosure leave investors with more to underwrite on faith than the clean beat implies.
Read our earnings preview for Ascendis Pharma A/S: https://www.earningswhispers.com/article/ASND/22988
This earnings review was originally published on Earnings Whispers.
This article is for informational purposes only and is not investment advice. Earnings Whispers and its staff may hold positions in the securities mentioned. It is AI-assisted, based on proprietary Earnings Whispers data and company reports, and edited by Earnings Whispers staff.
Mentioned In This Article
Latest News
| 3 hours | |
| 6 hours | |
| Nov-10 | |
| Nov-06 | |
| Nov-06 | |
| Nov-05 | |
| Oct-26 | |
| Oct-20 | |
| Oct-16 | |
| Oct-16 | |
| Oct-06 | |
| Sep-15 | |
| Sep-14 | |
| Sep-14 | |
| Sep-09 |
